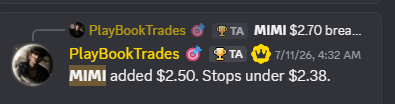
Definitely a nice way to start the week with a 58% overnight trade on $MIMI.
$2.50 -> $3.97 NHOD. 💰
For now, $4.15+ gives us another push for next leg if not we'll need to wait for setups off dips. 💸
Let's see how the rest of the week goes!
Paradis Research | $META the neocloud
Meta may build a cloud business to sell excess AI compute capacity.
TLDR:
- $META selling excess compute because they literally have no roadmap to use old gen capacity
- This is not bearish for neoclouds like $NBIS
- $META would instead dump old Hopper/Blackwell it overbought while renting new Vera Rubin capacity from $NBIS for 2027.
Just to frame Meta's own scale since it matters for what "excess" actually means:
- Meta has guided 2026 capex to ~$135B, up ~75% YoY.
- They've said they'll buy "millions" of $NVDA Blackwell + Rubin GPUs this year alongside Grace CPUs.
- While simultaneously scaling MTIA, their in-house training/inference accelerator designed w/ $AVGO.
Two implications:
1. At that spend, even a low % of "overbuilt" capacity is a multi $billion pool of resellable compute.
2. A cloud business is years from positively impacting Meta's rev mix which is still mainly from ads.
But naturally, the market has sold off the neoclouds today out of fear:
- $NBIS -14%
- $CRWV -13%
However, the threat to the incumbent neoclouds has been massively overstated ever since the news came out. I've been cringing reading bearish posts.
Per $NBIS March release, the two signed a 5 yr deal worth up to ~$27B:
- $12B of dedicated Vera Rubin capacity delivering early 2027
- Up to $15B of flexible capacity that Nebius intends to sell to third parties, with Meta buying whatever is left over as a backstop.
So Meta is simultaneously renting frontier compute from Nebius and floating the resale of its own.
Pretty funny lol.
Meta wants guaranteed compute allocation speed which Nebius with their Nvidia partnership can deliver.
While the capacity it would resell is older generation kit (Hopper, early Blackwell) it over ordered.
That segmentation dissolves most of the paradox and probably tells you the resale pool is marginal + ageing supply.
Naturally, the reflex reaction is to think that Meta will crush GPU pricing + breaks the compute shortage thesis:
If Meta tip from net renters (Microsoft rents from $CRWV and Nebius exactly because they're short on capacity) to net sellers, the marginal price of rented compute softens, and the neocloud and neoclouds get impacted.
But the bulk of the neocloud revenue is contracted and pre-paid over multi year deals.
Nebius's ~$50B backlog and CoreWeave's own book anchored by Microsoft insulate them.
And bitcoin miners like $IREN, $CIFR, $CORZ, $WULF, $GLXY etc sit further out on the risk curve, with more spot exposure.
Across the basket, Meta's resellable excess is just a marginal addition to supply rather than a flood like some will have you believe.
Then if Meta prove internally that selling excess compute is more profitable than ads...
They'll almost certainly increase capex next year to Google/Amazon levels to go build a cloud biz in full.
$INHD could be an interesting continuation setup if it clears and bases over $8.45.
Provided no liquidation follow ups after.
Current base is $5.40, under $5.40 means this intraday structure turns bearish for the first time today.
As a $NBIS and $BE shareholder, this makes me happy:
-> $NBIS entered an agreement with $BE worth up to $2.6B.
-> $BE will install, operate & maintain fuel cell systems for $NBIS, delivering ~250MW guaranteed / ~328MW installed capacity across three 10-yr phases.
For Bloom Energy:
- At full ramp, it would imply ~$260M of annualized service fee revenue from a single customer - meaningful against their top-line.
- They have commercial validation from $EQIX, $ORCL, and now $NBIS. A customer set that spans hyperscaler, neocloud and colocation.
For Nebius:
- They don't sign a $2.6B power capacity commitment unless they have the GPU allocation to fill ~328MW of installed compute capacity.
- Such a high power commitment probably means they've either:
(a) extracted very firm allocation guidance from $NVDA for FY27 deliveries.
(b) is pre-positioning physical infrastructure ahead of allocation confirmation.
Disclosure: I have a position in both Nebius and Bloom Energy.
POET’s teams in Singapore, Shenzhen and Malaysia include some of the brightest and most experienced engineers in our industry. They’ve chosen careers with $POET because they have examined our technology in detail and want to be part of the exciting journey ahead. #POETpowersAI connectivity with novel light sources and optical engines that are commercial-ready.
More to come from Asia this week.
https://t.co/oQqdxg0Ri3
I am normally an observer, but today’s post by @NMRtweet is an example of not believing everything you see online.
I will not be commenting on the actual performance of the company, but through a simple open source investigation, it is clear they did not visit $POET offices.
Please do your own research and stay safe.
I am normally an observer, but today’s post by @NMRtweet is an example of not believing everything you see online.
I will not be commenting on the actual performance of the company, but through a simple open source investigation, it is clear they did not visit $POET offices.
Please do your own research and stay safe.
Insane volume + premiums here on this $TSLA 495C 6/18
$8.6M on the line , won't know how much of this position they're still holding until Monday morning
@Ric_RTP Nobody is talking about the earnings of the pure AI model companies that’s allegedly will kill software companies because they don’t exist. I would love to see the profits of OpenAI, Claude, Anthropic and how they’ll kill software companies with VC money!!