Defensive driving typically involves anticipating others' mistakes and maintaining enough space and time to avoid crashes.
In India, however, this approach can be misinterpreted, as some may violate rules and act irresponsibly, assuming others will avoid collisions by driving defensively.
Some Road risks specific to Indian Roads are :
1. Lack of consistent enforcement
2. aggressive drivers with neither a fear of getting caught nor a crash, all due to optimism bias
3. Diluted responsibility, where people expect others to take care
4. In other countries,a very few poeple make mistakes on the road as there are strong deterrents against bad driving habits.
In India, without a standardized knowledge level across the population, people assume things and make up their own rules like bigger vehicle is always at fault etc.
So, how to drive peacefully without being burdened?
1. Observation --> Anticipation
2. See and Be Seen
3. Sometimes honk is necessary
4. Expect mistakes always and keep speeds in control in built up areas
5. Know about the limitations of the vehicle like blindspots and make up for the loss using observation/honk
6. Invest in a dashcam that can save from lot of hassles
7. Don’t carry every bad driver’s mistake home with you
8. Don't react emotionally for bad drivers
9. Follow safe driving habits like signalling,mirrors etc. Be Predictable
10. Don't consider it as a burden but consider it as acting smart in a broken system
Stuck in Pathankot or Dharamshala due to the current situation or the IPL?
We have a hotel in Dharamshala and dalhousie that can comfortably host needy tourists. Happy to help—just reach out. Please retweet so it reaches someone who might need it.
Contact - 8627042951
At 52, Goli Shyamala Garu's 150 km swim from Visakhapatnam to Kakinada is a story of extraordinary courage and determination. During six days, this daughter of Andhra Pradesh faced numerous challenges on her journey but ultimately prevailed with courage. Her journey is not just a shining example of Nari Shakthi, but a reflection of the power of the human spirit. She has also underscored the need to protect our precious marine life, inspiring millions through her admirable achievement. Congratulations, Shyamala Garu!
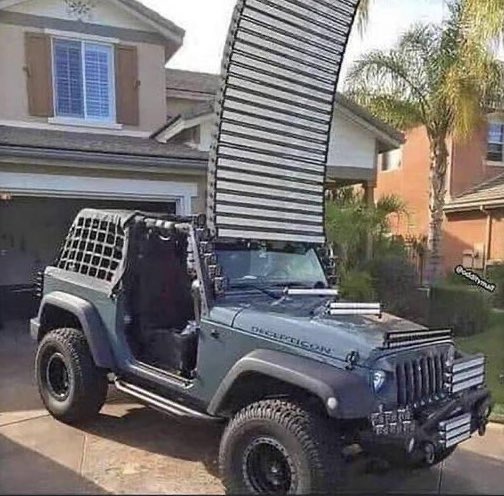
It is wild to me that this design got from someone’s cute idea (“Let’s put the Union Jack on the tail lights!”) through every step of production and regulation and onto the road, resulting in a right turn signal that points left and a left turn signal that points right
Startups: Here's a rough mental model of businesses in the 🇺🇸 market, pulled from census data sources:
Total U.S. employers = ~6 million
~5.5MM companies: 0-$25MM in revenue
~63,000 companies: $25MM - $250MM in revenue
~1,600 companies: $250MM - $1B in revenue
~700 companies: $1B+ in revenue
Mental Model Segmentation:
• Small Business: ~5.5MM companies
• Mid-market: ~63K companies
• Enterprise*: ~2,500 companies
A few thoughts:
1. The small business sector is massive, BUT it's a wild-wild west in that each firm is uniquely run, AND there are various owner incentives -- very little consistency from company to company; harder to unlock repeatability.
2. The mid-market is messy as it abuts two very different go-to-market strategies; one of high-volume sales (small business) and one of high-value sales (enterprise). You need to know which one you're leaning into, as it bifurcates here -- it's very dangerous to try and straddle both early on.
3. Enterprise has always been all about expansion opportunities ;)
*Enterprise includes companies with > $250MM in revenue.
Unsure if just clickbait, but this isn't SaaS dying, this is SaaS exploding.
The SaaS community has been talking about this exact pricing shift for over a decade. There are even reports on this very topic published annually (some by yours truly)! :)
Let me explain a bit 👇
Value based pricing that aligns incentives with business model has always been the goal, because that's the beauty of a recurring revenue model. It's the first model in the history of commerce that bakes the relationship with the customer directly into how you make money.
If the customer gets value - they keep paying/sticking around. If they don't, they leave.
"Patrick - isn't this how all commerce works?"
Absolutely not.
Your grocery store can't guarantee that you'll be there next week. There's no direct relationship, so they use hard and soft tactics (coupons and promotions) to bet you'll come in for your milk.
With recurring revenue you're in a symbiotic relationship with your customer until they stop seeing the value in your product. Doesn't matter what that product is. It's great for the company. It's great for the customer.
"PC - that's cute, but how does this relate to pricing? And why do some people hate recurring pricing?"
I got you.
Two reasons why Intercom and Zapier's new pricing didn't exist until today:
1. Billing systems suck/sucked
2. Customers hated this pricing until recently
Here's how pricing evolved over the past 20-30 years:
Phase 1 - "charge per user" days
Billing systems succcckkkeddd until recently. You couldn't track usage or consumption of a product, let alone hook that up to a payments product.
So how'd we charge?
Invoices. But that wasn't the problem - customers also hated the recurring revenue model, because they were getting similar software on a perpetual license (pay once), so why pay on a recurring basis?
Recurring software products compromised by charging on a per license/user basis. Less than 10% of products charged on anything besides licenses or features and those were all dev/engineering products (more on that in a minute).
But then came - magical value measuring software.
Phase 2 - we can measure value, let's charge on it
All of a sudden we had software that could measure how many emails were sent, contacts were in a database, or videos stored very easily AND hook that data up in realtime (or as close to realtime as possible) to a billing system.
So why not charge based on the exact value?!!
Customers hated it. They just got on board with paying a recurring fee, but now they had to get on board with paying based on how much they used? Software used to be unlimited use!?!? Also, how can they predict their costs for finance?
Companies comprised by still charging based on usage, but batching that usage - eg. a tier that charges $100 for up to 1k emails, $250 for 1k-2.5k emails, etc.
Customers got their predictability and companies got juicy expansion revenue baked directly into their pricing. During this phase we cross into 50% of all companies using a value metric.
But there's one major downside - some customers get screwed. Some are forced to pay recurring for something that should be free and is just a feature. Others don't use all the usage in their tier.
So we save them with Phase 3 👇
Phase 3 - unpredictable billing
Customers warm up to their bill not being the same every month. They realize super crucial apps like AWS and other engineering products are unpredictable, but necessary. They like that they only pay for what they use.
But they still want some predictability. Their finance teams piss and moan at them, but they also don't want prices to "get away from them".
Companies respond by adding more tiers with different bins of value metrics and some go much more usage based pricing
- eg. $500/month PLUS $10/month per 100 contacts. Companies want to go pure usage, but customers aren't quite there and that's mostly because companies suck at giving them predictability around how much they'll use. It's a give and take.
But then the dam starts to break and we get phase 4.
Phase 4 - the pure value era
Customers get comfortable enough and companies get good enough at giving predictability and transparency that you start to see the dam break.
Billing systems are nimble enough to handle this with a little bit of work. Shoutout to @PaddleHQ that built a ton of this two years ago.
Others will follow and we'll finally have a world of "monthly predictable revenue" versus "monthly recurring revenue." All of the same principles apply. We're now in a world where the vision can be fulfilled.
Well - that's it. I'm excited for the next ten years. All of this only gets better and better with AI and all the other magic coming.
Thanks for letting me regurgitate a decade plus of studying recurring revenue, pricing, and billing. At least here it's useful. At the dinner table I get no likes for these knowledge drops. :)
Happy to answer any questions.
I've seen a few threads recently about the power law in venture capital and what this means for individual company returns. We looked at our data on 11,350 companies backed by 259 funds from 1986 to 2018. /1
Acts of @Cloudflare: Pleased to share my deep dive exploring their evolution & challenges in becoming an enterprise platform
My goal was to figure out why Cloudflare trades as one of the most expensive SaaS cos.
If you only have 5mins, here's the bull v bear on $NET's next act:
An infinite number of mathematicians walk into a bar.
The 1st orders a beer. The 2nd orders half of a beer.
The 3rd orders a quarter of a beer.
The 4th begins to order, but the bartender cuts him off saying, "You guys need to know your limits."
He puts 2 beers on the bar.
This question comes up a lot, here’s my take.
High growth software companies today are trading at ~10x forward revenue overall median closer to 7x.
Many growth stage companies raised huge rounds in 2020/2021. Their balance sheet is loaded with 3-5+ years of runway. And even after a few years, they’re still sitting at a 20-50x revenue multiple (at last round valuation) as growth has slowed
If you assume a 7-10x multiple at exit (which many companies won’t get!), it’s hard to make the math work when investing at the growth stage at 20-50x revenue. So even a flat round is still quite expensive.
And given many of these growth stage companies still have 3-5+ years of runway they have no reason to do a down or flat round. They can wait. So there’s no price discovery.
For companies without this excessive runway (weren’t lucky enough to raise a Covid round), there’s still a mismatch in expectations vs what investors are willing to pay given the period we just came out of.
In summary - a flat round for many growth stage companies would imply paying 20-50x forward rev at last round valuations. Hard to make math work with a 7-10x exit multiple when growth stage co’s have less time to grow into their valuation. And for many companies there’s no incentive to go to market as they are flush with cash / runway. So it remains a “dead” market. Most activity I see at growth stage is either structure or secondaries
Quick math: for growth investing let’s assume a 5 year period to liquidity, 20% dilution post investment, investing at 50x, exiting at 10x, and 4x gross return target (~3x net). To hit that target return, the company would have to CAGR revue at ~90% / year! That’s an extraordinary hurdle very few will hit, and only for a 3x net return! At a 40x entry multiple the rev CAGR required is 81%. At 30x it's 70%. At 20x it's 57%. Not great risk adjusted valuations... math below:
Songs in Bollywood movies inspired from elsewhere aren’t something unheard of. But a song created from three different songs almost 50 years ago that continues to charm us even today is quite a feat. A thread. 1/10
2023 tech reality check:
1. Nobody owes you $2 million for having an idea.
2. DCFs are easy when interest rates are 0.
3. Value creation does not mean value capture.
4. Stock based compensation is still compensation; dilution isn't free.
5. Margins matter.