@perksverse The potential safeguards Schmidt envisioned in 2024 are nowhere to be found. Perhaps OpenAI & Anthropic are indeed cynically hoping for regulatory capture, but that doesn’t mean that the dangers they are finally screaming about are imaginary.
@perksverse This interview is from May 2024, and the OpenAI / Hugging Face incident shows that his 5 year prediction is 2x too slow; it is largely here. (Context is not infinite, but his point was that it will be enormous, and it is.) 1/2
https://t.co/mine0R9JZB
@james_raftery@JamieGriff97 Yes GAAP. Even GAAP is pretty lenient on a lot of stuff, but non-GAAP is often hilariously misleading. My favorites are “extraordinary losses” that are recognized in GAAP accounting but excluded for non-GAAP. These extraordinary losses are AKA “losses.”
@blenheimassocs@hussmanjp Sure; note that my post started with “Lately part …” Note also that some of the reported growth and much of the forecast growth is based on major vendor financing, e.g. where a loss-making company gets funds (in some form) from vendors to buy their AI HW and/or services.
@blenheimassocs@hussmanjp HW unit volume has not grown much; the rev/earnings growth owes primarily to shortage-driven price increases. Thus it would be a zero-sum effect on market-wide earnings if HW were expensed immediately rather than capitalized. Depreciation will drive mean reversion.
@blenheimassocs@hussmanjp Lately part of the margin expansion magic is that windfall profits on HW in shortage sold to hyperscalers is recognized immediately, whereas the hyperscalers capitalize the HW cost and will report that cost on P&L only on a lengthy depreciation schedule.
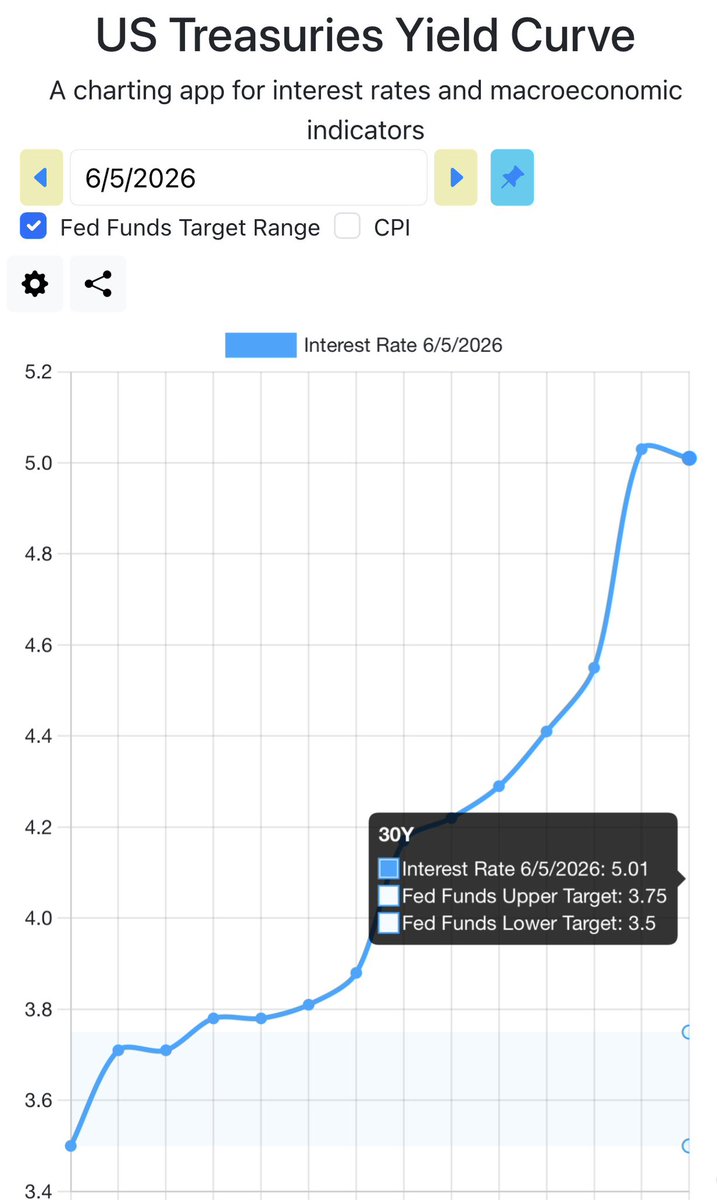
@InfraVaultHQ@elerianm 1. What inverted yield curve? 2. If it were inverted, it would encourage long term borrowing. 3. The only way real long Treasury rates are going down is if the Fed buys it, I.e. monetizes the debt on our way to Zimbabwe.
@Syedyousef16@zerohedge Stagflation has been baked in the cake for years. It’s also been happening for years, but underreporting (lying about) inflation has the “happy” side effect of making reported “real” GDP growth higher.
@dampedspring Seemed like Paulson was arguing for making the Fed put official policy in an attempt to avoid actual big print scenarios. Logical extension of the Fed’s/Treasury’s 1D chess moves.
The dual mandate has been a disaster for the US. I’m not sure what the RoW’s CBs’ excuse is.