Also borrowing this screenshot from @_Sgr_A_Star, and adding some color from last week's $IREN IR notes:
*Hyperscalers are now much more willing to prepay a significant percentage of the TCV compared to last year (e.g. $MSFT at 20%).*
Sweetwater 1 has 200MW IT under construction, 150~170MW of VR200s on order, and 9-12 months until the first data hall is commissioned.
The iron is hot, time for @IREN_Ltd to lock in an anchor tenant, ahead of the inevitable GPU debt for this deployment.
No matter what you read from the shady desks such as SemiAnalysis/Citrini et al, nothing will change the fact that $IREN has secured its H2 CY27 VR200 allocation, and with secure, permitted power, and a blazing fast construction process underway, Iren will land an impressive IG deal, including funding, and the market will change its mind overnight.
Did you all really forget that 2027 power is ULTRA scarce? Let alone 2027 LPS?
I'll be there, with more shares thanks to the discount of an uninformed market.
Long $IREN
$NVDA to continue to support neoclouds in a disciplined way. (Kress)
That bodes well for the establishment $CRWV $NBIS $IREN
May be less ideal for smaller upstarts. But my read is the big partners will continue to see dollars and backstops that are critical to NVIDIA.
Hey @grok $NVDA today kept talking about owning the land, power, and shell as the prime business model for neo clouds.
Which one of $IREN, $NBIS, $CRWV has been doing that strategy of being vertical the whole time?
Which company recently announced they are going to own the full stack from on now proving that one company has a superior business model and more visibility into the future?
And which company is likely too levered up to own the full stack from taking out so much debt already?
@Herukos_@ZeekTyt Why would they not rent the capacity long term? Nothing has even happened yet, we are so early in the AI boom man. I don't understand your reasoning here.
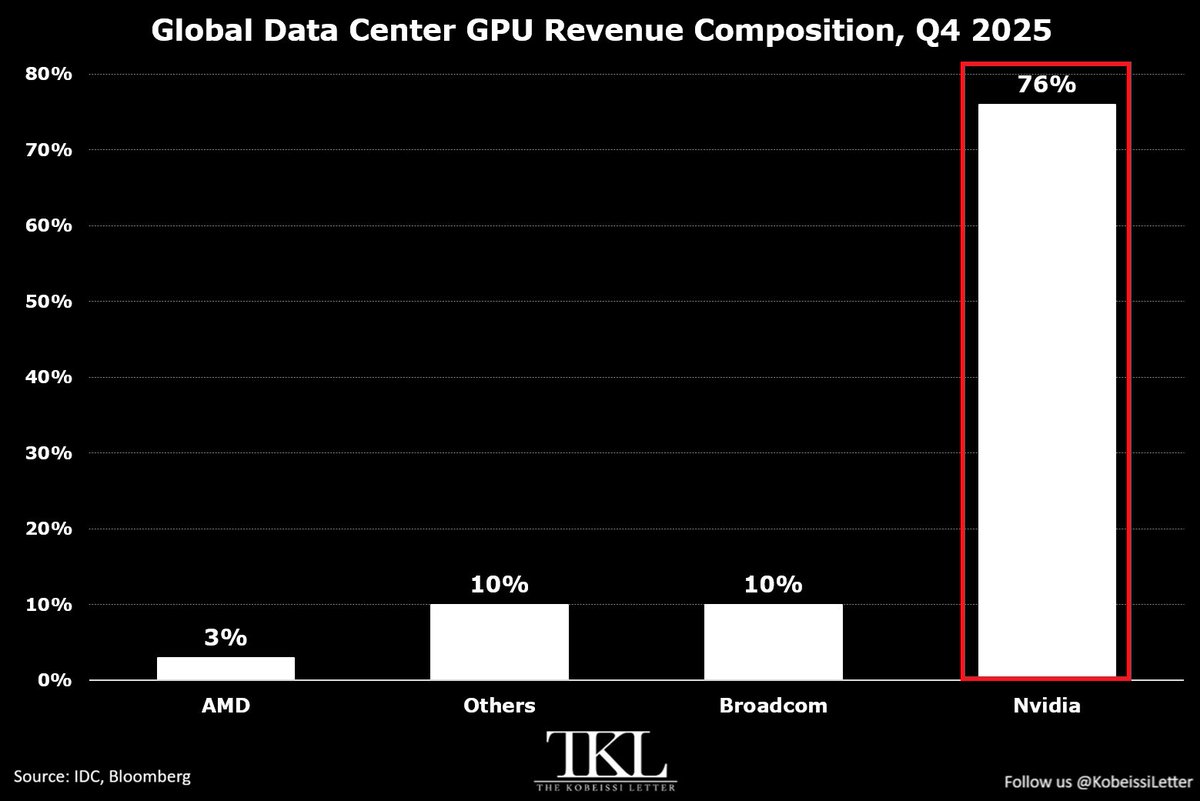
Nvidia's dominance in the global data center chip market is unprecedented:
Nvidia accounted for 76% of global server GPU revenue in Q4 2025.
This is more than 3 times the combined revenue of all its competitors.
Broadcom, $AVGO, came next, accounting for 10% of the market.
By comparison, AMD, $AMD, represented just 3% of total revenue.
This comes as Nvidia has spent years investing in GPU applications beyond gaming, long before the AI boom.
Nvidia is firmly in control of the AI chip market.
This was the overhang, from what I've seen.
We see the pipeline, we know the demand, and the question was how they'll build it...Now we know:
1. Prepayments
2. NVIDIA backstopped deals
3. Finance the data centers when built
When Nvidia says that Iren will be it's Flagship DSX Data Center, how do people not see how bright their future is?
When Iren and Nvidia announced a strategic partnership to deploy up to 5 GW of NVIDIA DSX-aligned AI infrastructure across IREN’s global portfolio, how do people not see it?
Finally, at GTC Berlin in October 2026, NVIDIA highlighted IREN alongside its new DSX Pod announcement. The factory-built, containerized data center modules house seven Vera Rubin NVL72 racks and cut on-site installation times down to roughly 14 days...Iren has the land, power and capacity to build out Sweetwater to plug and play these babies...
$NVDA HIGHLIGHTED THE IMPORTANCE OF OWNING THE LAND, POWER, AND SHELL
Only $IREN owns all of that right now
This leads to them having higher margins long term than $CRWV and $NBIS
Here are my projections:
The Neoclouds aren’t a nice to have for $NVDA. It’s the biggest sustained bet it has on creating an ecosystem of NVIDIA powered hyperscalers that won’t look to build competitive or meaningfully augment with custom silicon.
The investment is critical to its continued growth. It’s not optional for NVIDIA. It needs a new breed of AI hyperscalers to grow along with it.