Just a friendly reminder, the rule of thumb for bioturd investing, if your favorite bioturd tanks and you are 100% convinced it must be the bottom, there is another ~25% drop to go. $xbi
$PLRX from $1.1 to $0.66 within 2 months on no news.
- Cash $142M (runway to mid 2028) vs $41M market cap
- Well-enrolling ph1b in oncology, 100+ patients in 3 cohorts (NCSLC, RCC, TMB-H in secondary refractory CPI setting with readout mid-2027. With decent early PoC data and a good biomarker at 2w to predict response.
- Interesting cardiac/muscle integrin-based delivery platform
Early-stage biotech being beaten down every day to new lows
$LEGN This offering at $29 was pretty smart after all
Seems cheap down here.
Loads of cash.
Growing sales.
Competition overestimated (both bispecifics and anitocel)
Readout in 2027 in 1st-line setting
In vivo CAR-T pipeline (+ more)
$MIST ok sales not great. risky one. But trading at deeply negative EV and new runway through AF readout.
Why is it being punished so hard last couple of days? What is the negative news?
$KPRX overpunished. I get it. From a runway to late 2028 to going conern for funding a ph3 asset acquisition. However this acquisition has been pre-orchestrated with good biotrch expert funds involvement.
Warrants that were supposed to fund the deal are very out of yhe money now. But I believe the outcome will be good (very speculative of course)
$HELP now similar placebo-adjusted to $DFTX (vs better on prior data). But different study populations and design (adjuntive vs monotherapy) so difficult to compare
$HELP What is causing the dip? "There were three HLP003 treatment-related serious adverse events in the study" maybe this? Or the drop in efficacy compared to prior data?
Why would I spend brain cells on a stock I have no position. It was just a casual post asking for others' opinion.
Point of BioX to me is to share ideas and experience.
Why look for a confidence booster in comments from people you consider silly? Just focus on your own performance.
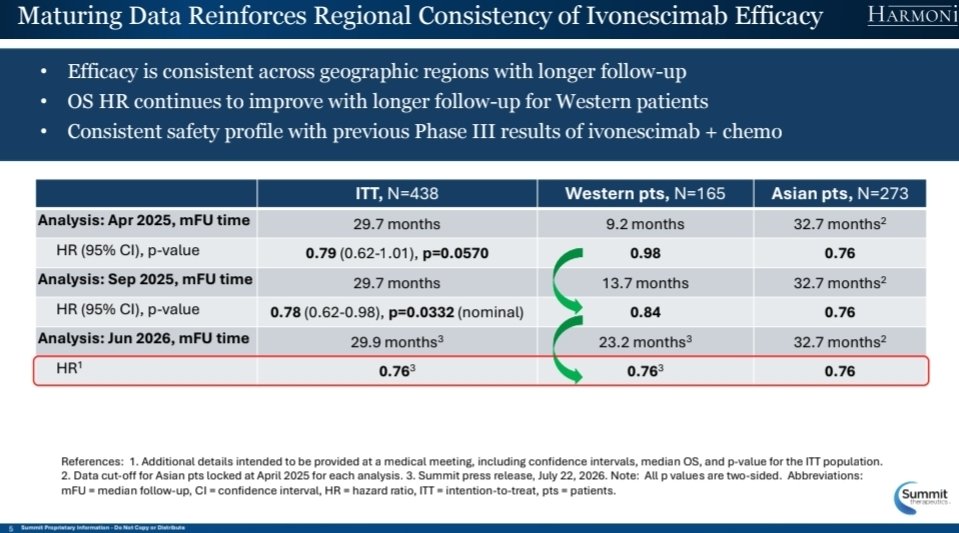
$SMMT CRL shocker: "substantial evidence of effectiveness is not established" in the absence of OS benefit. "PFS benefit in the absence of a statistically significant OS benefit does not support a positive benefit-risk profile."
I struggle to understand the FDA’s decision on ivonescimab in light of its previous decisions. Without those precedents, I could understand a rejection based on failure to meet a primary OS endpoint.
In TROPION-Breast01, PFS and OS were dual primary endpoints. Despite a positive PFS result and failure to meet the final OS endpoint, Dato-DXd received regular approval.
Dato-DXd also received accelerated approval in EGFR-mutated lung cancer after prior EGFR-directed therapy and platinum-based chemotherapy, based on response rate and duration of response. TROPION-Lung01, one of the studies contributing to that approval, also failed to meet its primary OS endpoint in the overall population.
Of course, each regimen has a different benefit–risk profile and approval pathway. Still, I look forward to a clear scientific explanation of why a statistically significant OS benefit is indispensable for ivonescimab and what distinguishes this case from these precedents.
@AppleHelix The 1st line is the big TAM.
The CRL is for a (relatively) small TAM. The problem is that this CRL means years delay in commercialization (would be much easier if they had it approved and commercialized by the time they get approved in 1st line)
$SMMT I am as surprised as you are looking at the data. My understanding is they stopped the trial too early (at least with regards to the Western cohort). OS barely missed (upper end of 95%CI 1.01) mostly due to not long enough follow up in Western cohort. On longer follow up it seems clear to me efficacy in Western cohort matches that of Asia cohort (even if NS due to smaller n).
They spent their alpha at primary analysis and FDA did not accept subsequent data.
At least that is my understanding. I would appreciate a better explanation
@RayneWothbaum Lol. You are exaggerating. I do say that but definitely not "every other post".
Why are you following/commenting school level posts btw?? I would mute me if I were you
@molecule_trader Undervalued based on just THI even if CHI doesnt work out.
I see CHI as a free call option at current valuation (and I think they will get approved for both)
Offering may seem disapointing but led by top tier biotech experts