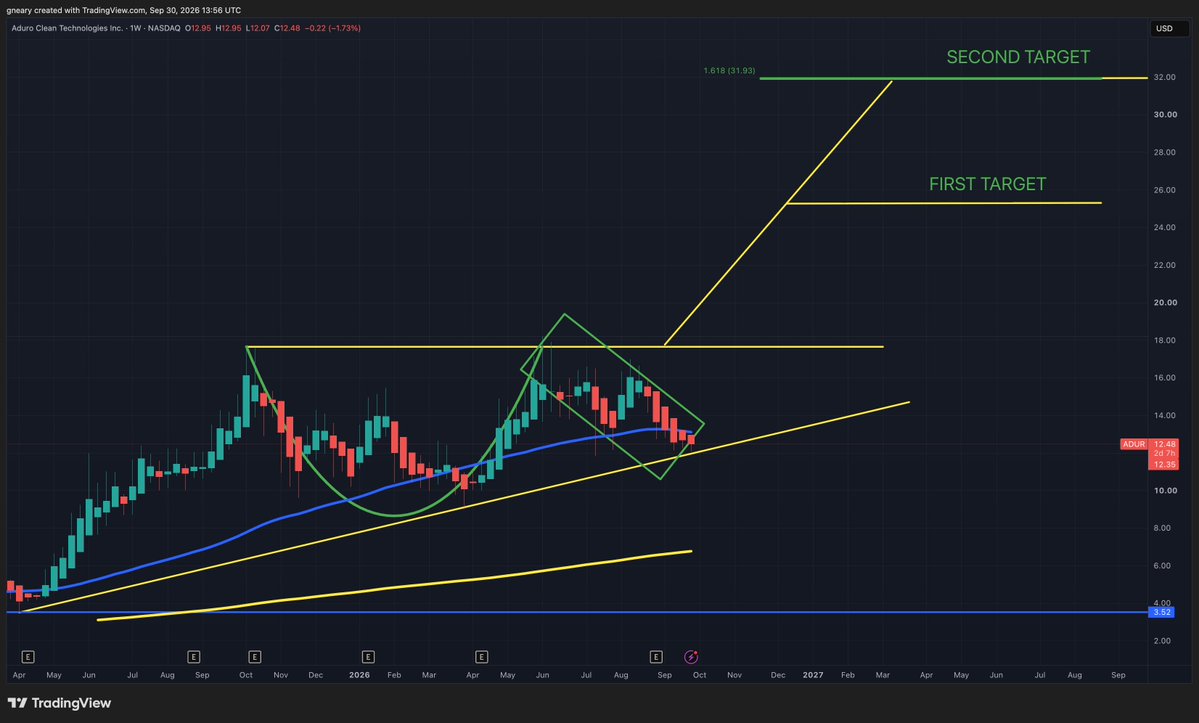
$ADUR when I see this chart, all I see is the $OSCR chart when it was at $12 before it ran +190%
What's even more bizarre is that $ADUR is at $12 now too.
Same upside trajectory
In a bullish ascending triangle while being in a bullish cup and handle.
And price target is EXACTLY where $OSCR is this week.
Wild.
If you’ve followed $ADUR for a while, you know Ofer is very intentional with his words.
During last week’s WTR interview, he specifically brought up the Venezuelan heavy crude topic while discussing the heavy-oil vertical.
Probably nothing.
$ADUR I will hold forever.
- They have invented a product that helps save the earth
- Their Moat can not be replicated
- Management team that works night and day.
Very lucky to have this opportunity.
A few months ago, I said $ADUR could eventually address a $1T market. I have even less doubts now.
I know this sounds absurd if you still see Aduro as simply a plastic recycling company.
- Plastic recycling alone represents an estimated $121B opportunity, while Aduro currently presents a combined addressable market above $250B across plastics, heavy oil and renewable oils.
- My $1T thesis has never been based on plastics alone. It comes from viewing $ADUR as a chemistry and intellectual property platform.
Ofer’s latest interview with @The_PennyQueen made this even more clear.
- Ofer said Aduro is developing technologies beyond HCT and expects the company to generate one or two new patents per year over the next few years. Some of that intellectual property could cover entirely new technologies.
- $ADUR is becoming the key player in manipulating hydrocarbons. Aduro's real breakthrough is a way to cut those chains precisely and predictably, in water, with a catalyst. Because the tool works on the chains themselves, the same core tech can be pointed at almost any hydrocarbon feedstock. And the world is full of hydrocarbons.
If Aduro keeps turning its research into protected technologies for other large industrial markets, its addressable opportunity could grow far beyond today's $250B+ estimate.
@DoleNotDeadYet@dmeinvestor Your comment won’t age well. I guarantee it. I’ll send you a screenshot of it in 6 months to remind you of how wrong you were. So tired of fools like you.
$ADUR
The company’s story will unfold much more quickly than people think.
Connect the dots and if you haven’t started your DD, I strongly recommend that you do ASAP.
First, let me count my blessings. I was invited to an investor presentation with fund managers and investors to meet with $ADUR management this week in Europe. This was Aduro's first time presenting to what I consider front-of-the-line Money Managers in Europe, and after both presentations, I came out with the highest level of conviction I have had in a while. You see, when you are sitting on large paper gains, the temptation to cash out is always there, so I have to say, outside of trading around my core position. I came out more interested in expanding my core position.
Now back to the presentation and my key observations for now, which I may add to once I get to Dubai:
1. Everything shared there is publicly available, but when you sit through an hour-and-a-half session and hear the founder and CEO speak, plus the questions that get asked, you realize how rare @AduroCleanTech is. Aduro also made it clear that they are not here to raise capital; they have what they need till closer to the end of the FOAK (my assessment: closer to Q3/4-27)
2. Two fund managers, after realizing how huge the opportunity is, asked management bluntly, " Why are you public. This company should have been a VC-backed company that would go public later in 2028/2029, post the FOAK, and I quote, "5 to 10bn Euros". The answer was equally impressive; Ofer said that when he and Marcus decided to finally go public (after they were poached for a buyout in 2020), it was to preserve their independence and allow Aduro to sprout its multi-vertical platform without being under the gun by a VC or a strategic investor that might have wanted shortcuts or shift the company's focus towards fast-tracking the process. To him, the key learnings from failed multi-billion-dollar pyrolysis companies were the same: he didn't want to skip steps, and he wanted the IP protected, and he wanted to commercialize the technology right.
3. Regarding strategic money and investments, Ofer made it clear that there were attempts by industry players to invest earlier; however, the main pushback was that Aduro did not want to give exclusivity, "being hugged by one company" too early. He believes they are closer than ever to commercial scale in two verticals, each of which could easily be worth multi-billion dollars, so giving exclusivity early could jeopardize the opportunity in the same way outlined in point 2.
3. Ofre's vision is for Aduro to be a worldwide Energy and Sustainability household, and he views that whilst the plastic and paraffinic oil verticals will be the first to go to market, the company is and continues to be focused on expanding its IP to new verticals.
4. The company's HCT platform is now being followed by all the major players in the Energy sector. Ofer made it clear that they don't see any other chemical recycling technologies as competitors, and he said Aduro is in a league of its own.
5. Their IP is iron-clad, with 7 patents issued and 4 pending, and many more in the works, and Mena made it clear that, based on what they know today, their IP is worth way more than the current market cap.
6. Ofer does not believe in shortcuts; the company, relative to the Energy space, is going at rocket speed, but they will not, for the sake of short-term gratification, rush the process. The first recycling commercial unit is set for 2028. However, the paraffinic oil vertical felt like it could be the first to go to market, at least to me.
7. They set up their commercial plan with regard to the plastic vertical that would benefit significantly from the European regulations, which want to protect their chemical industry. Europe is pushing back against imports of cheap products from the Far East, and to protect the industry, it has new mandates that disallow the use of such feedstock without applying a penalty for non-recycled material (a penalty of 160+ Euros per ton). These regulations will tighten by 2030, with demands for recycled materials to reach 30%+ of plastics. Europe produces over 11M tons of waste plastic a year, and that keeps growing.
8. The Parrafinic Oil sets Aduro miles away from anyone else. This vertical can add $ 11 to $25 in value to each barrel produced at the Unita Basin, when energy players are scrambling for cents/barrel. The vision is to get to a place where just the Utah Basin could go from 185k barrels a day to over 1M (clearly will take years to get there), but I suggest you pause here and get your calculator out as I did, and you will realize what Aduro is sitting on with just this vertical alone
9. The world is moving towards energy independence, meaning this is not a Utah matter. Aduro views the same opportunity in Alberta's heavy oil, Venezuela, etc and these are massive opportunities in front of the company, again, in my view, each of which can be a company maker on its own.
10. I spoke with a few of the money managers post both meetings and was positively surprised by how many are keen for follow-ups and for potentially putting the name in front of their investor base. They realize that once this company is known and the FOAK, or the first Parrafinic, moves closer to commercial scale, the window of getting a meaningful alpha may lapse by then
My personal view is that if I take a step back and look at $ADUR today as an investment, it is a very compelling/rare one if I am sitting my watch for the next 24-36 months instead of looking in the rearview mirror at when I got lucky in 2021 to find this company.
As always, these are my personal views; do your own diligence. This is not financial advice
@CFrechette I guess panic has set in for you and your party. You will LOSE the upcoming elections based mainly on the horrible record of the past few years. Goodbye.
$ADUR talking with and posting a picture of them together with PepsiCo's Senior Manager of Circular Economy Packaging & Recycling for Latin America.
It's probably nothing, just keep ignoring this and move along.
$ADUR seems like my @AduroCleanTech alerts are buzzing with great developments. I have been in this name for five years, and I am up big, but IMO, the de-risking over the past 12 months makes the company's current valuation quite compelling, and I might just start adding at some point
$ADUR CRO Eric Appelman has a packed few weeks:
- Yesterday, Eric presented HCT at the $PEP Sustainability Innovation Hub in Mexico City, focused on flexible and multilayer packaging.
- On September 30, he'll discuss $ADUR path from pilot validation to industrial deployment at Chemical Recycling Europe in Brussels.
- On October 8, he'll present $ADUR paraffinic crude technology at IRPC in Houston, in front of major oil and petrochemical companies.
Worth remembering that Eric was already retired before deciding to return to work after seeing what $ADUR was developing.
Probably nothing. He was just bored, I guess...