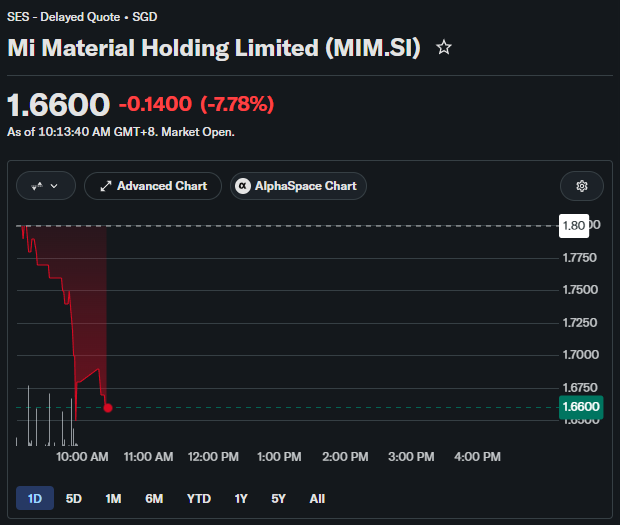
hope folks who got shares at IPO sold some at the IPO price to the stabilization bank for exit liquidity over the preceding two trading sessions
let's not forget that 8,980,524 shares were also distributed to eligible shareholders of the parentco (Mi Technovation) - which may add to the selling pressure
$MIM.SI
UltraGreen AI ($ulg.si) Pulls Guide
- UltaGreen the Singapore-based maker of indocyanine green, a fluorescence imaging agent (used for gallbladder, colorectal, breast sentinel lymph node and breast reconstruction surgery). Was a marquee SGX IPO at the end of 2025
- Stock was down 15% after earnings (and now down 67% since IPO)
- Q3 Earnings: Despite growing revenues 35% the company pulled the guide of US$175-185MM of 2026 rev saying they will come under that now.
- Mgmnt is blaming competition from new entrants putting pressure on pricing
The stock now trades at just 6x fwd earnings, but investors are questioning the moat.
Executives in Indonesia's state-owned bank Bank Rakyat Indonesia (BBRI IJ) bought the dip: senior officer Alexander Y S bought US$164,000 worth of shares close to the bottom. Even today, the stock trades at just 7.2x trailing P/E and a 11% dividend yield. Source: Smart Insider
Mi Material's IPO starts trading at 2PM SGT today
Retail reception towards the offering seems lukewarm at 1.3x cover (and looks like some of the EQDP funds had to step up)
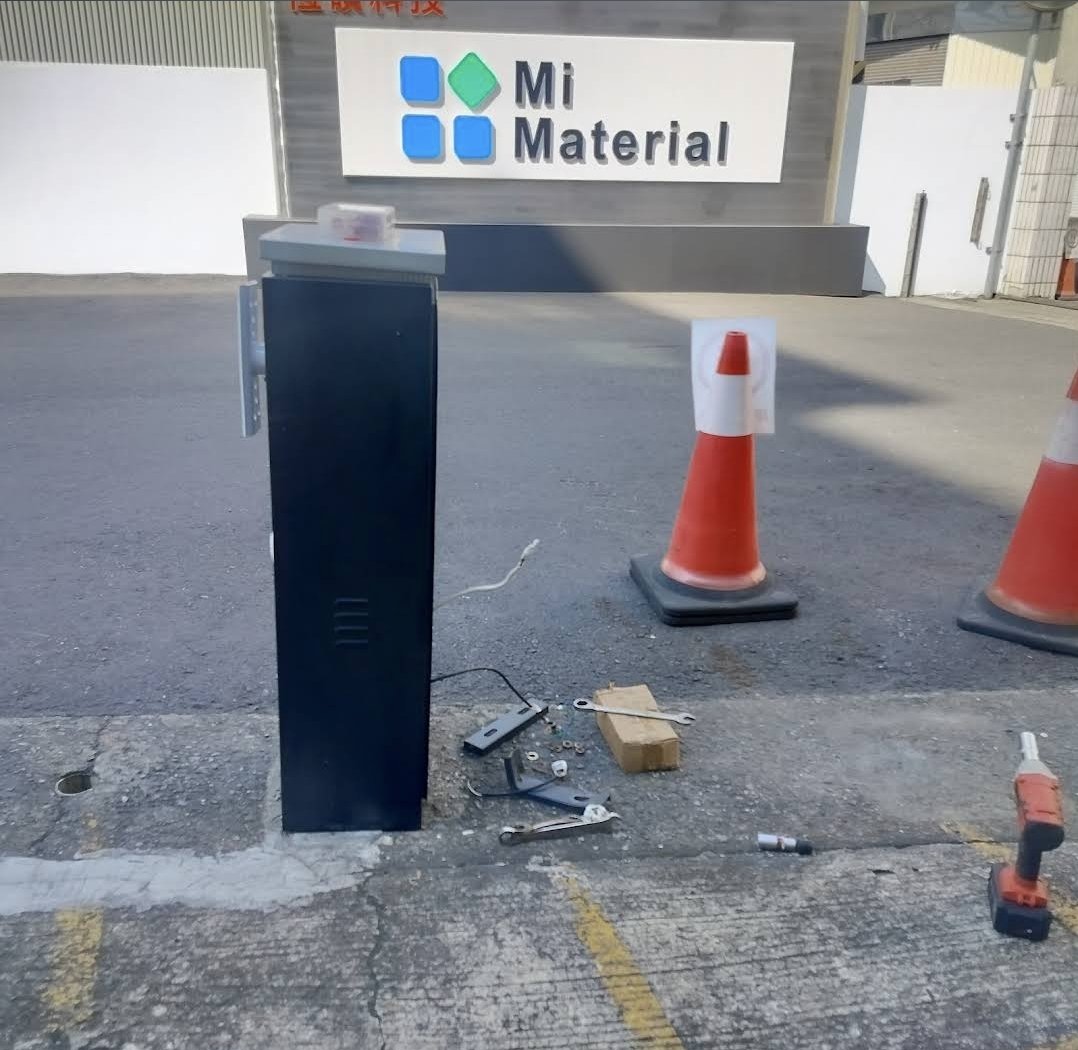
Let's see if first day trading is as broken as the gantry system at their Tainan factory lol
Mi Materials lists today on SGX ($5286.KL)
Mi Materials is begin spun of MiTB a Malaysian semiconductor materials maker.
Mi Materials focuses on solder spheres - microscopic balls of specialised metal alloys that create the electrical connections between a semiconductor chip package and the PCB underneath. Think of them as the microscopic “wiring dots” under modern chips. Without them, the chip can’t talk to the rest of the device. Mi Materials has about a 24% market share. They sell through OSATs and foundries. Largest end customers likely Apple (24% of rev), Broadcom (18%), and Micron (16%).
1H26 rev was up 109% to US$53.65MM and Profit up 396% to US$14.28MM. IPO priced at S$1.80/share which gives Mi Materials a market cap of S$891MM and EV around S$890MM.
Should be a good day to list given AI trade ripping. SGX needs a win. Trading starts at 2pm. Watch this space
We published an open letter to Orion Corp (271560 KS) earlier this week. Please find it here: https://t.co/B8Mk9EZtIr
- Orion Corp is a leading $3.3B market cap Korean confectionery business that earns a majority of its sales outside of Korea in high-growth markets like Vietnam, China, India, and Russia.
- The Company has iconic brands, is highly profitable, has great return on invested capital, and generates great cash flow.
- But, Orion has allocated cash away from its core business over time and recent market news about Orion considering an acquisition of JoongAng Ilbo, a newspaper, has brought these corporate governance back into the spotlight.
- We believe that Orion is not reaching its full potential because of these concerns and the market is rendering this verdict at ~5x p/e ex-cash and other financial assets.
- We believe that improved shareholder returns in the form of dividends and buybacks, as well as clear capital allocation framework, would assuage these fears and make for a better Orion.
@RyanReeves_ this isnt so unusual for founder operated cos.. grab.. meta.. etc.. all have this in one form another.. one guy at the top .. calls the shots.. for better or worse.. till death do us part
Mi Materials lists today on SGX ($5286.KL)
Mi Materials is begin spun of MiTB a Malaysian semiconductor materials maker.
Mi Materials focuses on solder spheres - microscopic balls of specialised metal alloys that create the electrical connections between a semiconductor chip package and the PCB underneath. Think of them as the microscopic “wiring dots” under modern chips. Without them, the chip can’t talk to the rest of the device. Mi Materials has about a 24% market share. They sell through OSATs and foundries. Largest end customers likely Apple (24% of rev), Broadcom (18%), and Micron (16%).
1H26 rev was up 109% to US$53.65MM and Profit up 396% to US$14.28MM. IPO priced at S$1.80/share which gives Mi Materials a market cap of S$891MM and EV around S$890MM.
Should be a good day to list given AI trade ripping. SGX needs a win. Trading starts at 2pm. Watch this space
@SteadyCompound btw u can also pay for a package with cursor (which is 50% discouned for next 6 motnsh) that gives you grokbot premium, x premium, and cursor for S$28/month
iFAST ($AIY.SI) AUM growth coming in at just 1.7% qoq and 20% yoy . Much below their required run rate to hit their $100bn target by 2030.
https://t.co/3OvRPiF0Yk
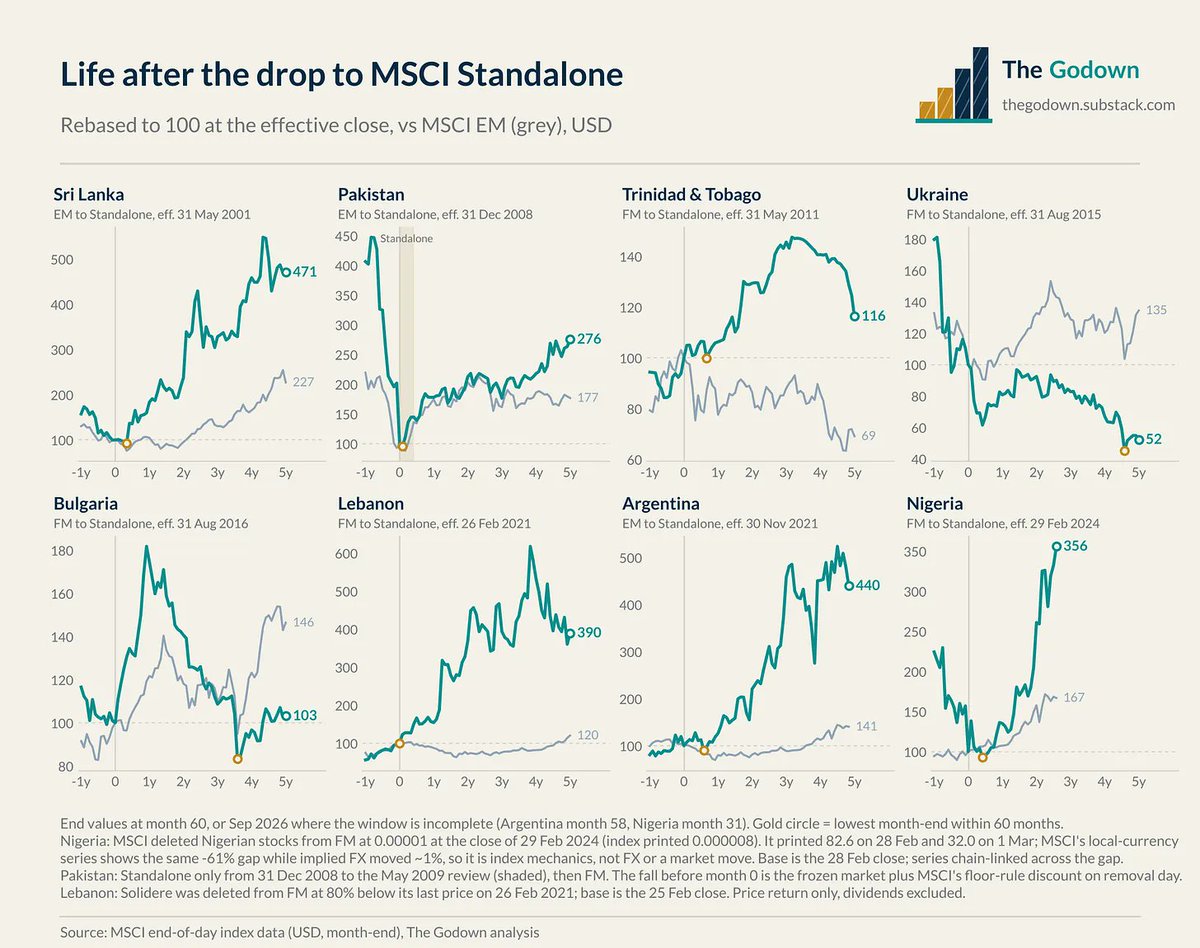
MSCI may dump Indonesia to “Standalone.” History says that’s not always a graveyard.
Markets cut before, rebased to 100 on the effective date vs MSCI EM (USD):
Sri Lanka 471 vs 227. Argentina 440 vs 141. Nigeria 356 vs 167. Pakistan 276 vs 177.
(Ukraine was the ugly exception.)
Every Standalone case side by side: after ~5 years, most beat the panic story (sample is messy).
None of these cover the threat window, that’s when forced sellers hit. Decision: 30 June 2027.
Full piece:
https://t.co/jpWtcHbrYb
Not investment advice. do your own work.
Pain doesn’t end on day one. Most indices fell further after the effective date.
The ones that bounced found their low ~1–8 months later, then ripped.
Sri Lanka: −8% to the low, then +410% over 5Y from that trough.
Argentina: −10% to the low, then +410% over 3Y.