$SIVE WOW:
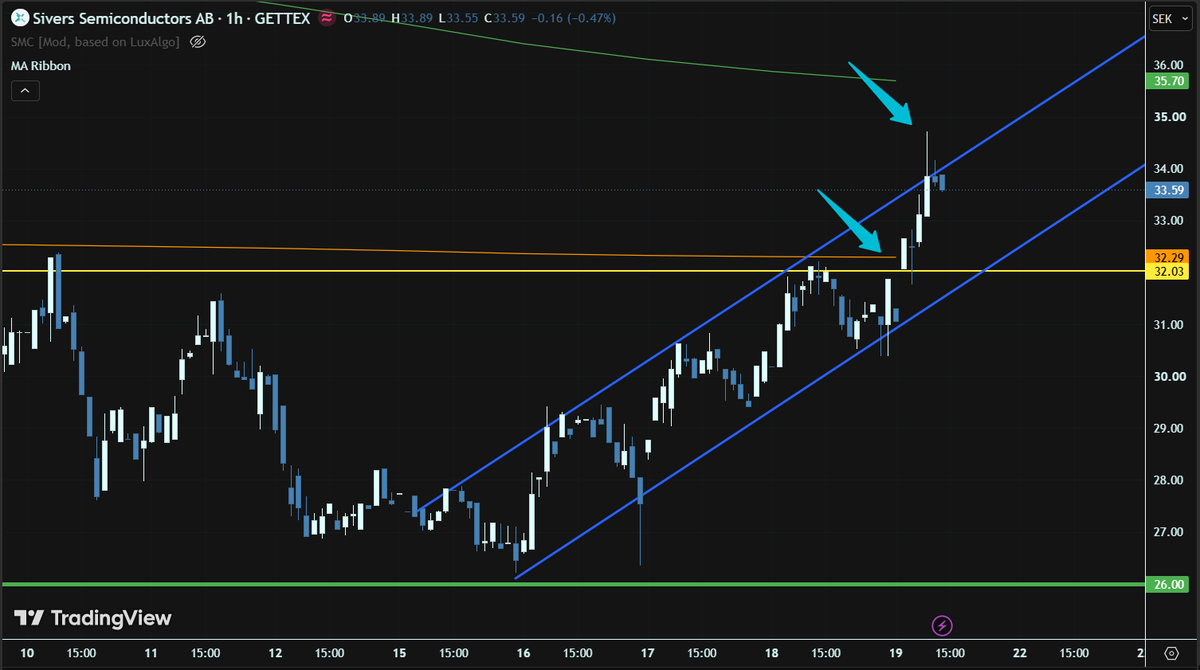
Broke through the 200 EMA and a major resistance flawlessly
It then attempted to breakout the ascending channel, propelled by clearing a major resistance, but rejected at the upper trend
The bullish ascending channel is hold pretty strong so far, surprisingly ngl
Just floating out an idea to $AVGO:
If you lock up $SIVE laser supply for next few years since you need “more laser capacity”.
You could unintentionally cause bottlenecks across your main ASIC competitors:
Like $MRVL (Celestial), AlChip, Mediatek, GUC (Ayar CPO), first gen deployments.
Where many also seem to be aligned with your best friend $NVDA…
Maybe it’s worth discussing spending spare change to lock up the remaining merchant laser supply?
Idk if I already mentioned this post but just gonna remind everyone that I still think some sort of partnership in China for $SIVE seems like the next announcement.
CIOE 2026 + The CEO's trip 7 months ago with the sales team of $SIVE + announcement of 6 meaningful engagments with pluggable partners + new foundry partner with "tremendous capacity" availabe NOW.
i'll prolly post some some fun predictions on who these could be especially because I have a hunch that at least a part could be in China.
Also in hindsight why did everyone freak out about the earnings call bro it was literally: announcement of 6 meaningful engagments with pluggable partners + new foundry partner with "tremendous capacity" availabe NOW. + Shifting away from NRE + Opportunity pipeline growth. That shit was bullish
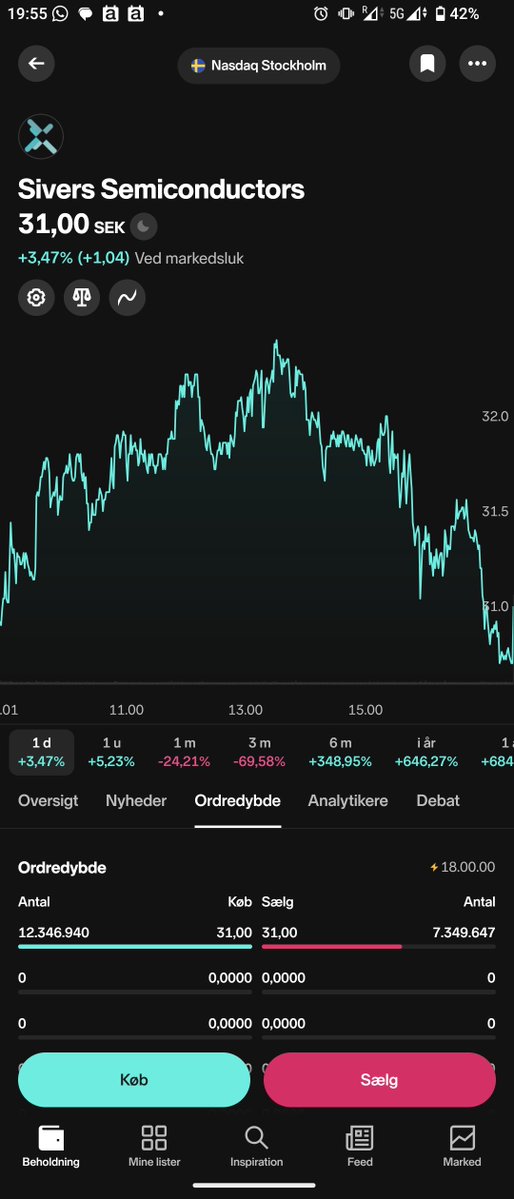
$Sive closing market was one of the craziest ones. They tried to dump 3.5 million shares, which was followed by backfiring 12 million on the buy side within a minute,!!!
Who did this ???
What just happened, or is about to happen???
$SIVE the $GFS × $MRVL capacity expansion strengthens one of the most compelling parts of the @SiversSemicond investment case.
@GlobalFoundries and @MarvellTech are committing manufacturing capacity to the components supporting next-generation pluggables, near-packaged optics and co-packaged optics.
Multi-year capacity agreements show how seriously the industry is preparing for growing optical demand.
$SIVE has a relevant connection here: its laser arrays are planned for integration into reference designs on $GFS silicon photonics platform, supporting the broader SCALE optical-engine ecosystem.
The technical distinction matters. The $MRVL agreement expands SiGe capacity for electronic components used in optical connectivity. Sivers supplies the laser technology that provides light for silicon-photonics systems.
My bullish read is that expanding the electronics side of this supply chain reinforces the opportunity for complementary laser suppliers.
$SIVE participation in GF reference designs could make its technology easier for customers to evaluate and adopt as optical deployments grow.
This announcement does not establish a $MRVL supply contract for $SIVE.
Revenue still depends on customer selection, qualification and production orders.
But it strengthens the commercial context: major companies are committing capacity to the same optical architectures $SIVE is developing products for.
$SIVE
Sivers managed to break the downward trend.
What ewe need to it be sustainable is a break of 32.5SEK and an increase in buy volume.
That would start wave 3 of the short-term trend .
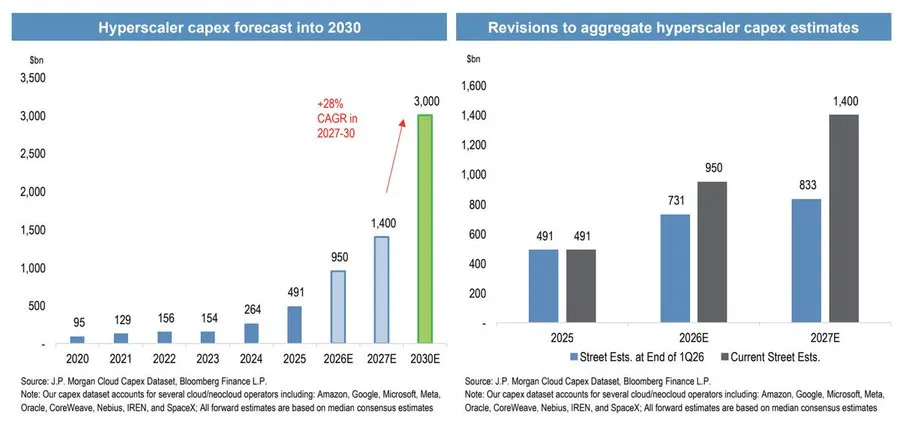
J.P. Morgan's cloud capex dataset just laid out where the money behind $SIVE and $AAOI is actually headed, and the shape of the curve is the whole story.
Hyperscaler capex went from $95 billion in 2020 to $491 billion in 2025. The forecast has it at $950 billion in 2026, $1.4 trillion in 2027, and $3 trillion by 2030, a 28% compound annual growth rate for 2027 through 2030 alone. This dataset covers Amazon, Google, Microsoft, Meta, Oracle, CoreWeave, Nebius, IREN, and SpaceX.
Every dollar of that spend eventually has to move data between racks, and that's the layer $SIVE and $AAOI both sit in. You don't need either company to capture a large share of that number for the current growth rates to keep holding up.
$SIVE
In my last $SIVE post the price was at 44SEK while I was predicting a pullback below 30SEK.
There we go.
What is missing at this point is a break of the downtrend and an increased buy volume. Once we see both the end of this correction is close.
The latest low marked the end of wave c which is fulfill the requirements for a possible end of wave 2.
Long term wave 3 target is 180SEK.
$SIVE Another reason to pay attention to its wireless business.
$NOK and $NVDA are advancing AI-RAN, with @nokia reporting more than 20% spectral efficiency gains and a roadmap toward AI-native 6G.
$SIVE already offers Daybreak beamforming chips targeting the emerging 7–15 GHz FR3 band for 5G/6G base stations and customer equipment.
No confirmed @SiversSemicond involvement in these specific deployments yet.
But as operators progress toward new radio hardware and higher-frequency networks, the potential opportunity becomes increasingly relevant.
The photonics story gets most of the attention.
I think the wireless business deserves a closer look too.
$SIVE has its own piece in Digitimes btw, which is appreciated industry recognition outside of Sweden.
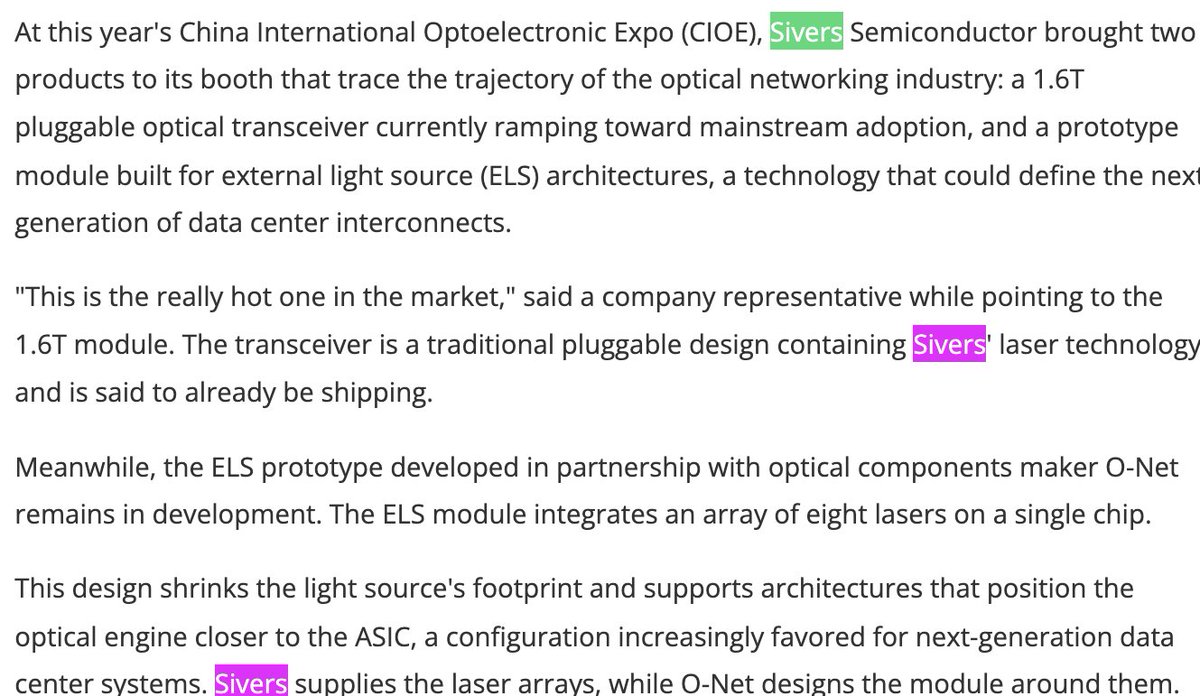
I think Sivers 100M+ CW DFB laser capacity buildout forced the industry to revisit its models and generated considerably more coverage.
BC it puts Sivers into T1 laser capacity convo w/ $COHR, Sumitomo, Furukawa, $AVGO, Landmark, and $LITE if it executes on its ramp.
But outside of that, CIOE 2026 channel checks were really meaningful since the community found Sivers is working with Chinese pluggable players + setting up an office locally.
I'm getting dejavu to the time I pointed out $SIVE + $JBL at OFC for their 1.6T LRO, but nobody believed the link until there was an actual press release.
Anyway, proud to see this little company growing up
Holy sh*t we are going to moon on Monday
Anthropic is tripling compute deals
OpenAI just stopped offering their $200 plan due to a lack of compute
There is so much demand for more GW. Stay bullish on everything
You aren't ready for this to become official
It seems increasingly realistic that $SIVE will announce a Chinese customer or partner
They traveled all the way to China to attend CIOE 2026, the event where the big players in the country's photonics industry gather
CEO Vickram Vathulya was there in early June and, according to a LinkedIn post, meetings with potential customers and partners were intense
As Serenity commented, if they confirm they're going to supply lasers to InnoLight (the market leader in global optical connectivity for data centers), the impact would be huge
There are several clues pointing right in that direction
If that happens, 200 SEK will be an understatement for $SIVE, and IMO it would easily justify over 1,000 SEK by 2029
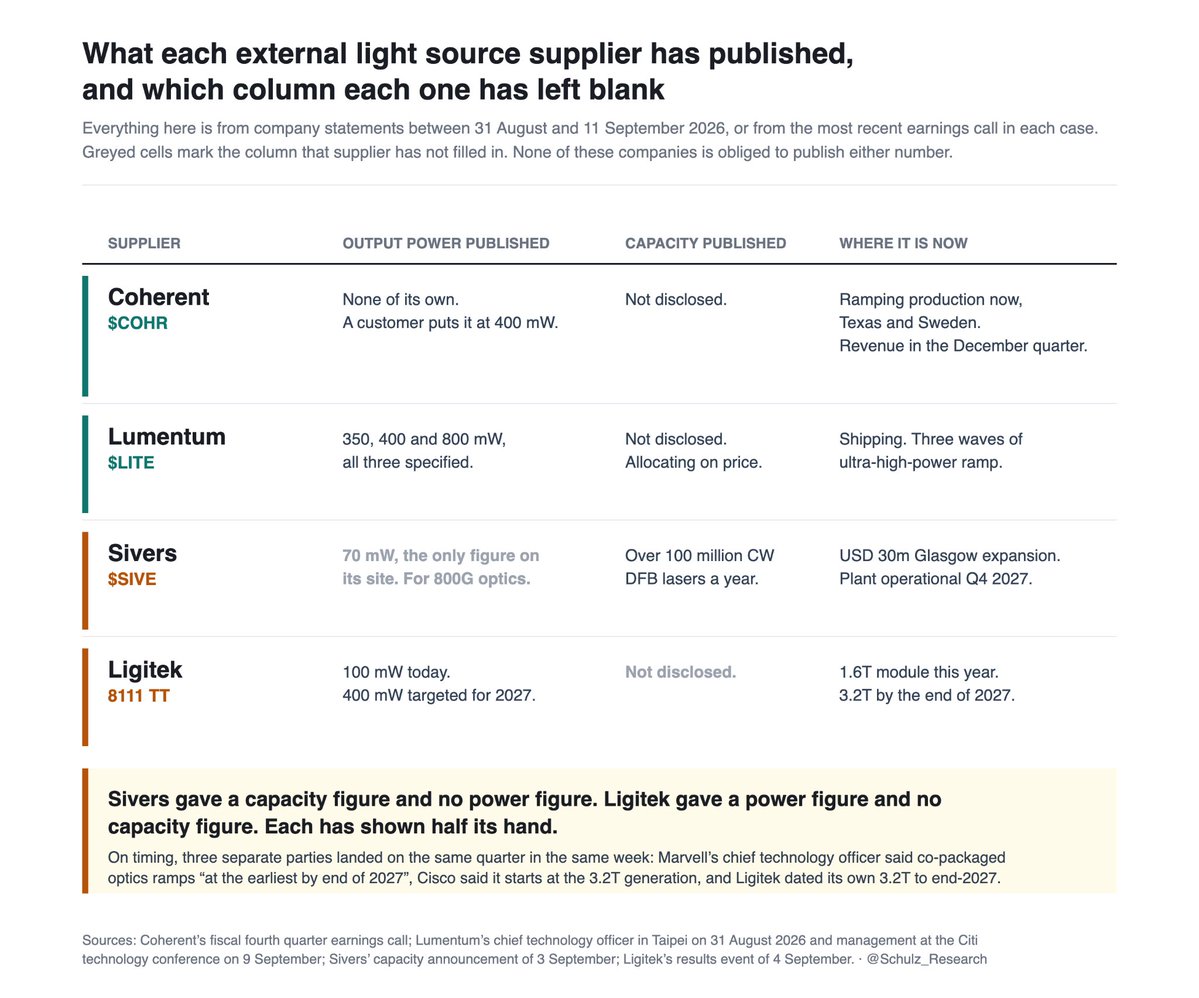
$SIVE raised prices, confirmed at its own CIOE booth this week, and channel checks put lasers across the 70 to 200 mW band up on ASP. That part is real and I am not going to argue with it. I spent this afternoon putting every published power figure in this chain onto one axis instead, and the rise is landing one curve below the curve the stock is being sold on.
Lumentum said the same thing about pricing two days before the show opened, in flatter language. Laser supply "is not really catching up," they do not see the supply demand gap closing "within the next couple of years," and they are allocating capacity based on price. Every deal they sign today is at equal or higher pricing than the escalator they already had in place. So the price rise describes the whole layer right now. It is not something happening to one company in it.
What separates the names inside that layer is power. Same call: "It's not going to be 100-milliwatt laser. It's going to be 150-milliwatt lasers or 200-milliwatt lasers." And then precisely, for all NPO and CPO work, "120, 150-milliwatt and above, which is not the traditional 70-milliwatt laser piece, which is used in today's pluggable market."
Sivers' own site lists exactly one in-sale product with a power figure attached. The DR8 1310nm at 70 mW, described as built for 800G and above transceivers. The eight-channel array is over 65 mW per channel. The other two chipsets say high power and give no number at all.
Lumentum's CTO stood up in Taipei on 31 August and specified its CPO external light source three ways: 400 mW first generation at roughly 20 percent wall-plug, 350 mW per laser in the sixteen-channel DWDM version, and a higher class above 1.0 W at 25 degrees. Coherent is not publishing milliwatts, it is just building them. Ultra-high-power CW lasers for CPO are ramping in Texas and Sweden right now, revenue expected in the December quarter, including volumes tied to its Nvidia partnership.
Lumentum saying it sees nobody else in high power is a competitor's line and it flatters them, so take it at a discount. The voice in this with nothing to sell is Lightmatter's Nicholas Harris, a buyer of these things, at that same Taipei summit: the laser engineers at Coherent and Lumentum "have taken the power to 400 mW," and 400 mW "is already very close to the damage threshold of the fiber."
Sivers is early on that side rather than absent from it. A USD 3.4m program with SemiNex announced 13 August covers high-power external sources and SOA gain stages, customer sampling and early production targeted for the second half of 2027. On 3 September it put USD 30m into expanding the Glasgow fab past 100 million CW DFB lasers a year, operational Q4 2027. So Sivers has published a capacity number and no power number for the AI tier, while Ligitek in Taiwan published a power number, 100 mW today and 400 mW targeted for 2027, and no capacity number. Each has shown half its hand.
The wait costs money. Q2 on 27 August: net sales SEK 53.8m, down 12% year on year. Operating cash flow minus SEK 70.0m. Equity per share from 3.55 down to 2.97. They raised roughly SEK 825m in directed issues during the quarter and converted a USD 12m loan to equity after it closed. Solvency is not the question, they have the cash. Dilution is, and it keeps showing up ahead of the revenue. Management's own horizon is a product business in 2027 and the long-term financial model from 2028.
One line in that report has stayed with me. SEK 42.9m of the EBITDA loss is a non-cash social security charge "related to the strong appreciation of the company's share price during the quarter." The share price going up is itself making the accounts look worse.
The bull case is not hiding either, which I respect. Asked this week whether he still sees all-time highs, Serenity said all it takes is a surprise announcement along the lines of Sivers powers Innolight, and added, "Could be anytime or never, who knows." That is an honest description of a catalyst trade. It is a different object from a spec sheet.
What would change my read: one published power figure from Sivers at 150 mW or above with a named customer against it. That single number moves the company from the pluggable curve to the AI curve and most of what I have written here falls over. Short of it, I would rather own the price rise where it is already converting into shipped product, $LITE at 946 and $COHR at 296 pre-market against $SIVE at 30.76 in Stockholm. And the argument has a date on it regardless: Marvell's CTO put co-packaged optics ramping "at the earliest by end of 2027," Cisco said it starts at the 3.2T generation, and Ligitek dated its own 3.2T to that same quarter. Everyone is building toward one window.