I sell data center capacity for a living. The conversation with customers has changed completely in the last eighteen months.
It used to start with price per kW. Now the first question out of everyone’s mouth is when can you actually give me power, and the honest answer in most major metros is later than you want to hear.
Everyone wants to argue about GPU supply. That is not where the wall is. The wall is a transformer you order today that arrives in three years, a permitting process that answers to a county board, and an interconnection queue with roughly 2,000 gigawatts stacked up in it. PJM ran the numbers on projects that came online last year and the average was over seven years from request to live power. Three years to get an agreement, four more years to actually energize after the agreement was signed.
And this is the easy part. We are nowhere near the peak of this demand curve. There is at least another order of magnitude coming, and the grid that is supposed to absorb it operates on utility capital planning cycles that were designed in a world where load growth was flat for twenty years.
Which is why the orbital compute argument stopped sounding exotic to me sometime around last fall. Up there you get uninterrupted sunlight, you dump heat straight into vacuum instead of running chillers, and there is no zoning hearing, no queue position, no substation to wait on.
Plenty of companies have interesting orbital compute concepts. Only one of them owns the rocket, has the scale, and deeply embedded partnership with Nvidia.
SpaceX filed with the FCC in January to launch and operate up to a million compute satellites, and there is exactly one launch provider on Earth with the cadence and the cost structure to make that number anything other than a press release. Starship is the reason this is an infrastructure plan and not a science project.
The constraint on the ground is the grid. The constraint in orbit is mass to LEO. SpaceX is the only company that has solved the second one.
$SPCX
Nvidia today announced that @spacexai will deploy Vera CPUs to accelerate its next generation of agentic AI applications.
"SpaceXAI plans to expand its AI infrastructure behind Grok on Nvidia Vera Rubin, while extending an optimized Vera Rubin NVL72 into space with its first-generation Starmind satellite.
SpaceXAI’s work with Nvidia is moving beyond AI factories on Earth. SpaceXAI is developing AI computing infrastructure for orbit, where power, thermal management, bandwidth, reliability and physical integration impose dramatically different constraints from conventional data centers.
SpaceXAI’s planned first-generation Starmind AI satellite will be based on the optimized Nvidia Vera Rubin NVL72 rack-scale system, extending the same accelerated computing architecture powering next-generation AI factories on Earth into space.
Nvidia and SpaceXAI are working to adapt that foundation to the requirements of orbital computing while preserving a common Nvidia architecture and software ecosystem.
This delivers one computing foundation across a wide range of environments: Vera CPUs accelerating increasingly sophisticated AI agents, Vera Rubin powering the AI infrastructure behind Grok and gigawatt-scale AI factories on Earth, and Nvidia accelerated computing extending into orbital AI infrastructure."
It isn’t just Elon saying it… listen to what Amazon’s CEO is saying about data center demand.
Amazon is spending $220 BILLION this year, and they’re STILL leaving meaningful demand on the table.
2026: Sold out.
2027: Largely sold out.
2028: A significant portion already sold.
That’s an incredible statement when you consider the amount of capital being deployed across the industry.
I work in the data center industry, and I can tell you firsthand that the demand is very real. We’re seeing enterprises looking for multiple megawatts of capacity with very few options available.
And despite the enormous investments being announced, bringing new capacity online takes time. Power availability, infrastructure, equipment, and construction all constrain how quickly supply can respond.
I continue to believe we’re in the early stages of a massive infrastructure buildout.
If you’re an enterprise planning your future compute needs, you should be having conversations about capacity today.
The competition for power and data center capacity isn’t going away anytime soon.
@HodlMagoo@elonmusk 🤣🤣 .. spoken like a true neocloud bag holder.
Magoo bought the top
After talking about the AI bubble popping for two years.. you jumped in. Just at the right time. Epic, sir. 🫡
@bot spin up a bot for me so I can track relative performance on all these AI names against SpaceX. Look at 1 week, 1 month, and 3 month each time.
Weekly updates. Let’s do it every Thursday morning. Create a similar graphic and send it to me in an email.
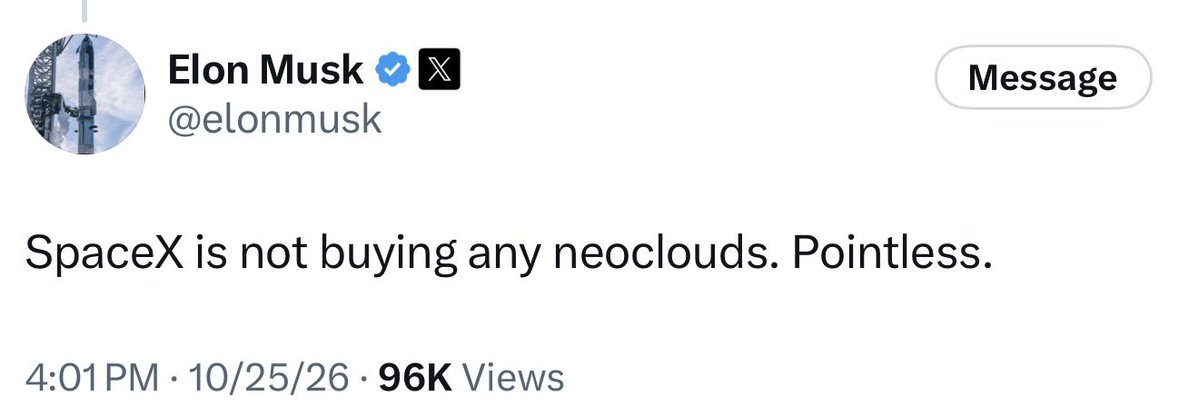
@BritishHodl SpaceX won’t be buying any neoclouds.
But as I explained earlier today in this thread, they might buy some of their distressed assets or unbuilt data centers where power permits are in place…
But nonetheless… yes. you should probably own some SpaceX.
Highly unlikely.
Far more likely SpaceX buys the distressed assets of neoclouds…
They will have no interest in taking over multi-year colo contracts and multi-year compute leases way under spot.
They’ll let their business model fail first, then come in and buy the assets on liquidation.
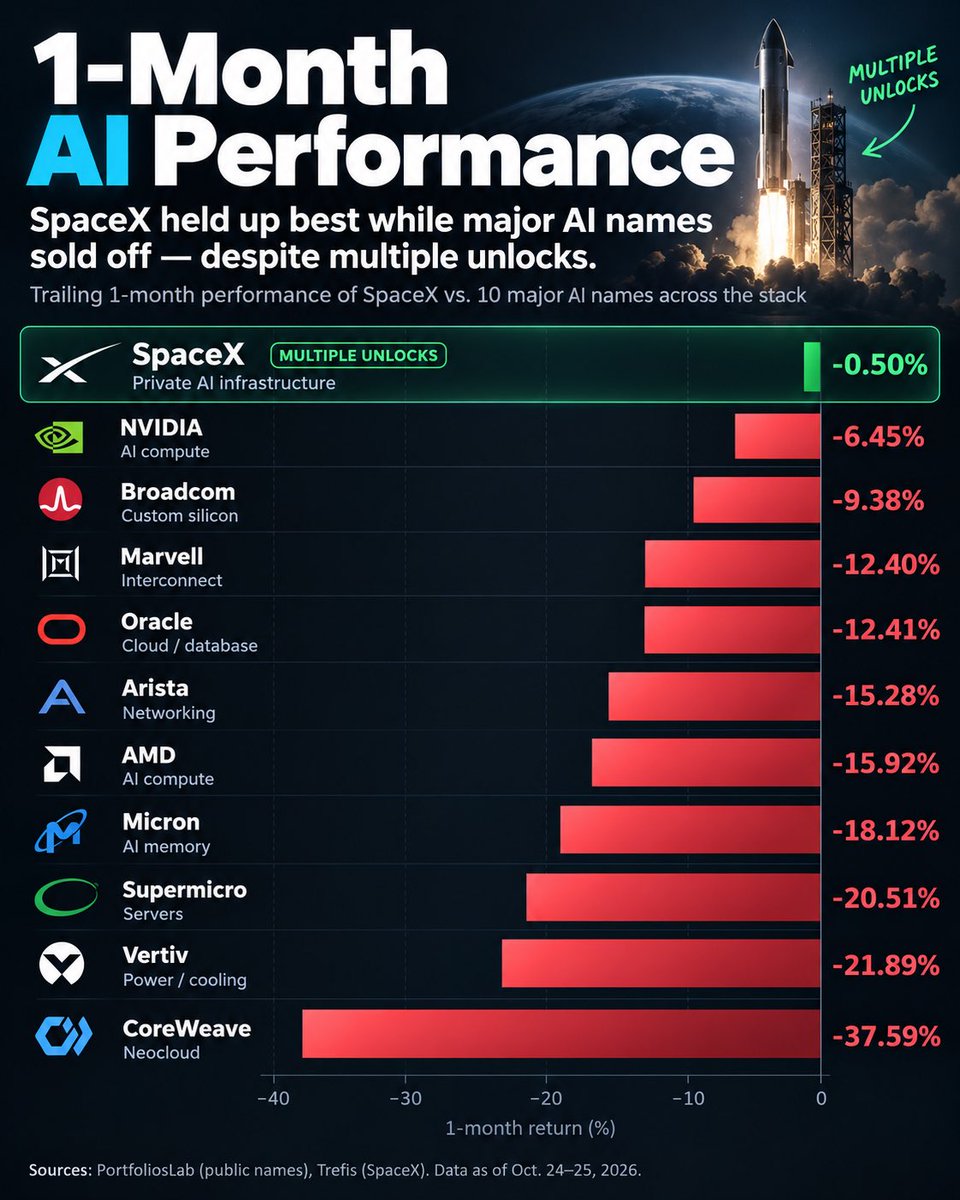
The *entire* AI trade has been getting hammered over the last month…
CoreWeave down 38%. Vertiv down 22%. Micron down 18%. AMD down 16%. NVIDIA down 6%.
Meanwhile, $SPCX is essentially flat.
And this is while SpaceX has gone through multiple share unlocks, with everyone’s parade of unlock FUD around potential selling pressure.
I think that relative strength is pretty telling.
SpaceX is building an AI compute business with economics that is the best in the industry, alongside Starlink, direct-go-cell, and launch.
The market is increasingly focused on AI infrastructure economics, and I am of the belief that SpaceX is best positioned. Period.
One month obviously shouldn’t make an investment thesis, but the relative performance is certianly hard to ignore.
My conviction grown, particularly coming out of the Q3 earnings call... hard not to be bullish.
The more I look at the economics of AI infrastructure, the more bullish I become on SpaceX.
David Sacks shared some fascinating numbers on All-In:
- SpaceX: ~$50B in monetization per GW, with roughly a 1-year payback.
- CoreWeave: ~$20B per GW, with roughly a 2.5-year payback.
These are estimates, but the difference is enormous.
A big reason is how the two companies structure their contracts.
CoreWeave relies heavily on long-term commitments to finance its infrastructure. SpaceX has the balance sheet and access to capital to operate with much shorter contracts, giving it exposure to today’s significantly higher compute pricing.
That flexibility is worth a LOT in a supply-constrained market.
And consider what happens when you’re recovering your capital in roughly a year. You can reinvest that money into additional compute, bring more capacity online, and potentially accelerate growth without relying as heavily on external financing.
Now consider SpaceX is targeting ~13 GW of operational compute capacity by the end of 2027.
The economics at scale could be extraordinary if they execute.
I’ve been extremely bullish on SpaceX for years, but the AI infrastructure opportunity has become a much bigger part of the investment thesis.
But those GPUs wouldn’t be instantly available to SpaceX. They’re already committed under multi-year agreements, including billions in contracts with Microsoft and NVIDIA.
Acquiring IREN means inheriting those obligations, including capacity they’ve already sold but haven’t delivered yet.
And even if customers leave when contracts expire, that’s years away. Meanwhile, you’ve tied up billions in capital acquiring and financing a business largely serving someone else’s customers.
I absolutely see the strategic value in acquiring powered sites, infrastructure and development rights.
I just don’t see the rationale for acquiring an entire neocloud business, and I doubt Elon has much interest in doing so.
Could be wrong, but I don’t see it.
A stock being down 62% doesn’t automatically make it cheap.
At $30, you’re paying roughly $12B for the equity. IREN also reported nearly $8B in debt and finance leases as of June.
I agree their power infrastructure is valuable. But why would SpaceX acquire the entire company, including its financing structure and existing customer commitments, when they could deploy that capital into infrastructure built around their own economics?
That’s the part I struggle with.
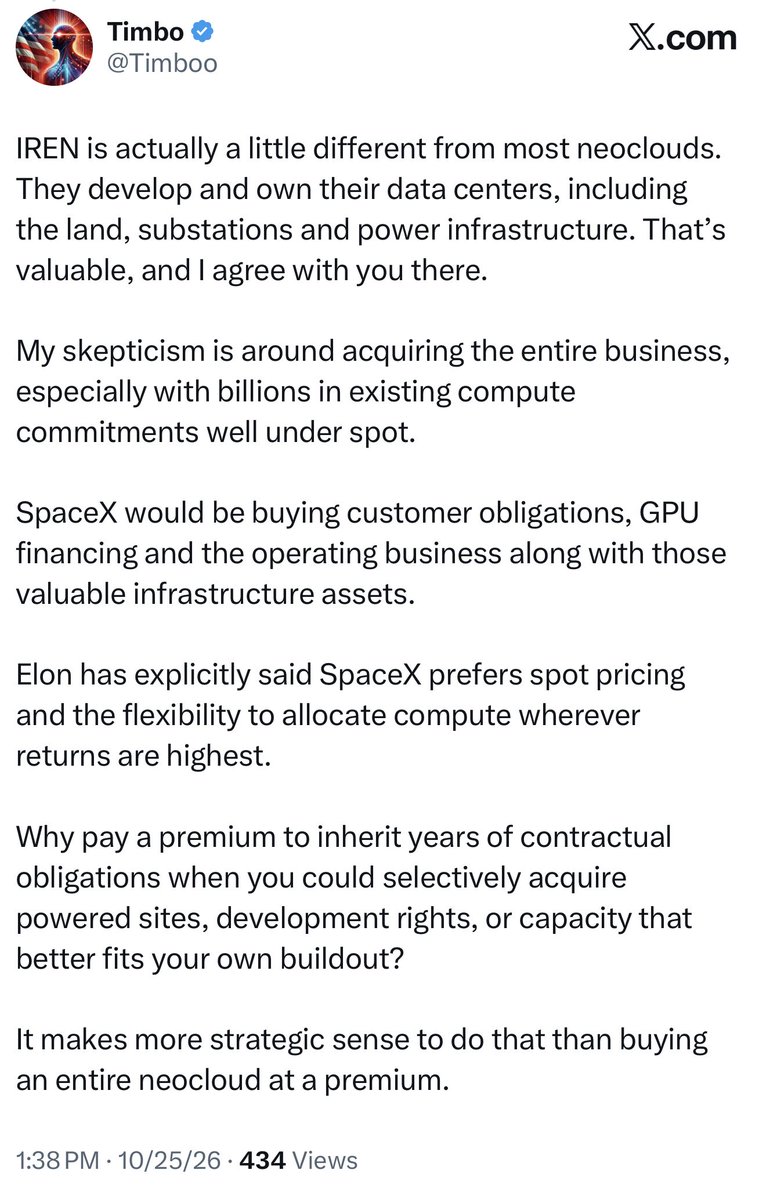
IREN is actually a little different from most neoclouds. They develop and own their data centers, including the land, substations and power infrastructure. That’s valuable, and I agree with you there.
My skepticism is around acquiring the entire business, especially with billions in existing compute commitments well under spot.
SpaceX would be buying customer obligations, GPU financing and the operating business along with those valuable infrastructure assets.
Elon has explicitly said SpaceX prefers spot pricing and the flexibility to allocate compute wherever returns are highest.
Why pay a premium to inherit years of contractual obligations when you could selectively acquire powered sites, development rights, or capacity that better fits your own buildout?
It makes more strategic sense to do that than buying an entire neocloud at a premium.
@SPCXTSLA@elonmusk@LeeMatt17631@Yuchenj_UW They essentially do this now… Nvidia requires proof of power. If you don’t have the power and place to put them, you aren’t getting GPUs.
You’re talking like SpaceX is starting from zero. 😂
NVIDIA called Colossus the world’s largest AI supercomputer, and the team built it in 122 days. Jensen himself praised the execution.
SpaceX already reached 1.7 GW of nameplate compute in September and expects 2.5-3 GW by year-end. They’ve proven they can execute at scale.
They’re also a major NVIDIA partner, with plans to deploy Vera Rubin. That relationship is going to be incredibly valuable given demand for next-generation GPUs.
As for funding, you’re completely missing the economics.
SpaceX had nearly $90B in cash at the end of Q3. They have access to debt markets, and their CFO just reiterated that new compute deployments are generating payback periods of LESS than one year at current pricing.
That’s what we call a flywheel… Deploy compute, monetize it, recover capital, reinvest into more capacity.
Nobody is suggesting 13 GW is easy. But dismissing the company that’s already demonstrated this kind of execution because you don’t like Elon is pretty funny.
Potential is an understatement.
Just look at what SpaceX has already accomplished, and now consider the opportunities ahead in AI infrastructure, Starlink, direct-to-cell, Starship…. I genuinely believe we’re still in the early stages of what this company will become over the next decade.
Super early IMO.
@rallenhughes@DavidSacks The biggest challenge in building data centers today isn’t really finding land (albeit it is a component). It’s finding enough power.
You need ENOURMOUS electrical capacity, substations, cooling infrastructure, and fiber connectivity….
that advantage only grows as SpaceX scales. Neoclouds need long-term contracts to finance expansion, while SpaceX has the balance sheet to move faster and capture higher market pricing.
Higher returns per GW, faster payback, and more capital to reinvest. That will compound into an enormous competitive advantage over time
@BoBbyPleWniaK The market doesn't owe anyone a tax-efficient way to get exposure to an investment they wish they'd made earlier.
If you want exposure to $SPCX, allocate capital to it.
Couldn't agree more.