My God, J.Dorward doing deals again. $ssrm.to acquire the Converse project form $rm.to. Roxmore shareholders get 6.75$/sh cash + exploration spinco shares which will retain the other Roxmore projects.
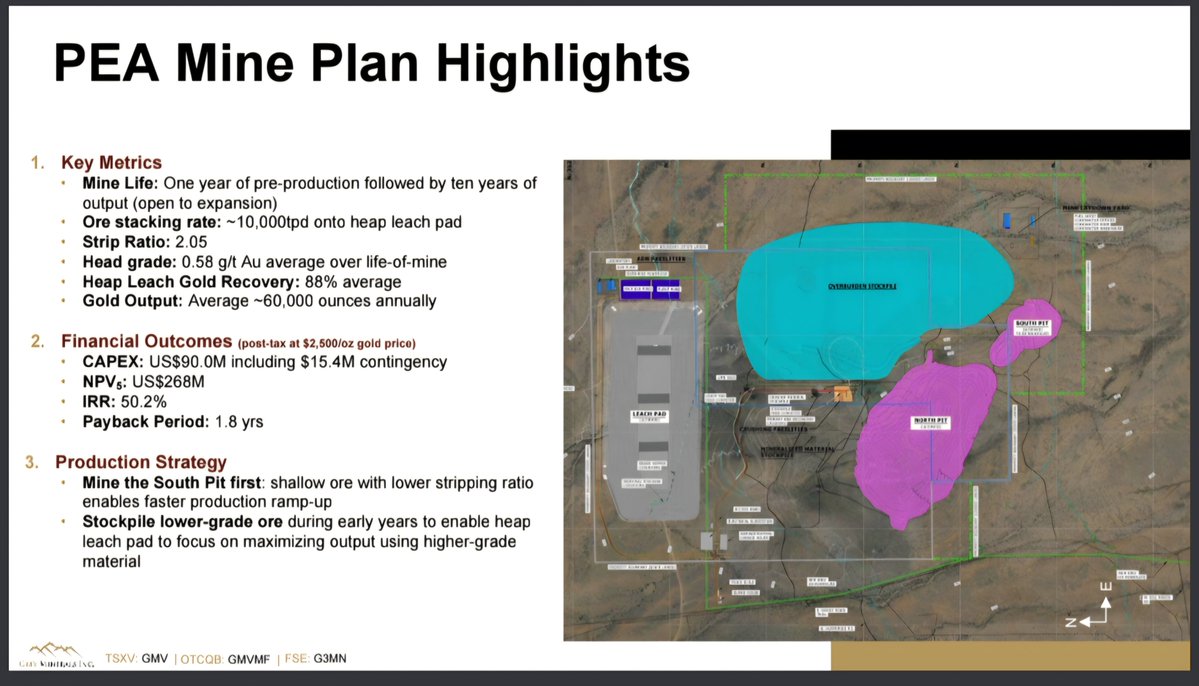
@inigoezponda Yeah recoveries are high for a heap leach, the lab results showed strong recoveries, like 90% in some test (dont have the exact numbers now) but they have to do further studies. Lets see the resources conversion on the next MRE.
Its perhaps a little bit utopian, but here is my general (retail) investment strategy:
I am metals focused. I do not hold a diversified portfolio, b/c I do not want to dilute performance with average stocks I probably do not understand.
This is therefore, obviously, a higher risk strategy.
I am bullish PM & base metals over the next 10-15 yrs, which is my current expected timeframe; while its exciting to see metal price action the last 18 months, I have lived & worked a brutal 30years of painful market downturns with a few, short-lived upturns. So this "dampens" all my investment decisions which therefore have to be into Co's I believe could survive any downturn or crash. I prefer to avoid day/week/month trading on trends, but admit I have have been trapped by this a couple of times. That aside I have been most successful holding a stock over a few years rather than weeks/months sometimes through -40% downturns. Good businesses recover from these, bad ones do not.
With this in mind I look for solid Co's which still show cash flow when modeling -35% metal prices. AIC & AISC per unit metal produced is important to me. I avoid Co's that have royalties & streams on the assets as much as possible b/c this REALLY RUINS Co. ECONOMICS & retail value & often steals the security of the assets from the SH's too.
Then- KISS- Keep it simple stupid:
Simple, relatively easy to mine & process --> Must, surely, therefore make cash easily.
If the team is good & the AIC is low & there is CF or near term CF & there is a clear path out of any debt, then I look deeper into the asset and try to decide what the resource or future expanded throughput might look like.
On the basis of the above I will then consider buying a stock.
$MARI.TO & $RIO.TO both potentially meet the above requirements, but are on development phase of the L curve, therefore should have a better delta over & above another Co. operating at steady state which normally are at full value and provide DIV's as a mans to dropping my acquisition cost. But they also have to have no community issues (fatal flaws) and no government permitting dramas (fatal flaws).
I will v. likely not exit at 1st production & hold these stocks LT through commissioning into steady state ops to enjoy the CF, unless they start doing more acquisitions. Then I will usually look for a time to sell.
When do I sell? When I am frustrated by the lack of SP performance against whatever applicable metal price.
I average down a little in big downturns if I have the time & opportunity. I average up in big upturns if I have time.
I don't check in on my stocks daily, b/c I have a pretty demanding day job & I am not interested in short term delta.
Otherwise I usually sell when I need cash or want to rotate into a fresh story. But my aim is to HODL long term as a hedge to FIAT and will sell out probably 50% in the next 10-15 yrs if things go well in that period.
My dream stock is one like $CMCL which -if I hold long enough- should pay me a decent % of my acquisition cost from dividends. I view it as a store of value for me rather than an investment to make money on, until I think it is not this.
I try to "make real money" by operating (my own) mining assets in the private space.
Good question @lachl11733, thank you. 🙂
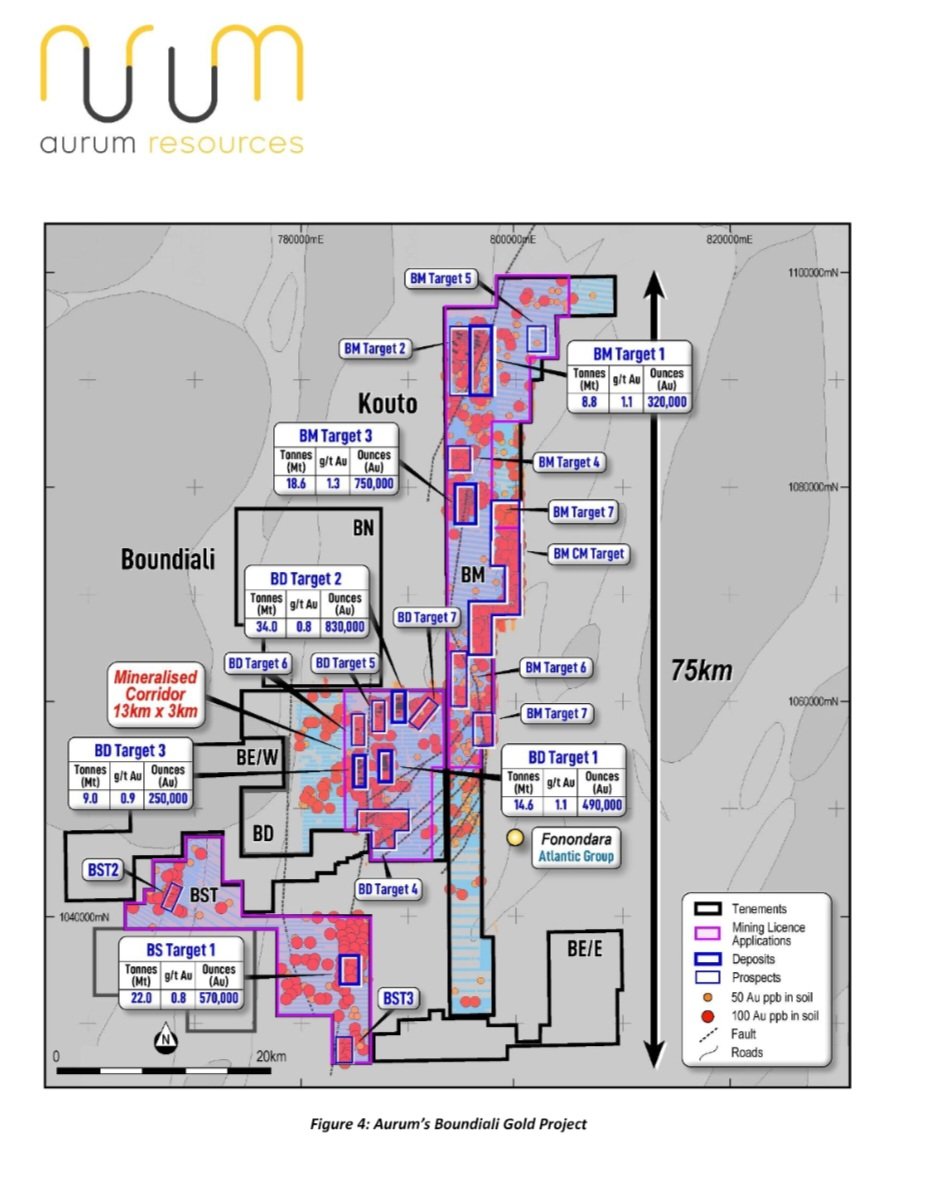
We’ve received results from 60 diamond drill holes across BMT1, BMT2 & BMT3 at our 3.22Moz Boundiali #Gold Project. Results will be assessed for inclusion in the next Boundiali MRE, targeted for Q4 CY2026, feeding the Boundiali DFS, expected late CY2026.
https://t.co/3u2E8IJRkw
This week, Aldebaran released drill results from the Altar #copper#gold project in San Juan, Argentina, including an intercept of over 1700 M at 0.45% CuEq
John Black spoke with @TrevAHall on Mining Stock Daily to add more context: https://t.co/2MFlsqRBQd
$ALDE.V $ADBRF ⛏️🇦🇷📈
https://t.co/dbUahIEWpv
Interesting exploreco. 11km max. width of Muskox intrusion, they basically looking at a gigantic magma body that solidified underground. 60 high-priority targets identified. Waiting for the 27 drilling campaign...
"Intervals represent true thickness of the deposit"...in football terms, this is like Barça winning 7-0 againts Madrid & Yamal scoring a hat trick...just awesome. $alde.v
Aldebaran Reports 1,728.9 m of 0.45% CuEq (0.41% Cu, 0.03 g/t Au & 1.34 g/t Ag), including 756 m of 0.68% CuEq (0.61% Cu, 0.03 g/t Au & 2.12 g/t Ag) at the Altar Copper-Gold Project in San Juan, Argentina $ALDE.V https://t.co/GUELnbJyJ4
Aldebaran Reports 1,728.9 m of 0.45% CuEq (0.41% Cu, 0.03 g/t Au & 1.34 g/t Ag), including 756 m of 0.68% CuEq (0.61% Cu, 0.03 g/t Au & 2.12 g/t Ag) at the Altar Copper-Gold Project in San Juan, Argentina $ALDE.V https://t.co/GUELnbJyJ4
$aue.ax BST1 already has a 570 koz resource & only 145 koz in the PFS reserve. 16 owned rigs mobilized to drive resource growth at Boundali. 4.4Moz combined group resources & A$95M Cash. MRE & DFS next.
That feeling when you're playing chess and you plan a move then make it and even though it looked small and more of a continuation of the entire strategy, after the move you slowly realize it's more important for the game than even you realized. And you smile internally. $MARI.to
Marimaca is pleased to announce various development activities at the MOD, including the receipt of the grid connection authorization and the key commercial terms for a PPA framework.
Read the announcement : https://t.co/cWhTr45Gnr
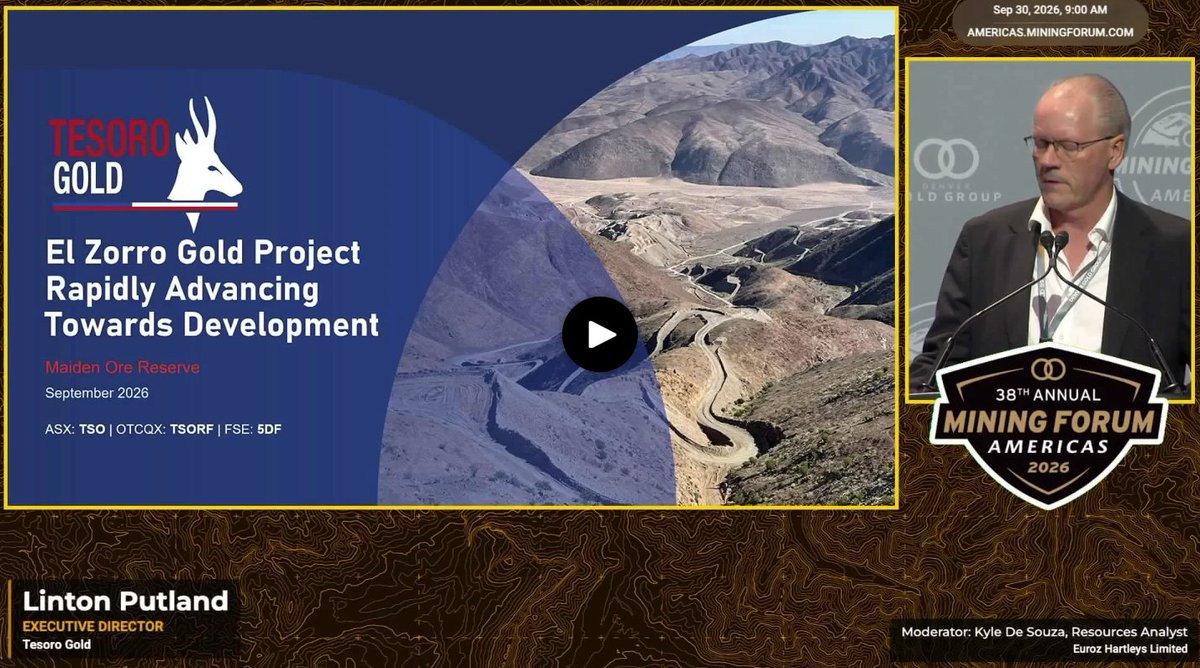
The recording of Linton Putland’s presentation at the @DenGoldGroup Mining Forum Americas 2026 is now available. Linton provides an update on El Zorro, including the 1.28Moz maiden Ore Reserve and pathway towards FID in Q1 2027: https://t.co/cOrYVJHjCx
We’ve hit a project-best gold intercept at the BST1 deposit at at our 3.22Moz Boundiali #Gold Project in Côte d'Ivoire.
28.80m @ 22.92 g/t Au from 204m, incl. 17.95m @ 36.57 g/t Au, the highest grade-thickness intercept reported at Boundiali to date.
https://t.co/904hCYuGPg $AUE
$ELT (~A$197m) is pre-production: Oropesa (Spain) first, Cleveland (Tasmania) second. Cash ~A$40m, no debt. Up 22% today
You could have bought for half the price if you’d listened the first time
Tin ~US$54,000/t, near June’s US$57–59k high: about +35% YTD and double early-2024. Oropesa’s DFS used US$30,000/t
Tungsten: China mines ~80%. Export controls and a Jan-2027 US defence ban have European APT at ~US$2,700–2,900/mtu, still more than triple this year.
Oropesa: EU’s only advanced tin mine. 3,405 tpa ingot, 12 years, AISC ~US$15k. Permits guided end-2026/H1 2027, then FID. 50% Spanish smelter option is unconditional. How many tin mines own a smelter close by ?
Cleveland is the Tassie tungsten path (no separate “Tasmanian 10” mine): 8.5 Mt at 0.24% WO₃, sorting to 0.98%. Scoping study late 2026/early 2027. Inferred only.
2027 MC speculation, not a forecast. DFS NPV was A$270m at US$30k tin and A$587m at US$38.6k. NPV escalates very quickly , remember its $54k at the moment
If permits and funding land and tin stays high: A$400–700m base, A$800m–1.2bn bull. If permits slip or tin mean-reverts: A$150–250m. Dilution for ~A$260m capex, ZEPA and inferred tungsten can break any of those.
A low risk no brainer IMO
Tin and Tungsten in one company
I obviously hold :) good luck