It’s funny because we said 3 months ago the future hedge fund analyst job will be to collect esoteric information
This is another step forward to automate that part of the job
My theory is that relationships and access to semi-private information will be all the alpha up for grabs in a few years
It's earnings season, and after the calls, executives make the podcast rounds, often on shows you'd never think to check.
So we built Ethmos: research agents that track the companies you cover, catch every executive appearance you might have missed, and brief you each morning.
Fake it till you make it:
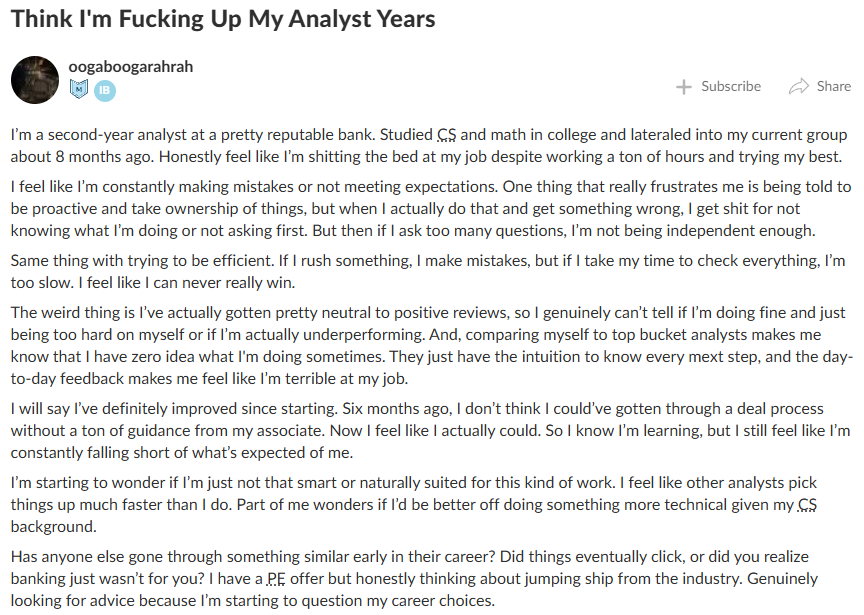
> Second year analyst at a good bank
> Completely shitting the bed (making mistakes, not meeting expectations)
> Inefficient
> Despite this, still get neutral/positive reviews from Seniors
> Not sure whether to stay or go
Sometimes, having a good attitude, showing improvement, and willing to learn is all it really takes
Back when I was an intern we were going through a small group training dedicated specifically to my group.
In the excel template we were using, there was an error that the associate running the training pointed out to us.
It was something that would be super hard to notice if you weren't looking for it.
He chalked it up to "everyone being too lazy to fix it in the master file."
I figured it was strange, noted it, and moved on. Come the end of the Summer for final presentations, 2/3s of the interns in my group failed to fix the error in the master template in their own copies.
Not all of them didn't get returns, but all that didn't get returns were in that group.
When I went back full time, I offered to fix the error in the master doc, but it turns out that it's intentionally left there for the interns to see who can remember the simple stuff.
Nowadays I bet Claude would catch it in one pass.
L40 ran the payback math on how much a PE buyer can pay for a software company, and the gap is bigger than most founders expect.
Two software companies each make $10M of EBITDA today. A PE buyer can pay about 5x for one and about 11.8x for the other.
If EBITDA stays flat, five years of earnings adds up to about 5x today’s EBITDA. If it grows 30% a year, five years adds up to about 11.8x.
One active software acquirer told L40 it needs deals to pay back within four to five years, or six at most. So the buyer is paying for the earnings it expects to get back over that window, not for what the company makes today.
That’s why two companies with the same EBITDA can get very different offers.
Would you pay 11.8x for 30% growth you have to trust will last five years?
81% of US firms told the Richmond Fed that neither the cost of financing nor access to it has constrained their investment or spending plans, per Apollo.
Those are two different things. A company can find rates expensive and still have no trouble raising money, or the other way round. When both are fine for four out of five firms, it’s a fair sign that credit is flowing. That’s a different story from what you’d expect after years of higher-for-longer rates
Jon Gray breaks down 3️⃣ takeaways from $BX’s 3Q results: the firm once again delivered for clients, the underlying economy remains strong despite the rise in cost of capital, and scarcity of compute is supporting the value of AI infrastructure. 💪✨🏗️
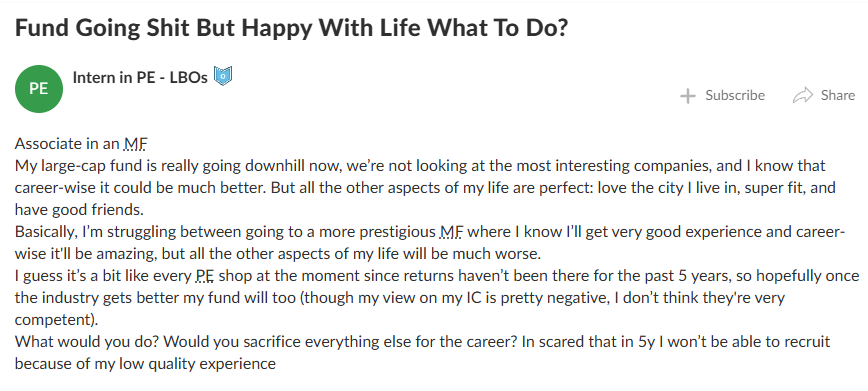
What would you do?
> Associate at a Megafund
> Weak recent performance
> Life is perfect (Good city, healthy, great friends)
> Incompetent IC
Stick it out a little longer and love your life or try looking for something new?
The marketing function is getting automated now.
If you aren't generating money for your business, you are a cost center and are at risk of being replaced.
Backed by Anthropic too so you know you're cooked.
>lead product for news feed and creator monetization at meta and X >spend years seeing exactly how things grow in the feed >cofounder scaled facebook groups to 1bn+ users >build nectar >$40mm+ raised, backed by Anthropic's Anthology Fund
I spent way too much time doing busy marketing work while building Pari Passu, no alpha in that - great to see this!
Blackstone $BX released earnings this morning. I read the transcript, so you don’t have to:
> A tighter AI financing environment will help Blackstone, as they are uniquely positioned to offer capital solutions which will allow them to earn a higher yield.
> Distributable Earnings: Blackstone reported distributable earnings of $1.7B, underpinned by a growth in fee-related earnings and fewer realizations than previous quarters, as expected
> Private Wealth: Assets from the Private Wealth channel grew 15% YoY to $330B. Fundraising for perpetual strategies increased significantly QoQ.
> IG Private Credit: IGPC grew 24% YoY and is increasingly being supported by pension and SWF LPs rather than solely insurance. The broader industry is seeing tailwinds from IG corporate borrowers looking to tap the private markets for customized solutions.
> PE: Returned 2.8% for the quarter and 15% on an LTM basis.
> Non-IG PC: Returned 2.6% for the quarter and 7% on an LTM basis.
BREAKING: Claude can now build your board deck like a $309,068-a-year investment banking associate.
Open Claude Code with Anthropic's free financial-services plugins, put this quarter's model, the budget, a GL export and last quarter's deck in one folder and run these 7 prompts:
If you are a gifted 18 year old going to a top college, traditional Finance is decreasingly becoming the place to go.
Why would you go to a bank or investing platform where you're going to make a mid hundred-thousand dollar base salary plus bonus when you could go to somewhere like:
1) Quant shop and make $500K plus
2) A startup where you can get equity that could turn you into a multi-millionaire in a couple years
3) AI roles which, to be transparent, I'm not super well aware of how the pay works, but know it has to be lucrative or the top talent wouldn't be going there.
The Harvard valedictorian doesn't want to work at Goldman and earn $120K base + 100% bonus while working 100 hours a week.
And frankly, Goldman doesn't need the Harvard grad either.
The entire AI infrastructure complex is now in a bear market.
Drawdown since all time high
> GE Vernova: -22%
> Quanta: -24%
> Eaton: -18%
> Vertiv: -47%
> Bloom Energy: -32%
> Constellation Energy: -33%
> Coreweave: -67%
> IREN: -64%
Either a falling knife or a generational buying opportunity, depending on which side of the AI debate you sit on