@PoornimaNimo Accusing a little boy of bad behaviour based on a tv show is completely unacceptable! This post to supposedly “raise awareness about bad parenting” is horrible, encouraging bullying of a child by adults! Shame on you Dr Poornima! Begs the questions who is really poorly raised
Spotted on the roads of Hyderabad, yesterday afternoon sometime, an ambulance in a hurry! Or was it an ambulance at all? Read the ticker carefully!escort services using the alarm of an ambulance, or ambulance making side money? …look into it @hydcitypolice@HYDTP@ghmc
@pgcilindia@MinOfPower@mlkhattar
As a unitholder of POWERGRID Infrastructure Investment Trust (PGInvIT), I would like to let you know about its performance, which has been substandard, unsatisfactory, and below par due to a lack of fresh investment.
Since its listing, PGInvIT has not taken any initiative to increase its portfolio size. Why is this?
How will you reassure shareholders that the performance of the Trust will improve?
I recommend that you investigate this matter at your earliest convenience.
there are apparently “personal problems” and honestly IDGF, half pieces have arrived, other are still stuck in factory, no one has a clue what’s going to happen next, been saying “tomorrow” for the past 3 days! caused such chronic problems! Really disgusted
@fenestawindows I don’t know if you are having some kind of existential crisis in your Hyderabad factory, but this is the worst delivery operations ever experienced!
My current opinion on Hotel Stocks : 10 Apr 2023
This is a cyclical sector. Room rates, occupancy rates, F&B income, operating leverage, new supply - they all rise in the up cycle.
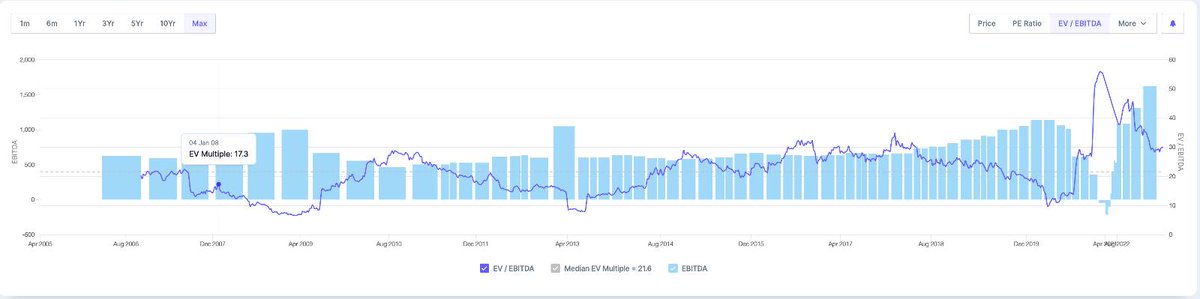
But the market’s music stops well before the fundamentals reflect the perception. Stonks reach their peak and EBITDA keeps climbing for several quarters ahead with bullish management commentary, new M&A (Remember Ratan Tata’s acquisitions?), further addition to supply, buy reports from brokers, occupancy moving up and matching previous room rate increases. It’s a heady cocktail. Therefore, it is dangerous to rely on fundamental data to time the exit. (See picture below for IHCL, EBITDA rising when stock peaked in Jan 2008 at 135. By the time EBITDA peaked in Apr 2009 the stock was at 35). Thanks @faltoo for screener :-)
Also think about this, IHCL stock hit 348 in the beginning of Oct 2022 before the company had its best quarter ever ie., Q3FY23 accounting profits were more than any YEAR’s profit in the history of the company. The stock is at 328 today. This is just a small trailer of how the difficult it is to time the exit.
Remember Remember : These businesses have the optical illusion of free cash flow. They come in on a quarterly basis tempting the investor. But through cycle they turn into maintenance capex right before your eyes. The market knows this only too well.
30% + EBITDA margins should come down as occupancy rises in this cycle. The Tata group will perhaps continue to do peak M&A in airlines and hotels. FTA should go up further.
Basically, you need to be a genius to sell close to the cycle top. You somehow need to figure out at what point is the optimism fully discounted while management continues to guide for better growth on CNBC. All the best.
My thesis at the time of entry was different. I was buying the proverbial rupee for 50 paisa post the pandemic hit. Now I have the headache of getting stuck into an up cycle. I really don’t like investing in cyclical plays, buying durable and okay-okay business for cheap with 2-3 % allocation. I can’t size aggressively and I don’t know when to get off the ride. And yet I do it because it works. I guess there are some who can take concentrated bets on cyclicals like the Chandler brothers did when they ran Sovereign, but last I heard even they went the grandpa Buffett way and now prefer to concentrate on secular durable high RoCE businesses.
With cyclicals and mean reversions in general, I get stuck in the portfolio way of thinking. Which I increasingly believe is the enemy of sound private capital. My conviction stands - that the single biggest competitive advantage for sensible private capital is to concentrate big size in a few opportunities. This is a no go in institutional thinking. It’s ergodic…variant… It goes against the values of the average for at their heart that’s what institutions are all about - playing for the average outcome, serving the average person - and perhaps rightly so. In which case indexing remains a no brainer and your chief trouble is to find something to do with your time . @passivefool is doing well here :-)
Given all the complexity around selling, there is only one way forward. I have to use my magical powers. So for the Indian Hotels Company Limited …Abracadabra.. the important numbers indicating future stock price are 280, 348, 415, 500 and 635. After that you’re on your own :-)
#valueinvesting #hotels #travel #stocks #investing #ihcl
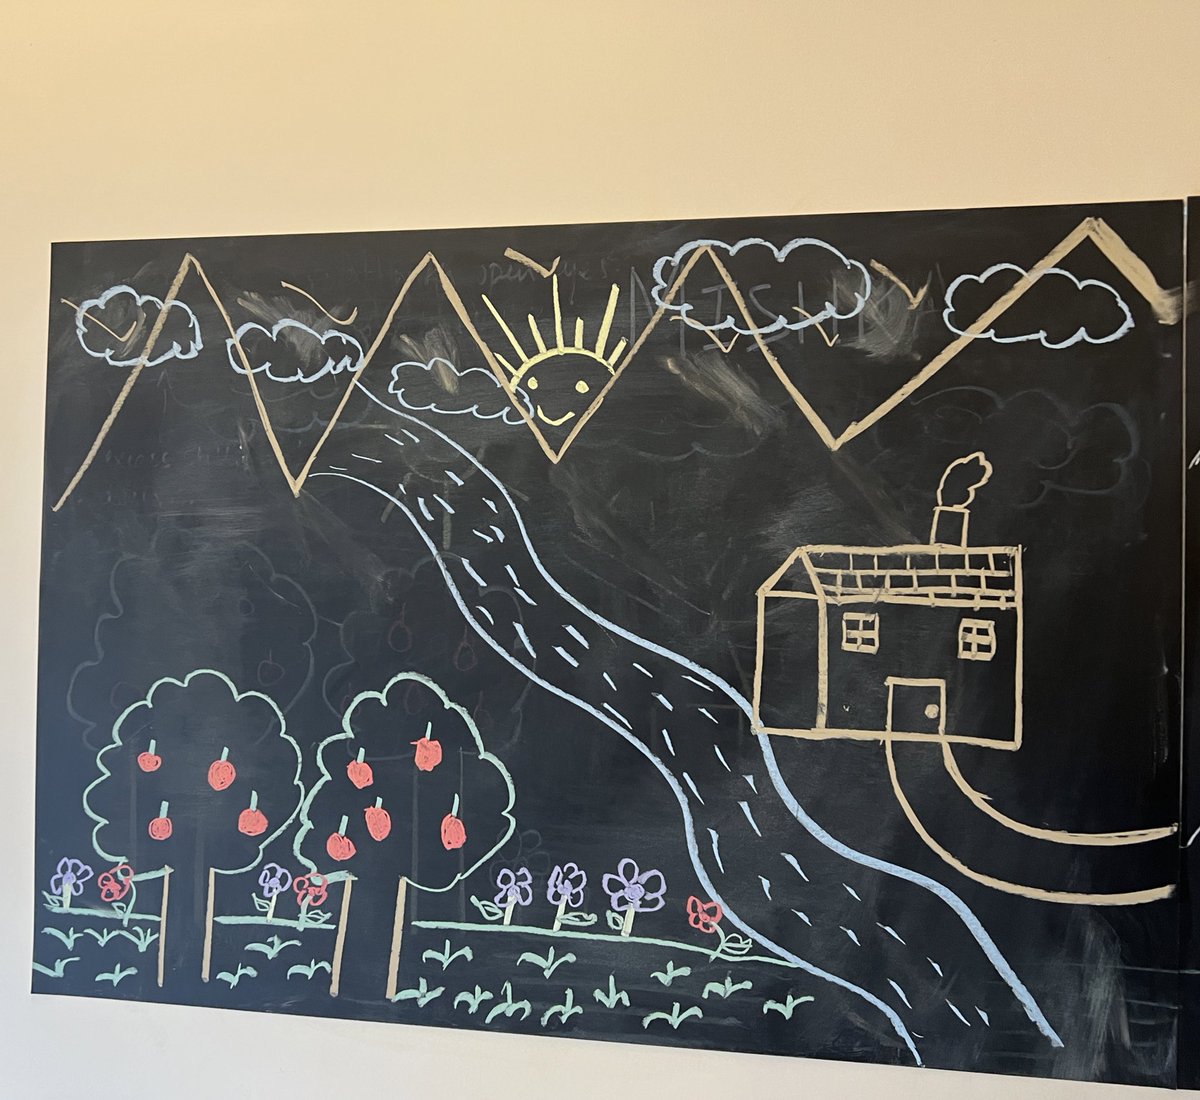
It had to be 4 mountains, smiling sun bang in the middle with 1 short-1 long sun rays; a river flowing from the 2nd mountain running by an out of perspective house (trees, flowers optional). For me, this was literally every art class ever!😅 Similar memories anyone? #throwback
It had to be 4 mountains, smiling sun bang in the middle with 1 short-1 long sun rays; a river flowing from the 2nd mountain running by an out of perspective house (trees, flowers optional). For me, this was literally every art class ever!😅 Similar memories anyone? #throwback
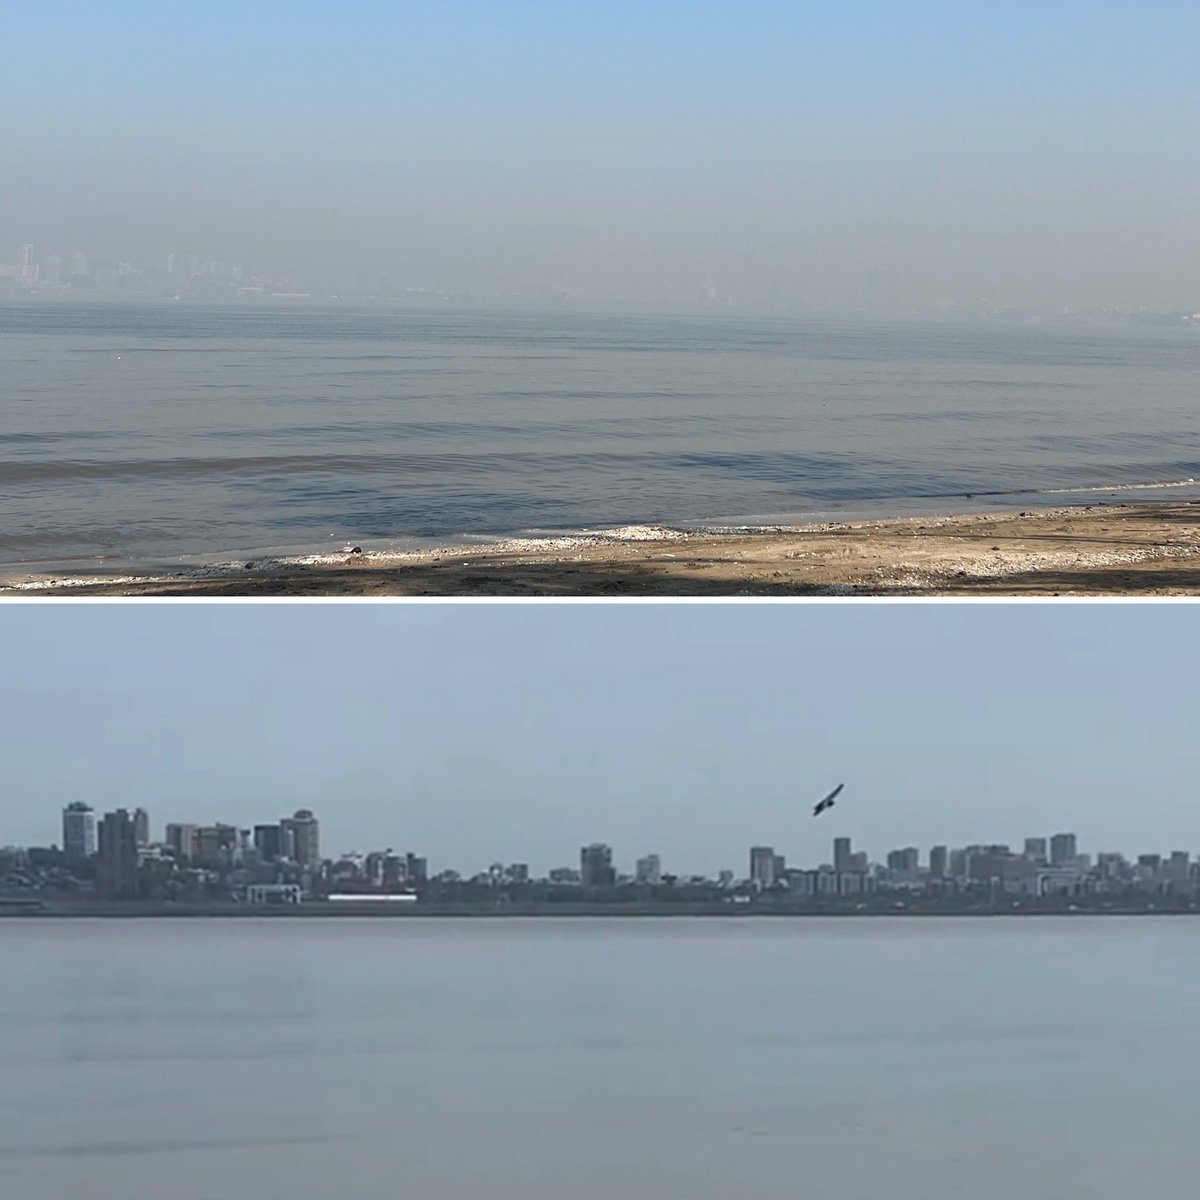
Can’t get over how #pollution levels have worsened in #mumbai…Here’s the view from Dadar beach today versus in what it was in 2021. #Mumbaipollution#smog