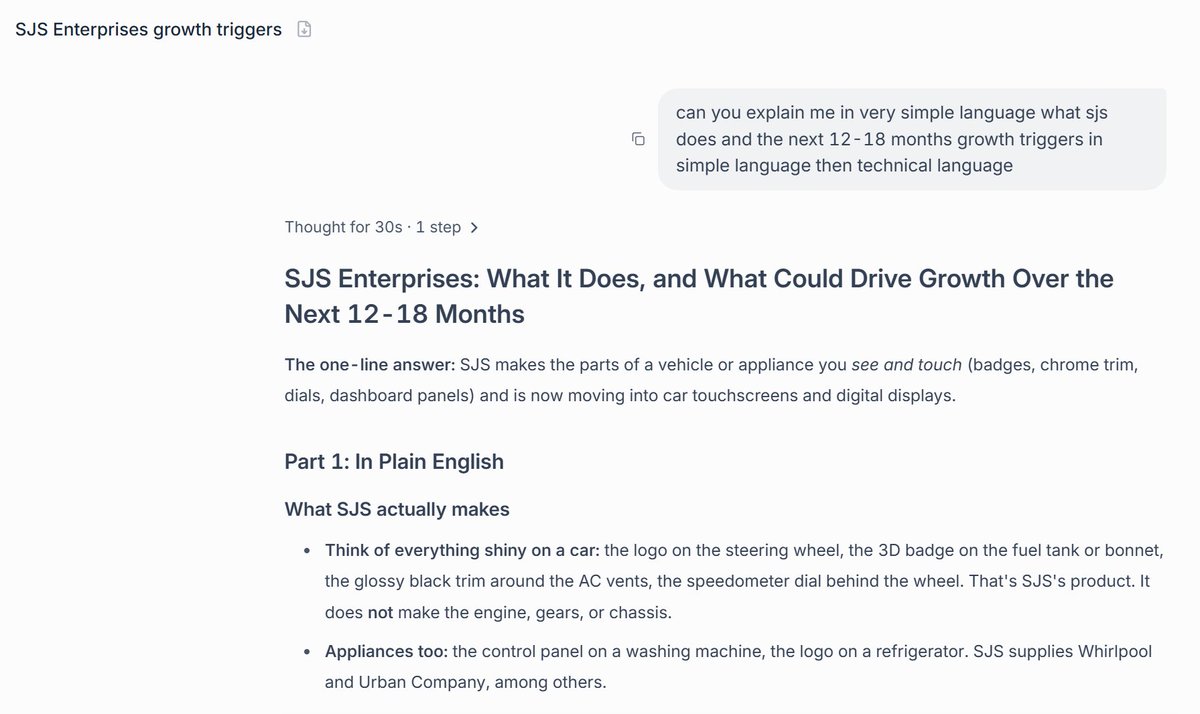
I feel like I should cancel my Claude subscription. I mainly used Claude for stock research, but @stockscansin does it way better, faster, with proper sources and much more focused analysis. Super feature of Research AI
I think MDR on UPI was probably inevitable at some point, especially given how widespread UPI adoption has become. It could also lead to more competition, instead of just three apps accounting for more than 95% of the market.
That being said, there are some use cases, like investing and broking, where the proposed MDR structure doesn’t really make sense.
The problem with broking is that there is no guarantee that money transferred to a broker will actually result in a transaction.
As brokers, we can’t force a customer to trade after transferring money. And if we can’t pass the UPI charge on to the customer, there is essentially no limit to the cost a customer can impose on a broker without generating any revenue.
Just as an example, 10,000 customers could each make 50 UPI transfers of ₹2 lakh in a month without executing a single trade. At the proposed MDR, this could potentially cost the broker around ₹2 crore, without generating any business.
What makes this even more challenging is quarterly settlement (QS). This is a SEBI regulation that requires brokers to send unused funds back to clients every month or quarter.
Most customers then transfer these funds back to their broking accounts, with more than half of these transfers happening through UPI. So regulation essentially forces this movement of money every month or quarter, and the broker could end up bearing the cost when the money comes back, without any incremental benefit or revenue.
By the way, we currently don’t charge brokerage on equity delivery trades because the economics allow us to offer them for free. But if every UPI transfer starts carrying an additional cost, irrespective of whether the customer actually trades, I don’t see how we can absorb this indefinitely.
I think having an MDR is okay. It still doesn’t solve the problem of customers transferring money without transacting, but something like 0.02% with a cap of ₹5 or ₹10 per transaction seems much more reasonable for broking, instead of a cap as high as ₹300.
I am just amused as to how are some people defending this blunder of a move by @NPCI_NPCI & Government alike
Media houses presenting it as "Nominal" charges really have no understanding that this is a charge on Topline+GST of any business which makes this a big hit on the bottomline
They are not going to charge it on sales but on collection by the Merchant which is Sales+GST which is horrific!
Really glad that @Ashneer_Grover stood out & rightfully pointed out that this levy is pointless as non of the ecosystem participants were holistically losing any money
This move would not only discourage merchants from doing UPI but this would also make businesses even more incompetitive & of course such intervention never helps the ease of doing business narrative
You just make businesses a hopeless exercise just because you feel they earn it so they will have subsidise for everything
Managing costs is literally becoming impossible & such taxes cum charges never help
#Upi #npci #MDR @narendramodi
First we killed the capital markets with consistent increase in STT, capital gain , dividend
Now we will slow down UPI too and further increase cash in circulation. 0.4% MDR is too steep!
The financial think tank is undoing all good work done by the govt.. too much arrogance.
Crisp video on How to use IPO Scans...
Use "IPOSCANS" for subscribing or renewing your StockScans Premium Subscription.
Disc: Not a Buy/Sell Recommendations.
#StockScans
Golmaal is back! Watch till the end!
Here are 4 companies trying to fool consumers by their marketing!
If any company mentioned in this video is planning to send me a defamation suit, just remember, I will send you a defamation suit back for misleading Indian customers!
POSITIVE AGGRESSION!
Share this video and let's make India healthy again!
If you deploy 45,000/- per year for 20 years in LIC’s New Money Back Plan, after 20 years you will get ~12.5 lacs!
Annualized return: ~3.33% per annum.
That’s not insurance, that’s daylight robbery disguised as tradition.
What is somewhat disappointing is that large corporate houses looking at disrupting businesses like paints, cables and toys, while there seems to be relatively less focus on genuine import substitution and building globally competitive manufacturing capabilities.
Competition is healthy, of course.
But it would be even more fun to see large capital and capabilities being directed towards reducing our dependence on imports and creating globally competitive Indian businesses.
The first time we appeared in the press was 15 years ago, on September 5th.
I first spoke to @nikhilmw as Sachin, my pseudonym for speaking to clients during sales calls. You didn’t want the CEO making sales calls. 😬 By the way, I’ve even met customers pretending to be Sachin in the early days of Zerodha.
Anyway, one day I got a call and picked it up as Sachin. Turns out it was a journalist from @EconomicTimes, and I was shocked. I had to suddenly switch from Sachin to Nithin. I faked a weird accent so that I wouldn't be recognised. 😬
When this story came out, our account openings suddenly went from a few hundred accounts a month to almost 500. I was convinced I had discovered a growth hack.
Over the next 5–6 years, I spoke to countless journalists, until 2017–18 when the popularity of traditional financial media started declining due to social media and other factors.
That’s when I started posting on Twitter and LinkedIn. Until then, I wasn't that active. If you look at what's been more beneficial for us between traditional media and social media, there's no comparison at all.
The ability to tell your own story directly to the people is powerful. Of course, you need to know how to tell your story well. 😬 If not, you become a meme.
देश के चर्चित मेदांता हॉस्पिटल ने नोएडा में अब ठगी का कारोबार शुरू कर दिया है, जिन्हें धरती पर भगवान का रूप माना जाता है सफेद कोट पहनकर वो डॉक्टर अब ठग बन गए हैं...
नोएडा के सेक्टर -49 थाना क्षेत्र के अंतर्गत सेक्टर -50 में स्थित मेदांता हॉस्पिटल में बीते शुक्रवार को बुखार से पीड़ित एक मरीज को भर्ती कराया गया था..
जब उसने अस्पताल प्रबंधन से खुद को डिस्चार्ज के करने के लिए बोला तो अस्पताल के प्रबंधन ने बोला कि पहले बिल पे करो तब डिस्चार्ज करेंगे और तभी तुम्हे बिल दिखाएंगे।
अस्पताल प्रबंधन को लगा कि मरीज की मेडी क्लेम पॉलिसी है, मरीज के घर वाले पढ़े लिखे होंगे नहीं, बस शुरू हो गए लूट खसोट करने..
मरीज भर्ती था बुखार के लिए और बिल दिया गया पथरी व कोविड के इलाज का, अब मरीज घर वाले पढ़े लिखे थे तो उन्होंने बिल चैक कर लिया..जिसके बाद अस्पताल में हंगामा शुरू हुआ..
देखते ही देखते वहां पर 4 मरीज और आ गाए जिनके बिल में हेराफेरी कर रखी थी..
अब अंगाजा लगाइये कि मेदांता हॉस्पिटल में रोजाना बिलों में हेरा फेरी कर मरीजों को कितने रुपए का चुना लगाया जा रहा है...हिसाब लगाएंगे तो ये आंकड़ा करोड़ों में पहुंचेगा...
सरकार से विनती है कि ऐसे लुटेरे अस्पतालों पर रोक लगाएं..
@PMOIndia@narendramodi@WHO@myogiadityanath@myogioffice@CMOfficeUP@medanta@dmgbnagar@DHSGBN1@MoHFW_INDIA@nhm_up
Samhi is looking at cumulative free cash flow post interest of Rs 3000 Crores in next 5 years
Disc: Own in self and client portfolios. Not a buy or sell recommendation.
Motilal Oswal and Quant AMCs played differently they went for concentrated bets, during down trend their stocks returns were extremely poor. Many of us criticized (incl me), few abused. Investors opt out, they stick to their strategy.
When market reversed, their returns skyrocketed.
Parag Parikh with such a huge AUM, they focused more on downside protection than returns. Hold on to cash, invested in stocks like Coal, ITC, HDFC, ICICI etc, last 1 yr they cannot beat Index.
Interesting to see their strategy in coming months.