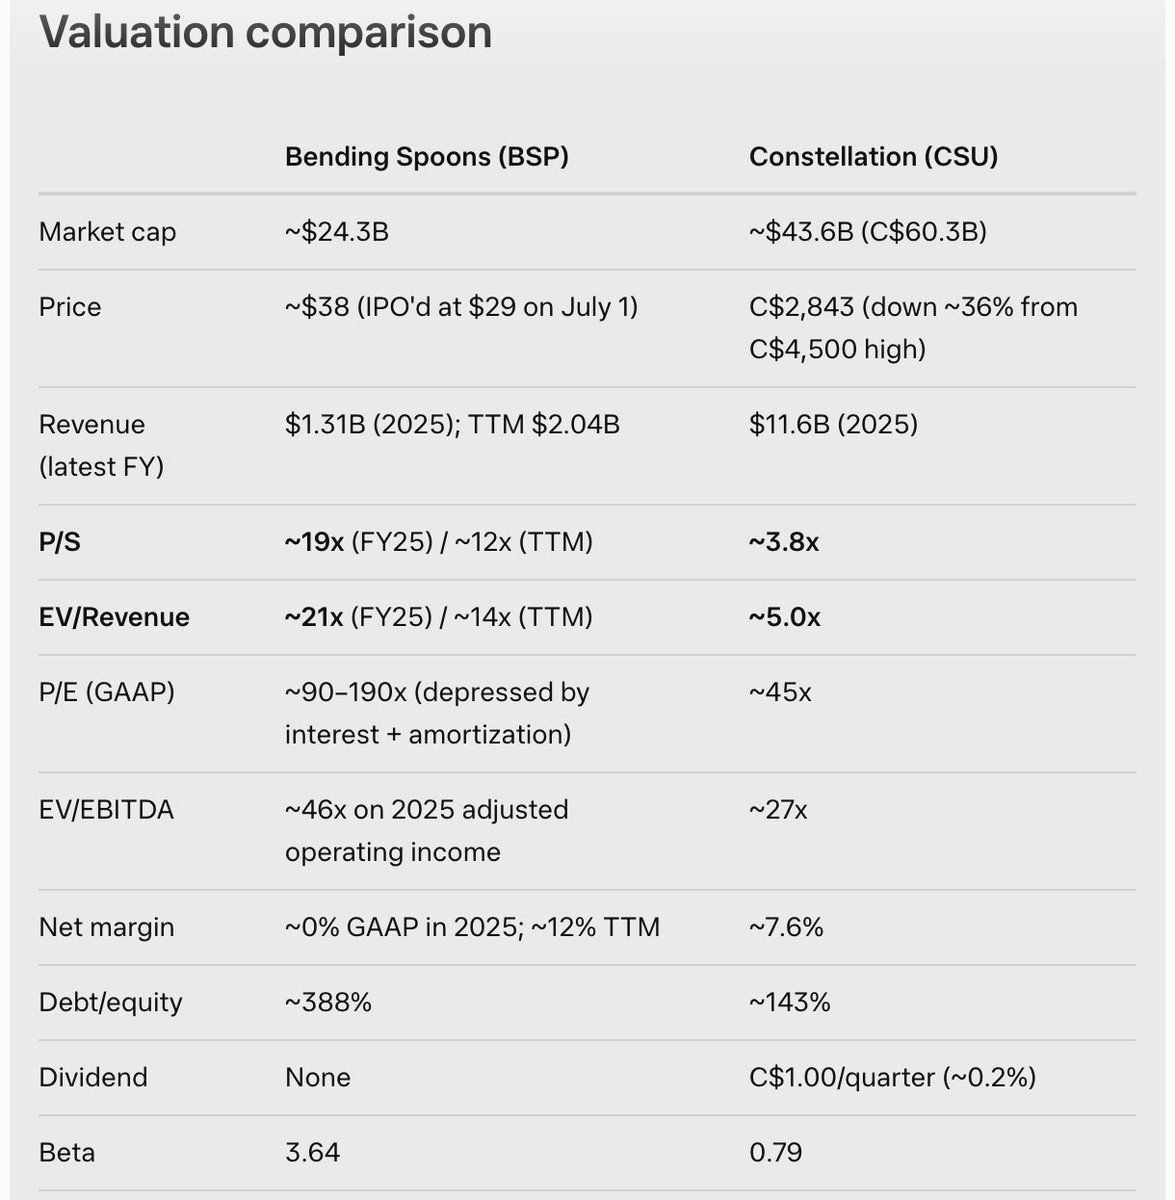
Bending Spoons vs Constellation Software.
Venture folks are sophisticated about venture investments, but they put all acquirers in the same bucket.
Software company acquirers can look very different depending on:
- who they acquire (types of companies)
- how they grow
- how they generate profits
- how they finance acquisitions
- revenue and profit stability
Bending Spoons has completed 50 acquisitions, while Constellation has acquired 1,400 companies.
Bending Spoons is trading at 19x FY25 sales, while Constellation trades at 3.8x.
Bending Spoons is growing at 100%+ with acquisitions, while Constellation is growing at 20%.
But they are both growing 3%-5% organically.
Bending Spoons' organic rate has halved two quarters in a row (13% → 6% → 3%).
Bending Spoons carries roughly 8–10x more debt relative to revenue than Constellation.
Bending Spoons has a much higher net debt-to-revenue ratio at 3.1x, while Constellation is at 0.2x- 0.4x.
For Bending Spoons, interest expense is 11% of revenue, while for Constellation, it's 2.6%.
Constellation can deleverage quickly, while Bending Spoons needs the next deal to pay for the previous deal.
Overall, Bending Spoons' growth is bought on credit.
Each company took a different approach to compounding revenue and cash flows, and the valuations will eventually reflect that.
@gokulr Personally I’d wait to see if this model actually works - feels a bit like copying Groupon. SaaS revenue in these businesses could deteriorate much faster than they expect.
My son Max is raising funds for 2026 Millbrook Baseball and would love your support. You can click here to make your donation - thank you! https://t.co/LMopnRdukU
"Everything is an ad platform."
"You won’t match Amazon with something off the shelf."
@averyj CEO of @kevelapi, predicted the rise of APIs + retail media before it was cool.
We went deep on the future of commerce media—and why differentiation still wins.