$975.HK is a met coal company down 30% YTD when the price of the product it sell is up 30% (their own sales prices dot-plotted in latest release on Friday). Sure there's been some cost increases.. but...
Thermal coal is even wilder.. the stocks are flat to down.. the commodity is up 30-40% and the commodity relatively is about 50% cheaper than the alternative.. 🤔🤔
This is a fantastic analysis only I think too conservative.. 😉.. a decent slice of LNG is at spot JKM (US$26/mmbtu) ..
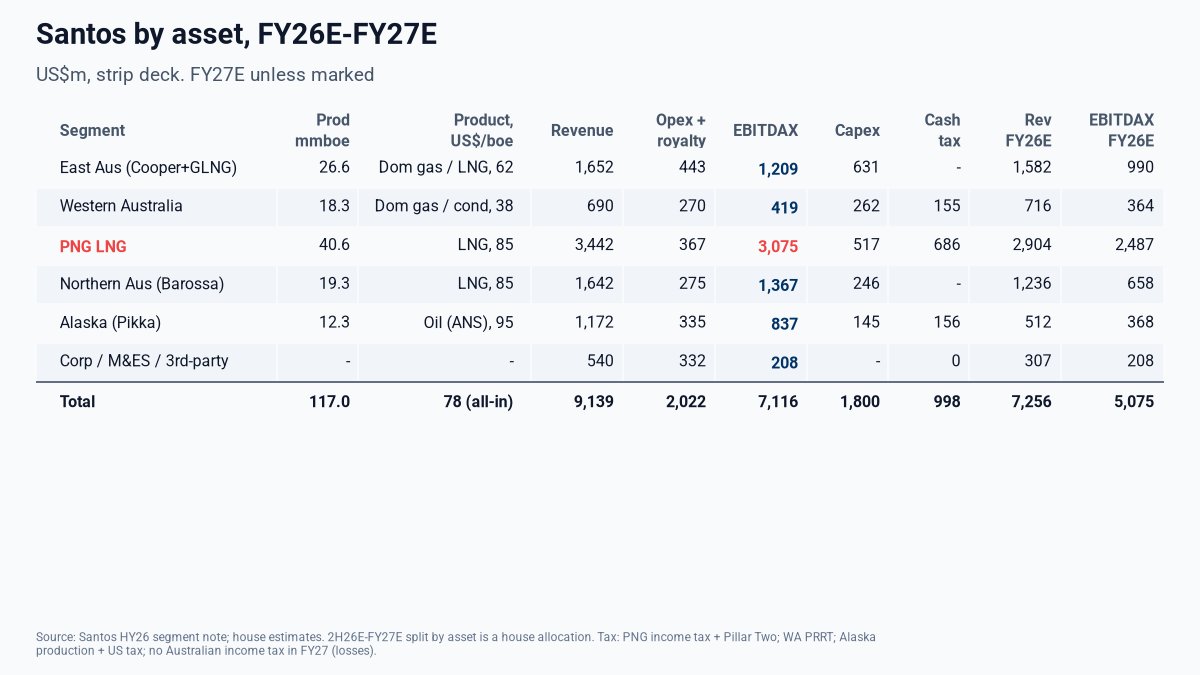
Revenue at US$10bn and opex+capex at US$4bn = US$6bn PBT for a US$20bn company (with multi-decade operations).
And for those concerned about Albo.. PNG + Alaska = ~50% of the revenue and ~80% of the profits..
$STO.AX
Show me a better risk/reward trade today than thermal coal miners.. Russia, Indonesia & China have production issues, India (and Europe) have inventory issues.. and gas is trading at like >US$300/t Newcastle equivalent.
Meanwhile at US$150/t Newcastle the miners trade at 2-3x EBITDA with multi decade mine lives (likely pricing in US$120/t NEWC)... 🤔🤔
The financial market ignores both China Rare Earths and Baosteel decided to raise prices in rare earth concentrates starting Q4 26 - while only up 0.53% from Q3, it was actually up 48% yoy....it sends signals that the Chinese REE leaders have set floor price for the minerals
Since all the damn Aussies love $STO.AX, I sat down to model it properly .
Fair warning: this thing is not easy to model. But you don't need a perfect model to see they're going to come in well above the street. The LNG price lag basically hands you the next two quarters.
First of all oil and gas disclosure is rubbish next to mining, and that's an industry problem. Santos is well run and better than most. You get reserves, guidance, realised prices by product and even a slide on their premiums. What you don't get is field by-field costs, decline curves or LNG contract slopes. So you rebuild it yourself from the quarterlies. Could be better! So what we need here is a BRE-X style event to force some standards.
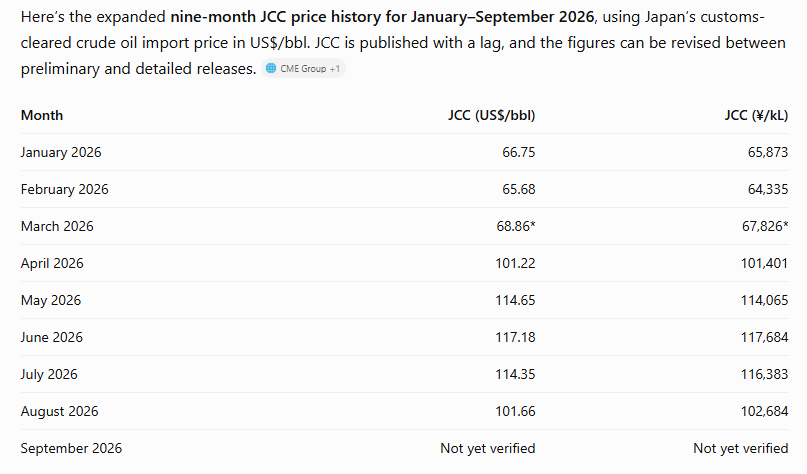
Anyways, onto $STO.AX, Most of their LNG is priced off JCC, the Japanese crude cocktail, from about 3 months earlier, and the cocktail itself trails Brent.
Fitted to Santos' own numbers, realised LNG comes out at ~14.45% of the lagged cocktail. This is 60% of total revs ish.
The odd one is Q2-26. On their usual formula (~14.45% of the cocktail from 3 months earlier), a US$67 cocktail, the lowest since 2022, should give about US$9.70/mmBtu. That would have been down on Q1's US$10.30.
Instead the oil-linked contracts printed US$10.87, and the overall LNG price went up 4.9% to US$11.21. That works out to a 16.2% slope, well above every other quarter. Management said it was achieved "despite" the low price and never explained why.
A 3-month lag can't push the price up when its input falls. So either some contracts pick up newer prices or the terms changed. My guess is in their own wording: the "majority" of contracts are on a 3-month lag, not all of them.
The cocktail jumped from ~US$69 to US$101–115 in April–May, so if ~25% of volume is on a 1-month lag, that explains it.
Anyways, because of the lag, we already know the next two quarters with pretty good accuracy.
Q326 is priced off the April–June cocktail (101/115/117).
Q426 is priced off July–September (114/102/~100),
which has already printed. Q1-27 is two-thirds set by Brent that has already traded!
That gives realised LNG of ~US$16/mmBtu in Q3 and ~US$15 in Q4, vs US$10.95 in 1H26 which gives us a
Q4-26 EBITDAX: ~US$1.76bn, 11% above the street's run-rate. For Q1-27 we get EBITDAX: ~US$1.98bn vs the street at ~US$1.17bn, +69%.
This is very simple math on prices that have printed.
Premiums
Santos' liquids are selling well over Brent right now: ~+US$8/bbl YTD and over +US$20 currently, with Pikka crude and LPG at a premium too. History says that's a spike, since the 2016–25 average was ~+US$1.30. So I keep the juice for FY26 and fade it through 2027.
Domestic gas is the boring bit, at ~US$5.60/GJ on old contracts well below today's A$10–12.
Tax, who doesn't love (not) paying tax. Santos pays basically no Australian income tax. It has ~US$2.5bn of carried-forward losses plus US$5.7bn of PRRT credits it hasn't booked, so nearly all of its cash tax goes to PNG. The losses run out around late 2027.
Vs the street
FY26: I get EBITDAX of ~US$5.1bn vs the street at ~US$4.7bn, ~8% above. Most of the gap is Q4, which is already priced.
FY27: this is where it gets silly. On today's oil strip I get revenue of ~US$9.1bn. The 11 analysts on Yahoo average ~US$7.0bn, and the most bullish is at US$7.8bn. Barossa and Pikka add ~15% more volume and Brent is ~US$103!!! Nobody's even close.
The next two quarters are about as close to known as this sector gets, and they're well above consensus. Estimates have to come up, for the quarters and for FY27.
Santos is basically telling you the same thing. In the last quarterly they said JCC above US$100 "is expected to drive higher realised LNG pricing and cash flow in the third quarter", and that 2H production would be up 20–30% on 1H. They added that ~US$300m of cargo cash slipped past 30 June, a PNG under-lift reverses in 2H, and a ~US$200m gas prepayment landed on 1 July. 1H26 was the low point, with the projects still costing money and LNG priced off a US$67 cocktail.
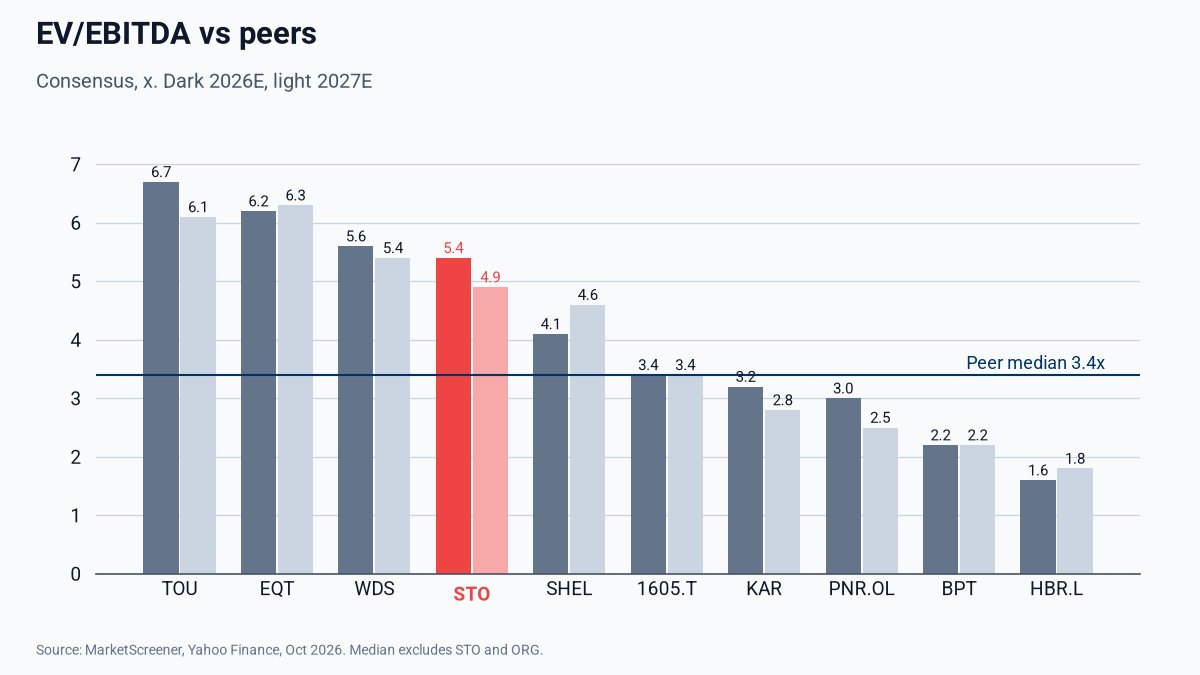
It screens relatively expensive at ~5.4x EV/EBITDA against my random peer group, but that's a timing thing. The EV carries the debt from building Barossa and Pikka, while the EBITDA doesn't include them yet. With both now producing, it drops to ~3.4x in FY27 on the strip.
The first test is the Q3 result in late October: LNG at ~US$16, revenue of ~US$2.3bn and Barossa near full rate. Then 2027 guidance at the investor day. The prices are already locked in, the projects are running, and the company is saying it out loud. The only ones who haven't caught on yet are the analysts.
Not advice, DYOR.
🇨🇳 China's coal prices hit a three-year high 🇨🇳
⛏️ This is driven by sluggish domestic production growth and disruptions to top exporter Indonesia, just as winter demand is set to rise
📈 Benchmark coal prices hit 1,004 yuan a ton ($150) on Monday
https://t.co/X3jbVeXiBJ
Santos $STO.AX contracts work on a 3-month LAG to the JCC price (Japanese Crude Cocktail).. you can do the work on what 1H26 looked like and what 2H26 looks like below.. and those dumbass algo's will no doubt run up earnings momentum.. I don't pump stocks but @costanzakapital says this is full send.. 🚀
Anyone got good AI exposure in microcaps to pitch? My best one is $FTEK but looking for more.
Most good ideas to me are 5-15Bn market cap right now.
$NNBR $MEC interesting candidates but outside of that not finding much.
If you ever viewed the below tweet you know what happened next.
Below is my view on the #coal players today.. (don't dare mention that shitco).
Either the market is right in its valuation and the spot coal price reverses meaningfully or the equities go higher.. I don't know which one happens..
I'm always long 25 year++ Assets trading at 2-3x EBITDA.
Received a lot of hate for posting this at the time.
I'm wrong a lot, and will probably be wrong here.
But we're not far from $4,000.
Ideally we'd test $3,800/oz.
Imagine the bargains on the miners if we got there.