A letter of intent and a term sheet are often confused because both serve as pre-deal agreements, but they do very different work in an acquisition or business sale.
A letter of intent is a non-binding document that comes earlier in the process.
It signals serious intent from a buyer and typically outlines the basic framework: purchase price, structure (asset deal or stock deal), timeline, and any major conditions.
Think of it as a mutual agreement that both sides want to move forward, but with escape hatches built in.
Most LOIs explicitly state they are non-binding except for confidentiality, exclusivity, and expense clauses.
A seller benefits because it narrows the field of potential buyers and shows the buyer's financial and strategic seriousness.
A buyer benefits because it protects them during due diligence, before they've spent months reviewing financial records, customer contracts, and liabilities.
A term sheet comes later, typically after due diligence has begun or wrapped up.
It's more detailed and binding in many respects.
A term sheet might specify working capital targets, earnout structures, representation and warranties insurance, indemnification thresholds, escrow amounts, and other closing mechanics.
Both parties have deeper information now, so the term sheet reflects actual deal anatomy rather than preliminary intent.
Here's where confusion happens: sometimes a buyer and seller use "LOI" to mean everything pre-closing, and sometimes they skip a formal LOI altogether and move straight to a term sheet.
This varies by deal size, advisor involvement, and market norms.
A smaller add-on acquisition might just use a term sheet.
A larger deal or one with significant risk (carve-outs, complex earnout structures) typically benefits from an LOI first, which lets both sides align on fundamentals before the term sheet locks in details.
A businses owner selling, buying, or raising capital must master the balance sheet.
Assets equal liabilities puls equity.
Buyers will scrutinize curernt versus non-current assets, working capital cushion, debt-to-equity ratios, intangible asset valuations, etc.
most business owners don't understand synergies in an acquisition.
they see the acquisition price and move on.
they miss the real value creation.
synergies show up in three places.
reduced cost of goods sold when you combine operations.
gross margin expansion from scale or eliminating duplicate functions.
and enterprise value multiplication because the combined business generates more cash than either alone.
America’s largest grocery store should be out of business.
Jungle Jim’s.
Fairfield, Ohio.
Monorail out front.
He bought it for a dollar.
Put two and a half million into it.
“That’s the kind of crazy shit I do.”
814-pound cheese.
Kangaroo. Yak. Wild boar.
1.5 acres of produce.
18,000 wines.
Never touched a computer.
“This place talks to me.”
most entrepreneurs are taught to think about business in layers.
You've got revenue, profit margin, cash flow, customer acquisition cost, lifetime value.
All useful metrics.
But there's a distinction that changes how a founder actually runs things day to day, and it shows up clearly when someone tries to sell the business.
The difference between a business and a job.
A business generates revenue because systems and people create value independently of the owner's time.
A job is something the owner performs.
Practically, this looks like revenue that continues whether or not the founder is in the room.
A founder might have $2M in annual revenue but if they're the only one closing deals, the only one delivering the service, or the only one holding relationships together, they're running a job.
The business stops if they stop.
When a buyer runs the numbers, they see this immediately.
They're not buying revenue, they're buying dependency on one person.
That's not a business for sale, it's a wage replacement that's now their problem.
Compare that to a founder who built the same $2M in revenue but systematized cilent acquisition, hired people who can deliver, and stepped back from the day-to-day work.
Same top line, completely different asset.
A buyer sees a business that runs without them.
This distinction matters early, not just at exit.
A founder building systems and delegation early compounds over time.
They have more breathing room, can actually think strategically instead of working in the business, and the foundation for scale is already there.
A founder grinding to deliver client work personally is stuck until they change structure.
More revenue doesn't fix this.
It just makes the workload heavier.
The systems and the people are what turn a job into a business.
A business owner watched revenue climb while cash flow tightened.
at 8% monthly churn, they'd lose 60% of customers yearly.
an audit revealed the problem: weak onboarding left customers stuck at friction points.
after rebuilding the experience and adding day-14 outreach, churn dropped to 3%.
fix your customer experiences please
A KPI connects a number to a decision.
A metric is just a number.
Revenue is a metric.
Revenue growth rate relative to customer acquisition cost is a KPI, because it tells you whether you're building a sustainable business or burning cash to buy sales.
Website traffic is a metric.
Conversion rate per traffic source is a KPI, because it shows which channels create buyers and which create noise.
In M&A, a seller might tout total addressable market, monthly recurring revenue, and customer count.
A buyer hunts for KPIs: customer acquisition cost, churn rate, gross margin trend, cash conversion cycle.
warren buffett's step down from berkshire hathaway raises a question for business owners eyeing acquisitions or exits...what's the actual value of a business when the leader departs?
the answer depends on how much of your competitive advantage lives inside your head versus embedded in operations.
start by auditing your core competency.
can someone describe in detail how your business actually wins?
if the only answer is "because i'm good at it," that's a problem.
document the repeatable processes.
train others on them.
prove the advantage survives without you present.
next, examine your unit economics hard.
buffett targets businesses with durable competitive advantages specifically because they show stable, predictable margins.
a buyer will stress test your cogs and working capital assumptions against different leadership scenarios.
if your numbers only work because you're personally managing something, they tighten their offer or walk.
build a balance sheet that stands alone.
buyers analyze earnouts based on whether future cash flows depend on your continued involvement.
remove that dependency through systems, key hires, and documented workflows.
agentic workflows that handle routine decisions reduce the risk profile.
consider how bolt-on acquisitions might strengthen your position in advance of a sale.
buyers pay valuation multiples partly on the strength of your moat.
owning adjacent capabilities or customer relationships makes that moat wider and harder to replicate.
run a due diligence process on your own business as a buyer would.
stress your assumptions.
find the gaps.
fix them while you still control the outcome.
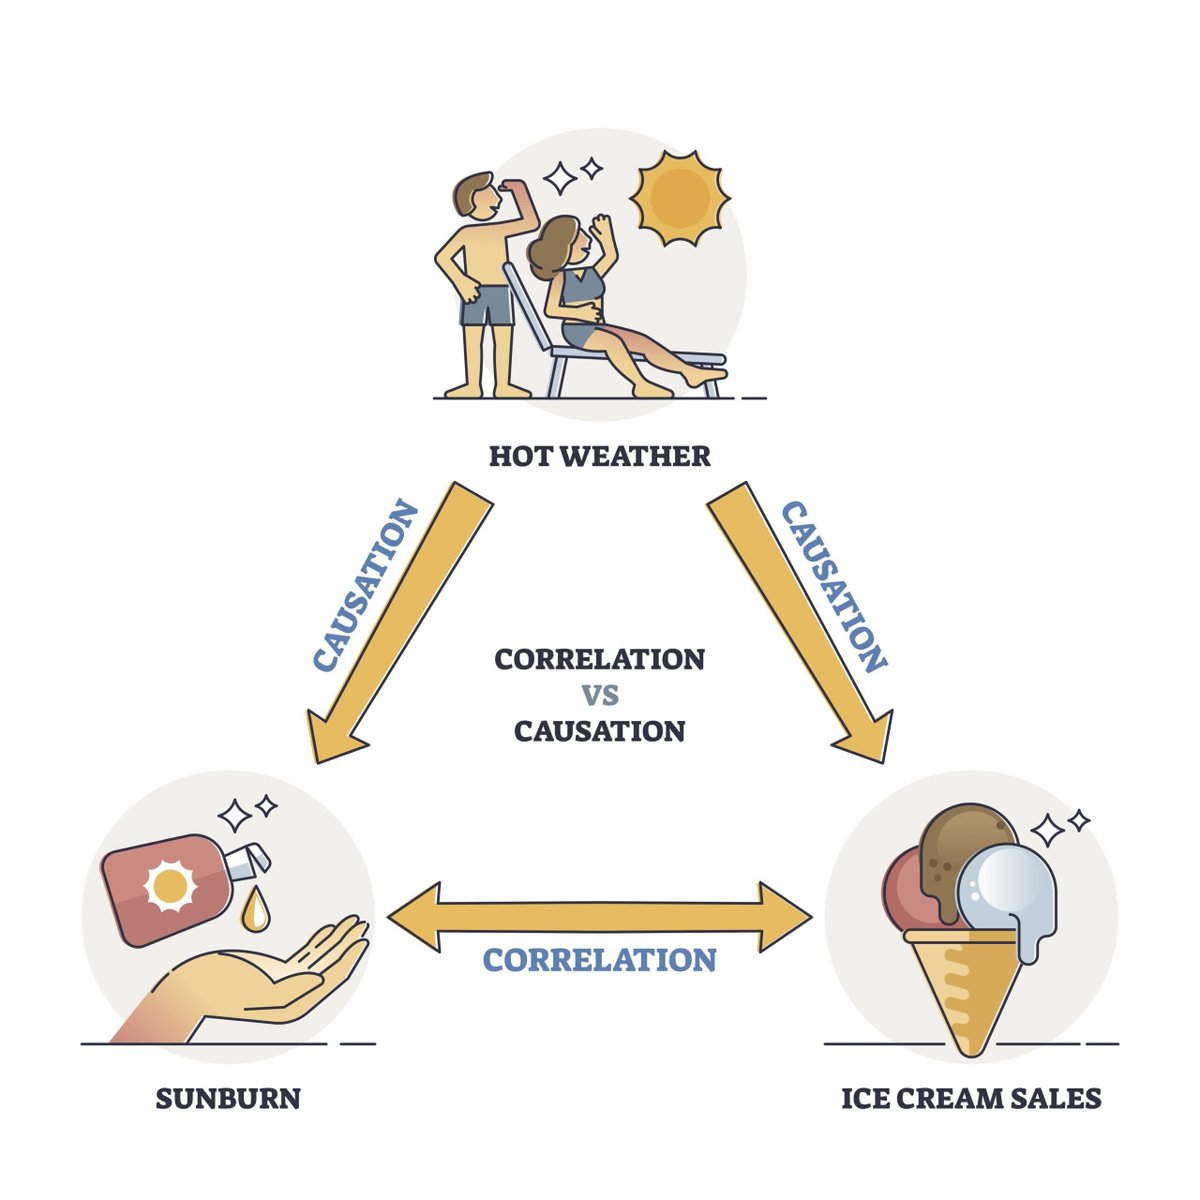
One of the hardest lessons in M&A is understanding the difference between correlation and causation in deal synergies.
A private equity firm acquires a business in a booming industry.
The company grows 40% in year one.
The GP takes credit for operational improvements, marketing strategy, new hires.
But here's the reality: the entire sector expanded 35% that year.
The buyer's actual value creation was probably closer to 5%, hidden in the noise of market tailwinds.
This matters because it distorts how you evaluate past deals, how you price new ones, and what you actually learn from your playbook.
When assessing an acquisition candidate, strip out the macro effects.
If the seller's growth came from a rising tide (bull market, supply shortage, regulatory shift), that competitive advantage disappears when conditions normalize.
A founder who crushed it during a growth phase might struggle the moment headwinds hit.
You need to isolate what the management team itself moved the needle on.
The same principle applies to synergy assumptions.
A buyer estimates 20% cost reductions by consolidating operations.
But if two thirds of that comes from "we'll cut duplicative overhead," and that's only possible because the combined entity reaches new economies of scale that only exist in a hot economy, you're betting on conditions staying favorable forever.
The best operators separate what they control from what the environment hands them for free.
A colleague at a PE firm spent weeks analyzing a target's historical margins.
They discovered that 60% of the improvement over five years came from falling input costs, not better management.
The margin profile was less attractive than it appeared.
They passed on the deal.
When you can spot the difference between a manager who built something strong and a manager who rode a wave, you start making acquisitions you actually know how to improve.
Enterprise value is what a business is actually worth on the market.
It's the total price a buyer would pay to own the whole thing, and it's calculated by adding together the company's market value of equity, its total debt, and subtracting any cash on hand.
The math looks like this: Market cap + Total Debt - Cash = Enterprise Value.
Why does this distinction matter?
Because a business owner looking at their company's market cap might see a number and think that's the full valuation.
But that's only part of the story.
If a business has $10 million in equity value but also carries $5 million in debt, the enterprise value is actually $15 million.
A buyer isn't just acquiring the equity; they're taking on the obligation to service or pay off that debt.
Cash works in reverse.
If that same business has $2 million in the bank, the enterprise value drops to $13 million because a buyer can use that cash to pay down debt or run the business.
This matters in M&A because different buyers care about different pieces.
A private equity firm buying a business for a leveraged buyout is intensely focused on enterprise value, not just equity value, because they're calculating how much debt they can load onto the deal and how the cash flow will service it.
A strategic buyer might weight things differently depending on whether they're buying just the operating business or taking on its financial structure as-is.
When you see a valuation multiple quoted in the market, it's almost always expressed as a multiple of enterprise value, not equity value.
A business trading at 6x EBITDA means the enterprise value is six times the annual earnings before interest, taxes, depreciation, and amortization.
That's the true economic price of control.
Understanding enterprise value prevents a dangerous mental error: confusing what the equity is worth with what the business costs to acquire.
They're related but not the same.
The equity is what an owner has left after all debts are paid.
The enterprise value is what a buyer needs to pay to own the whole operation, debts and all.
A business owner bought a software company, ran thorough due diligence, closed the deal.
three days later, a customer revealed an $200,000 billing error the seller had buried.
Tough luck.
That's why R&W insurance may be a good idea.
R&W (Representations and Warranties) insurance is a specialized type of transactional laibility coverage in M&A to protect buyers or sellers from financial losses caused by a breach of the statements made about the acquired company
It covers discovery failures so buyers don't chase sellers through.