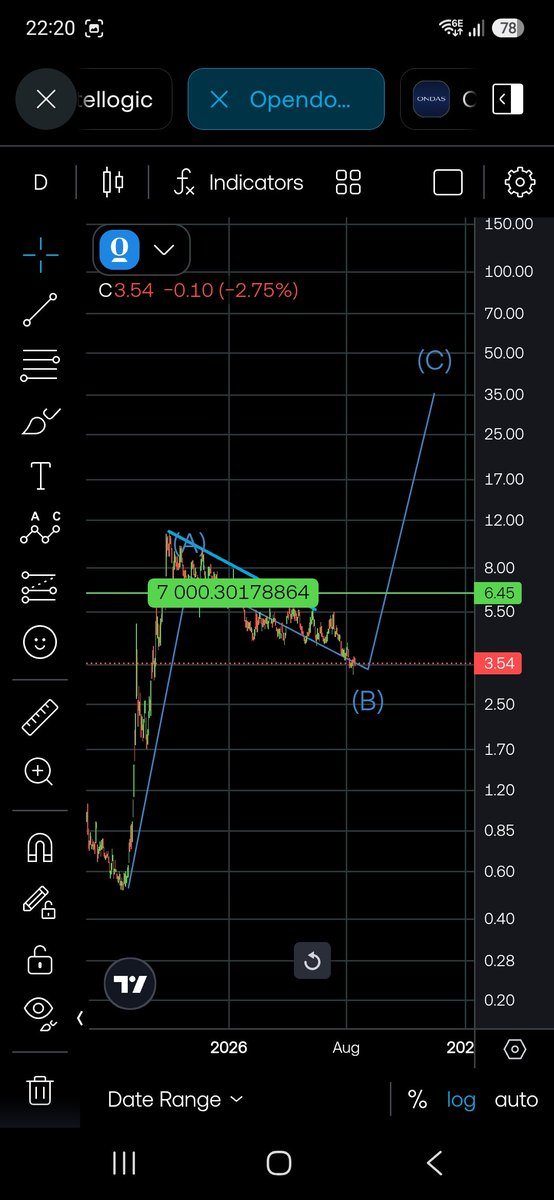
@Nbusiness1990 I feel exactly the same. I dont mind bag holding...its just numbers on a screen right.....the main thing that has annoyed me that ive missed out on so many other opportunities and great set ups over the past 6 months having money tied up in $OPEN
$OPEN The biggest winner from this compensation package could ultimately be shareholders—not the CEO.
Instead of paying Kaz Nejatian a massive guaranteed salary, Opendoor is tying almost all of his potential wealth to one thing: creating long-term shareholder value. His $741 million stock award only becomes truly valuable if the company’s market value increases significantly over the coming years. In other words, if investors don’t make money, neither does the CEO.
This creates one of the strongest alignment structures possible. Rather than focusing on quarterly earnings or short-term stock movements, management is incentivized to build a stronger business that can compound value over many years. That could mean improving profitability, growing market share, strengthening technology, and making smarter capital allocation decisions instead of chasing short-term results.
For existing shareholders, this reduces a common concern in corporate America—executives getting paid regardless of company performance. Here, the CEO’s financial future rises and falls alongside investors. If the stock doubles or triples because the business executes successfully, shareholders benefit first before management earns its largest rewards.
The package could also help Opendoor attract and retain top executive talent without placing immediate pressure on cash flow. Instead of spending hundreds of millions of dollars in guaranteed cash compensation, the company preserves capital to invest in technology, AI, operations, and future growth. For a company still working toward long-term profitability, conserving cash while aligning incentives can be a significant strategic advantage.
The message to Wall Street is equally important. By offering a Tesla-style performance package, Opendoor’s board is signaling confidence that the company still has substantial upside despite recent challenges. They’re effectively saying they believe the business has the potential to become many times larger than it is today—and they’re willing to reward management only if that vision becomes reality.
Of course, this isn’t a guarantee of success. Opendoor still faces headwinds from higher interest rates, a challenging housing market, and ongoing questions about the sustainability of its business model. A performance-based pay package cannot solve those issues by itself. Ultimately, execution will determine whether shareholders realize those gains.
If management delivers, everyone wins. Shareholders benefit from a higher stock price, the company builds long-term value, employees gain confidence in the strategy, and the CEO earns his compensation by creating wealth rather than simply receiving it. That’s why many investors view these performance-driven compensation plans as a more shareholder-friendly approach than traditional executive pay packages.
I shared this note earlier today with the entire team at Opendoor.
Today we began to say goodbye to our colleagues in India as we wind down our India operations.
Our customers are in America, and that's where our operational work belongs.
This Homeownership Month, President Trump and @HUDgov are delivering REAL solutions to restore affordable homeownership and bring the American Dream back within reach. 🇺🇸
🏡 Slashing bureaucratic red tape
🏡 Homebuilding innovation
🏡 Mortgage accessibility
Perfect analysis of $OPEN
The only thing I would add is the chart structure 7 month bullish channel, looking for wave 3 up to (IMO) $25 in the first instance
Increased my $OPEN position again today. Now around 15-16% of my portfolio and looking to get it to 20-25% over time.
The more I dig into this company the more convicted I become. The reasons are simple:
→ A CEO who left Shopify because he saw a generational opportunity and is executing at an absurd pace
→ An engineering team he says he'd put up against any company in tech, not just real estate
→ Insiders buying with their own money at these prices
→ Cohort margins at 6%+, best in company history
→ Acquisitions ramping from 120/week to 655/week in 8 months
→ Aged inventory crushed from 51% to 10%
→ EBITDA breakeven guided for Q2, net income positive by Q4
→ Mortgage expanding to 40 states by Q3
→ 100,000+ agents now integrated via RealScout
Every metric I track quarter over quarter is moving in the right direction. Contribution margins improving. Acquisitions climbing. Sales accelerating. Costs declining.
This company is reinventing how people buy and sell homes. We are only at 0.7% US market share.
This is the beginning.
Will increase dramatically once my compute positions play out.
nfa, long $OPEN 🏠
🚨 $OPEN is the most mispriced AI turnaround on the market right now.
The future-focused thesis retail isn't sizing yet:
🎯 THE INFLECTION ARRIVING THIS QUARTER:
✅ Adjusted EBITDA BREAKEVEN targeted Q2 2026 (NOW)
✅ Q2 revenue growth ~25% QoQ (management guided)
✅ Contribution Margin 5-7% target range
✅ "Profitable on 12-month go-forward basis as of April 1" — CEO
⚙️ THE OPERATING LEVERAGE COMING:
✅ AI-first "Opendoor 2.0" model = scalable margins
✅ Each new cohort structurally improving
✅ Best margin/stability/velocity in company history (ex-COVID)
✅ Aged inventory cleared = pricing discipline locked in
📈 THE MACRO TAILWIND ACTIVATING:
✅ Housing sentiment improving
✅ iBuyer market structurally repositioned
✅ Rate pivot optionality 2026
✅ AI-first captures disproportionate share when volume returns
🏦 THE INSTITUTIONAL CONVICTION SIGNAL:
✅ New CEO Kaz Nejatian bought 100,000 shares May 11 at $4.88
✅ Personal capital deployed: ~$488K
✅ 225,000 shares bought past year. ZERO sells.
✅ CEO direct ownership: 83.5M+ shares
✅ Alliance Global initiated BUY, $8 PT
🔮 THE FORWARD CATALYST STACK:
→ Q2 earnings: EBITDA breakeven proof
→ Adj Net Income positive (12-month forward by EOY 2026)
→ Housing volume normalization 2026-2027
→ Cohort compounding
→ AI operating leverage materializing
→ Potential Fed pivot late 2026
🛡️ THE STRUCTURAL POSITIONING:
$999M cash. Cleaner inventory. AI-first model. New CEO. EBITDA breakeven this quarter. Multi-year operating leverage ahead.
This isn't a recovery story.
This is the inflection BEFORE retail recognizes the trajectory.
The market is pricing the historical $OPEN 🔥
The trajectory is pointing somewhere completely different.