airline miles are a genius marketing trick to hide the fact that you're receiving very low cashback
monetary value of a mile is like $0.01
if you get 1 mile per $1 spent you're earning 1% cashback
cashback caps are now easy to track in the rewards section
after a lot of improvements on the core flows like kyc & onboarding we’re now shipping all the small quality of life improvements
let me know what else you want to see and i’ll make sure we ship it
We have been cooking with @openinterest_hq. Stay tuned for interviews with the best in the industry. Here's a teaser from the one with @litocoen, who leads GTM at @ethenapay.
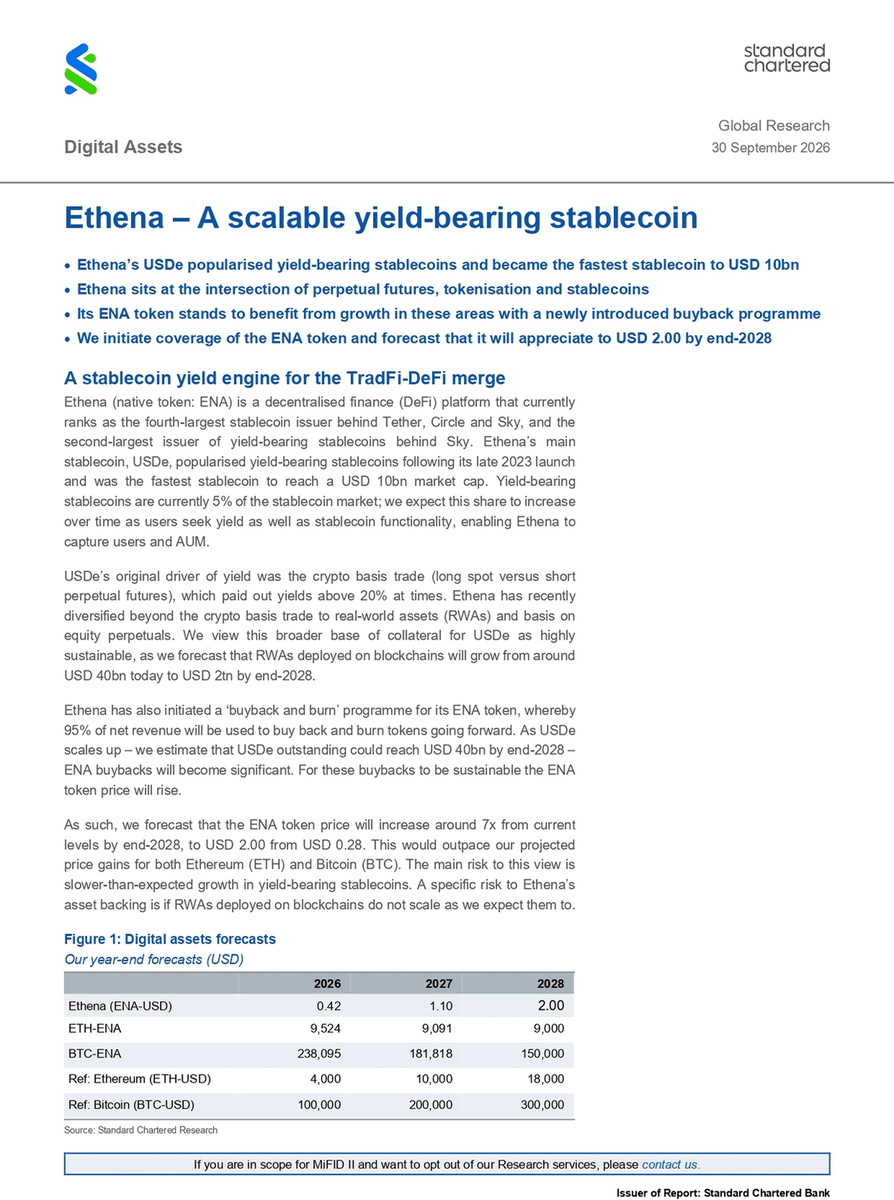
Standard Chartered has initiated research coverage of Ethena.
They forecast potential USDe growth of ~8x in the next 2 years as the convergence of DeFi and TradFi accelerates.
Unclear why they are so bearish, but worth a read regardless:
We just raised the Daily Boost caps.
Pro members now earn up to 6% on their first $100,000, and VIP members on their first $1,000,000 - up from $15,000 and $50,000.
Balances above the caps still earn the 4.5% base rate by default.
Always be earning.
the UX of depositing and earning *automatically* without having to deposit into a separate Earn vault is so slick and different from legacy banking apps.
Introducing @EthenaPay: the internet money neobank.
→Card spend cashback at 5.0%
→Best-in-class 6.0% dollar savings rate
→Borderless, free, instant global money transfers
→Free global onramps in USD, GBP, EUR and local FX
→Multi-currency high-rewards savings accounts in local FX
→Unified fiat IBAN integration with self-custodial stablecoin accounts
→Buy Now Pay Never where your savings rewards covers daily expenses
Not coming soon™️. Live now to download on iOS.
The growth of equity and commodity linked perpetuals has been the most exciting development in the space in the last year, with RWA perpetuals already growing to >50% of Hyperliquid crypto volumes last month, and aggregate Binance RWA volume at 2x BTC-USDT last month.
High conviction view that this is one of the very few 100x left in the space, and I expect both open interest and volume to exceed crypto perpetuals across all venues within the next ~24 months.
For Ethena this is the most exciting opportunity since we started: effectively expanding the underlying asset base from ~$2.5tn of crypto to >$120tn of equities. USDe peaked at ~$15b on crypto alone and we expect by the end of this next cycle the opportunity here will unlock scaling to a multiple of that number.
While we would have liked to do this earlier, we took a cautious approach to what was a nascent market and waited until we saw deep, liquid markets with a data history we could study before moving into the opportunity at scale.
Over the next weeks we will begin deployments into equity basis across the venues where we already execute crypto basis with the same battled tested infrastructure used to date.
Become more clear this cycle that the very best businesses in crypto aren't just levered to the crypto cycle but can be flexible enough to reposition their businesses every 4 years when crypto is in the gutter.
Going forward the growth and through-the-cycle resilience of Ethena will be tied more closely to basis on these markets rather than crypto alone.
A lot of people reached out asking about paid integrations, how protocols can even compete, and what the growth perspectives are for Fluid in this case. Here are some thoughts: Paying for integrations and exclusivity is simply part of growth strategy and business development. That's completely normal. A lot of people just do not know about this and think that eg Morpho is getting all integrations by default. Morpho has a very strong backing and an excellent BD team, but they won't be able to pay for every integration forever. There is also the question of alignment between partners.
Eg the Coinbase deal reportedly cost ~7x less than the Robinhood deal, yet Coinbase accounts for more than 60% of Morpho's TVL and has been a major contributor to $morpho becoming the highest-valued lending protocol. This high valuation helped to finance the deal with Robinhood, which is a direct competitor to Coinbase. CB is well known for their negotiating skills, so it'll be interesting to see what happens when they revisit that relationship.
I also agree with what @euler_mab said about tokens. A new token can open many doors. Like Euler, we chose not to launch with a new token and instead continued with the token from the previous protocol from 2021. That decision came with limitations, but when one opportunity closes, others emerge.
That said, I think it is too early and naive to think that there is a clear winner among lending markets and I am very excited about @0xfluid future.
But how can Fluid or other lending markets navigate in this space, which has turned into enterprise sales controlled by suits? First of all, the world is pretty big. There are thousands of banks, funds, fintechs with trillions of dollars in AUM. The pie is large enough for multiple winners.
Second, Fluid has a fundamentally superior architecture, and I know that matters to sophisticated integration partners. Instead of integrating separate lending markets, DEXes, and other financial primitives, partners can integrate once and access everything through a single stack while working with one team.
On top of that, Fluid is the only protocol with equivalent deployments across EVM, Solana, and soon Sui - three different VM ecosystems. (And what if I told you there are more VMs to come?)
Powered by Fluid We have had great success with our first distribution partner - @jup_lend powered by Fluid. A $2B TVL protocol with plenty of growth ahead.
We'll be launching additional white-label deployments with traditional asset managers, exchanges, neobanks, and other partners in the near future.
We don't have the luxury of paying for every integration, but we can win partners through better technology, white-glove support, and predictable economics instead of fee switches or curator fees that can be turned on at any time.
DEX v2 - it is a shame that we keep delaying it despite announcing it a year ago, but we have it ready and we will launch it sooner rather than later.
DEXes generate roughly 16x more fees per $1 of TVL than lending markets, so this will be a major focus for us this year.
There are plenty of other things I'd love to share, but every time I do, another market-wide armageddon seems to happen, forcing us to delay or reprioritize launches.
So this time, let's just wait for the launches themselves.
Stay Fluid 🌊
Excited to announce our collaboration with @Blackrock.
→Integration of USDe into BlackRock's Aladdin platform
→BUIDL as the primary asset for our whitelabel product
→Liquidity facility on BlackRock tokenized products
The integration of USDe on Aladdin provides unique institutional access for the >$20 trillion of assets managed by financial institutions on Aladdin.
StablecoinX Inc. @stablecoin_x is now trading on Nasdaq Global Market under the ticker "USDE".
As the first treasury company focusing on Ethena, StablecoinX gives public-market investors direct access to the most important emerging trend in all of finance: the secular growth of digital dollars.
a lot of crypto cards and neobanks advertise 0 FX fees
what they actually mean is that they are not *adding* any additional FX fees to the one already charged by Visa/Mastercard
to date, every crypto neobank piggybacks on the FX infrastructure provided by Visa & Mastercard
if a user has a USD card and spends in 🇧🇷Brazil, the merchant gets $BRL and the exchange is handled by Visa
to really get 0 FX you would need to receive the so called "interbank rate" which is the rate at which banks exchange currencies between one another and what you see on online currency converters like XE
the only way to get close to this and offer a more competitive rate is to build an FX engine in-house which is what players like Revolut and Wise have done but it involves complex treasury management and operations
in a nutshell they hold pools of different currencies on their balance sheet and when a user swaps e.g USD to EUR it's just an internal swap in their treasury
they can then settle with Visa/Mastercard directly in the merchant currency and avoid the markup for the user
but to avoid the FX risk that comes with holding multiple currencies on their balance sheet they need to hedge via forward contracts and try to net flows to hold as little float as possible
this is why they mostly only offer major currencies and not the more exotic ones because the cost of hedging, ops and lack of bi-directional flows makes it too costly
and even on major currencies the 0 FX amount is capped to $1000/month for most users
i think there's a real opportunity to move FX markets on-chain and let every neobank large or small tap into wholesale liquidity
0 FX for every user worldwide with no amount caps is how crypto neobanks become significantly better than their tradfi counterparts