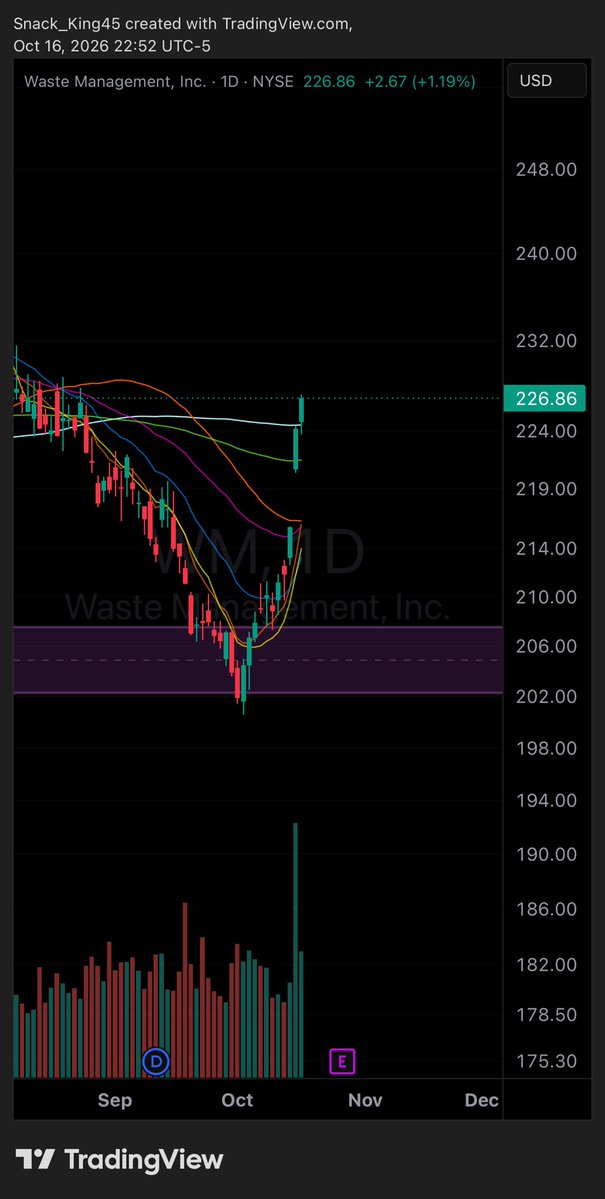
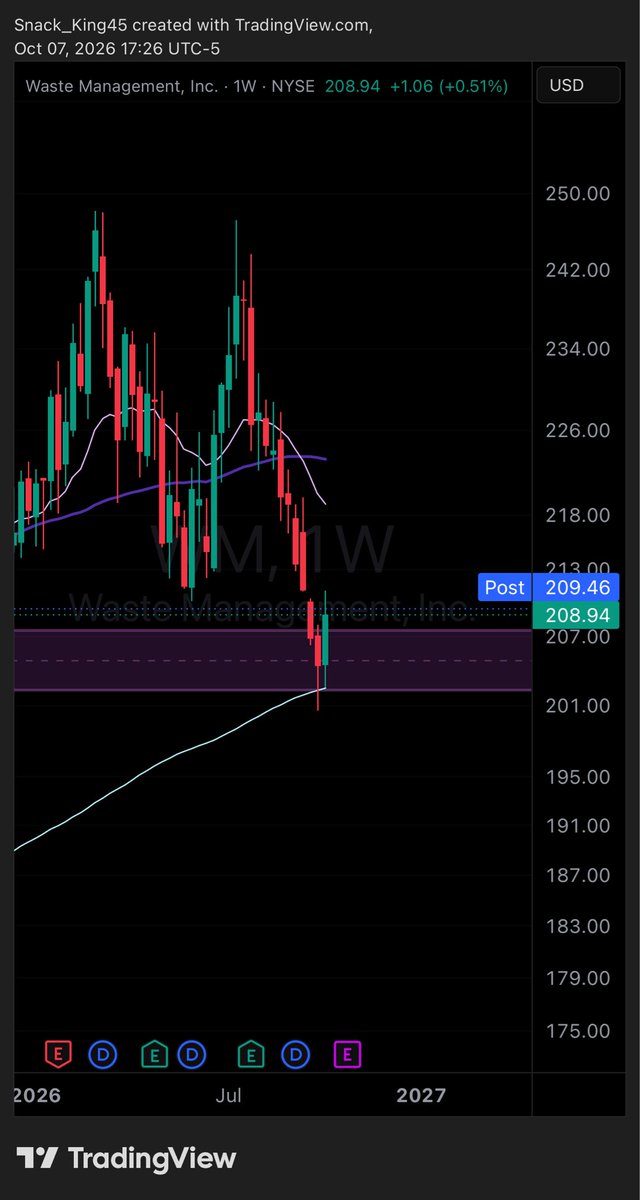
Update on $WM since I started some defensive positions.
Some busted my balls for this call.
I don’t see anyone in the fin community talking about how to build a true portfolio.
I think there is a strong argument to be made on both sides. Memory stocks have looked the cheapest at peak earnings. But could also mean that market is undervaluing earnings potential, which I think it is.
This is where technicals come in. Let the chart be your guy. Cash is king fsho
Even my 80 year old grandpa has been selling stock the past month, and bears are out here acting like they just made the call of a lifetime after getting their buttholes blown out all year.
Even the school of the blind could see that top put in on $QQQ
Let’s see some P&Ls
Got a pretty good source telling me that more than one firm is getting blown up, and this has been in the making since the April/May squeeze. Could be a gnarly unwind.
Seems like it’ll be the biggest blow up since the meme saga.
@Breadddman The rally is going to be insane. This was a pretty big drawdown this week when a lot of stocks are already beat to tits. INTC top of my list next week. MU as well
$MU hasn’t tested the 200d since June 2, 2025 at $96.
I think that it would make sense for that to happen here.
I expect a bounce off this trendline first unless there’s a big gap down Monday.
Perhaps we see $975-$1,050 before more downside.
Either way MU should give us some nice swings to trade.
Instead of making a big call on a price target, I’d rather just take it one level at a time.
I’m waiting for a big scare that really shakes up semis.
It would be a gift to grab $MU at around $850-$860.
Still amazes me how many furus ignore fundamentals.
@DickJohnso99691 Hahahaha this was their same thesis at $350, but to be fair, it’s not only them that misunderstands this. The SMCI comparison is a big whiff though. MU isn’t engineering financials.
$MU is down -30% from this year’s ATH, but still up 900% YoY, and all the sudden everyone is saying the memory cycle is over.
Sure, a healthy correction is much needed.
Fundamentals tell you what to own, and technicals tell you when to own it.
$MU is a great example of how many people don’t understand fundamentals. The same people hated it at $400, and we know how that turned out.
Let $MU form a bottom and rebuild some relative strength. Patience will be rewarded.
It seems like $MU is the topic of conversation again, and the same narratives are surfacing from when MU was at $350.
Here are my thoughts on what’s misunderstood.
——
Memory is cyclical
There is a misunderstanding of the current memory cycle by comparing it to historical boom-and-bust cycles without accounting for the structural shift in demand driven by AI.
Historically, memory was highly cyclical, driven by PC and smartphone demand, oversupply, and pricing pressure.
Current day, there is explosive demand for HBM and data center DRAM is creating a more durable growth opportunity, while HBM production consumes manufacturing capacity that would otherwise support conventional DRAM supply.
This matters because memory manufacturers historically struggled with excess supply. Today, AI infrastructure spending is driving demand faster than manufacturers can expand production.
——
Competition
Competition doesn't immediately solve the shortage, and the barriers to entry will slow new competition. We know this to be true because established competitors like Samsung and SK Hynix can’t even bring new capacity online overnight.
Competitors can expand capacity, but building advanced manufacturing capabilities, achieving competitive yields, and qualifying with major customers takes years.
HBM also consumes disproportionate manufacturing capacity, restricting conventional DRAM supply.
Micron benefits from both growing AI demand and constrained industry supply, supporting higher prices and margins.
Competition is inevitable, but additional supply doesn’t automatically mean oversupply.
——
Low P/E Ratio
Because memory has been historically cyclical, memory stocks often looked cheapest near peak earnings. A low P/E doesn’t necessarily mean a stock is undervalued if earnings are about to collapse. It’s a legitimate concern.
Given all of the above, MU’s low forward P/E suggests the market may be undervaluing its earnings potential, especially given AI-driven demand, constrained supply, improving margins, and greater revenue visibility through HBM contracts.
The real question isn’t whether MU deserves a higher multiple today. It’s whether the earnings supporting that multiple are sustainable.
A low P/E isn’t automatically bullish, just as historical cyclicality isn’t automatically bearish.
——
I’m NOT saying MU can’t go lower. What I am saying is that the market is applying yesterday's valuation framework to a fundamentally different demand environment.
The bear case is flawed because its assuming past performance is indicative of future outcomes.
This narrative prevented people from buying it at $300, and many got blown out shorting it.
Remember, fundamentals tell you what to own, and technicals tell you when to own it.
Cheers
For the second time in 6 weeks I saved a neighbor from a fire.
6 weeks ago my next door neighbors generator caught on fire and almost burned down both of our houses.
Yesterday, the electrical box that services the neighborhood which is in an easement in our backyard caught on fire. The arcing ran a current to our boxes and melted them on ten side of the house. This fire here grew 10X in 5 minutes.
Our house is fine but we won’t have electricity or internet for 5-7 days. We are going to lose our 100 year old oak tree, which is the worst news of all.
2026 has been the most challenging year of my life.
At least this was one of the best weeks I’ve had in the market all year.
Things can always be worse!