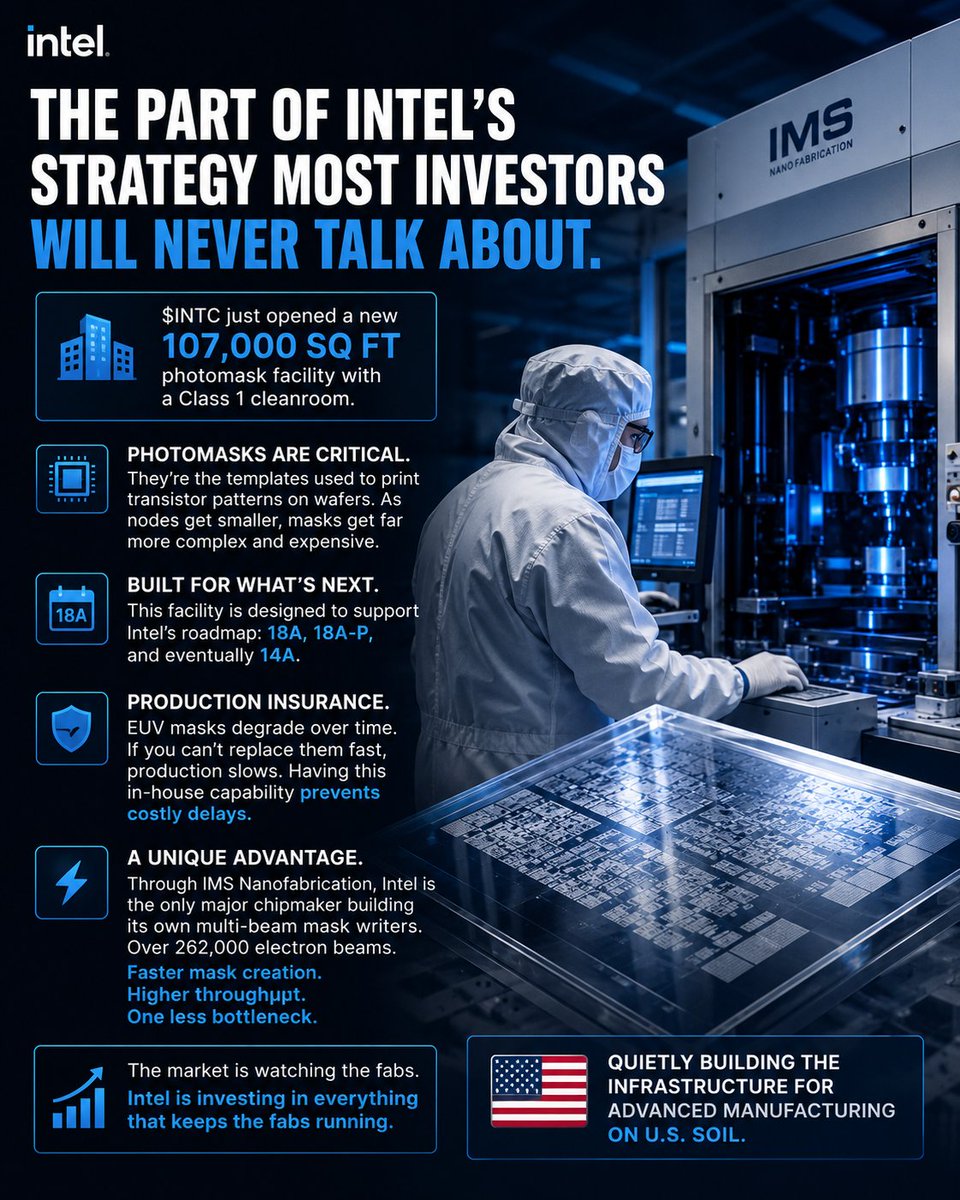
🧵 The part of Intel's foundry strategy most investors will never talk about.
$INTC just opened a new 107,000 sq ft photomask facility with a Class 1 cleanroom.
At first glance, that sounds boring.
It isn't.
Photomasks are essentially the templates used to print transistor patterns onto wafers. As nodes get smaller, the masks become dramatically more complex and expensive.
This facility is being built to support Intel's future roadmap, including 18A, 18A-P, and eventually 14A.
Here's the part I think matters.
Advanced EUV systems are incredibly powerful, but the masks don't last forever. Over time they degrade, get damaged, and need to be replaced.
If you can't replace them quickly, production slows.
That means a mask shop isn't just manufacturing infrastructure.
It's production insurance.
Intel also has an advantage that doesn't get discussed enough.
Through IMS Nanofabrication, Intel is the only major chipmaker that owns the company building the world's leading multi-beam mask writers.
Instead of writing masks with a single electron beam, IMS systems use over 262,000 beams simultaneously.
Faster mask creation.
Higher throughput.
Less risk of becoming a bottleneck.
Most investors are focused on foundry customers, yield numbers, and whether Intel can win share from TSMC.
Those things matter.
But none of it works without the infrastructure behind it.
This looks like another piece of Intel quietly building the ecosystem needed to support advanced manufacturing on U.S. soil.
The market is watching the fabs.
Intel is investing in everything that keeps the fabs running.
𝗜𝗡𝗧𝗖 𝗪𝗲𝗲𝗸𝗹𝘆 𝗥𝗲𝘃𝗶𝗲𝘄
Week ended November 20, 2026
𝗠𝘆 𝗿𝗲𝗮𝗱
Intel has the worst luck right now. They finally got the big customer. Just in time for this week.
In a terrible week for stocks Intel actually did better than most.
Intel had its best customer news in weeks, but the stock still fell about 14% for the week, from $59.66 to $51.28.
Thursday’s gain on the Microsoft and 18A-P news was erased Friday as chip stocks sold off hard.
The customer wins improve Intel’s story. They have not changed the near term financial test yet.
𝗪𝗵𝗮𝘁 𝗰𝗵𝗮𝗻𝗴𝗲𝗱
Microsoft confirmed a long term Azure collaboration that includes multi year Xeon supply capacity and Intel EMIB packaging for Azure silicon. That gives Intel a role in both the CPU and packaging layers.
CEO Lip Bu Tan also said Intel signed an outside customer for 18A-P. The customer remains unnamed, and Intel has not given production timing or contract details.
Socionext had already announced plans to develop chips using 18A-P in August.
𝗪𝗵𝗮𝘁 𝘀𝘁𝗶𝗹𝗹 𝗵𝗮𝘀 𝘁𝗼 𝗽𝗿𝗼𝘃𝗲
Intel Foundry generated $411 million in external revenue in Q3 and posted a $1.85 billion operating loss. That is the gap between customer interest and a foundry business that can cover its costs.
At $51.28, $INTC market cap is about $272 billion. Q3 cash and short term investments were roughly $54 billion against about $50 billion of debt, putting enterprise value near $268 billion, or about 4.5 times trailing sales.
𝗪𝗵𝗮𝘁 𝗜’𝗺 𝘄𝗮𝘁𝗰𝗵𝗶𝗻𝗴
Can Intel identify the 18A-P customer and show a credible path from signing to production and external revenue? Until then, the announcements support the turnaround thesis, but execution still has to carry it.
Sources: Intel Q3 results, October 29; Microsoft and Intel, November 18; CNBC, November 19; Socionext, August 18; Yahoo Finance and StockAnalysis, November 20.
I feel like my picks lately have been performing terribly to be honest. $KEEL, $IREN and $NBIS.
Here is the thing. I have been DCA ing of course as much as I can.
The companies are still going to need power and a location. It will be getting harder and harder to get data centers approved due to moratorium’s. Not to mention lack of a power interconnection.
The stocks I believe in have all of that. Even if ai infrastructure is cut in half. And it won’t be. The demand Still outweighs the supply. These stocks will go back up.
Who can change my mind?? Even Archook isn’t happy about the market last week!
Good night friends! I am feeling better. I was finally able to eat after yesterday.
I am still pretty tired but I am on the mend. For once Archook isnt chasing me to bed lol. She does like to hide her eyes from the light.
𝗗𝗚𝗫𝗫 𝗪𝗲𝗲𝗸𝗹𝘆 𝗥𝗲𝘃𝗶𝗲𝘄
November 16–20, 2026
𝗠𝘆 𝗿𝗲𝗮𝗱
DGXX had a strong operating update and a poor week in the market. Yet they dropped a lot less than the other companies in the niche. The AI business is growing. The market wants results.
The first big test is getting the Columbiana project online and starting Cerebras billing on schedule.
𝗣𝗿𝗶𝗰𝗲 𝗮𝗰𝘁𝗶𝗼𝗻
$DGXX closed Friday at $1.85, down 18.9% from the prior Friday’s $2.28 close. It traded between $1.83 and $2.35 this week, with about 15 million shares traded across the five sessions. The decline followed the Q3 release.
𝗪𝗵𝗮𝘁 𝗰𝗵𝗮𝗻𝗴𝗲𝗱
Q3 revenue was $12.25 million, up 85% from Q2. AI revenue reached $5.66 million, or 46% of quarterly revenue.
DGXX reported $1 million in net income, but digital currency and warrant valuation gains supported that result.
Cash, cash equivalents, and digital currencies totaled $119.6 million at September 30, with no borrowings then outstanding.
𝗧𝗵𝗲 𝘁𝗲𝘀𝘁
The 15 MW first phase at Columbiana is expected to give Cerebras access on December 15, with billing expected to begin in January.
The $200 million financing remains subject to final documentation and conditions. DGXX’s $250–$300 million annualized revenue run rate target by Q3 2027 also depends on financing and market conditions.
𝗥𝗶𝘀𝗸 𝗰𝗵𝗲𝗰𝗸
Shares outstanding rose from 69.4 million at year-end 2025 to 101.4 million as of September 30.
That dilution matters. The company now has to execute its buildout without putting too much more pressure on shareholders.
𝗪𝗵𝗮𝘁 𝗜’𝗺 𝘄𝗮𝘁𝗰𝗵𝗶𝗻𝗴
Does Cerebras get access to Phase 1 on December 15, and does DGXX confirm the financing is closed? Those are the next concrete tests.
Sources: DGXX Q3 release and 10-Q, November 13, 2026; StockAnalysis and Finabase historical prices.