@HDFC_Bank
I’m a current account holder in HDFC bank.
Received foreign remittance intimation 4 days back, and same was accepted and disposed from my side on same day, still amount not credited in my account.
This is very disappointing and not expected from hdfc bank.
Hi @ICICILombard,
very disappointing, During breakdowneven call was not connected to RSA Team, whenevever your support executive transfers call to RSA Team, it gets disconnected every time. What is the use of opting RSA if you can’t provide service when required.
DL6EV5001
अपने इस मुकदमा से थक चुका हू वर्तमान में थाना डौकी में जाँच हो रही पीड़ित की विवेचना घोर लापरवाही अभियुक्त के राजनैतिक दबाब व मोटी रकम से मेरे साथ अन्याय हो रहा है मेरी शिकायत को संज्ञान लिया जाये अगर न्याय नही मिला अन्याय हुआ मेरा अंतिम संस्कार थाना डौकी पुलिस करे वही मरुंगा
पीड़ित के अस 97/25निष्पक्ष जाँच नही हो रही पीड़ित को इतना आहत गया की मरने का राश्ता चुना @Uppolice@agrapolice@DCPEastAgra@dgpup@CMOfficeUP प्रशासन तब सुनेगा ज़ब तक़ पीड़ित आत्मदाह ना करले थाना डौकी विवेचक पीड़ित से सम्पर्क नही कर रहा इससे साबित होता है आरोपी से मिला हुआ है
अपने इस मुकदमा से थक चुका हू वर्तमान में थाना डौकी में जाँच हो रही पीड़ित की विवेचना घोर लापरवाही अभियुक्त के राजनैतिक दबाब व मोटी रकम से मेरे साथ अन्याय हो रहा है मेरी शिकायत को संज्ञान लिया जाये अगर न्याय नही मिला अन्याय हुआ मेरा अंतिम संस्कार थाना डौकी पुलिस करे वही मरुंगा
Free TDS/TCS tool built for Indian Tax Professionals and CAs 👇
✅ 91 section codes
✅ IT Act 1961 + IT Act 2025 mapping
✅ Finance Bill 2026 rates
✅ New vs Old Regime slab tables
✅ Built-in calculator
✅ Works on mobile
✅ Zero login. Zero cost.
Applicable for Tax Year 2026-27
Bookmark this before your next TDS filing.
🔗 https://t.co/oWpVM1Bwkq
#TDS #TCS #CA #IncomeTax #FinanceBill2026 #TaxationUpdates
STOP USING YOUR IPHONE LIKE A BASIC FLIP PHONE.
You’re only using 10% of what iOS can actually do.
Copy these 15 hidden features to upgrade your daily workflow
🛑STOP ASKING CHATGPT THAT "REPLY THIS SCN"
Bad prompt = Confirmed demand.
Smart prompt= Half the case already won.
Use these SCN-Optimized Prompts to draft replies like a seasoned litigator:
1. Issue Extraction Prompt: -
“Extract all legal, factual, and procedural issues raised in this SCN and categorize them clearly. Text: [paste SCN].”
2. Fact-Correction Prompt: -
“Identify factual inaccuracies, assumptions, and misinterpretations in this SCN and rewrite the corrected facts. Text: [paste].”
3. Statutory Defence Builder: -
“Prepare section-wise and rule-wise rebuttals to every allegation in the SCN with short, crisp explanations. Text: [paste].”
4. Case Law Alignment Prompt: -
“Identify relevant case laws that directly counter the SCN’s arguments and explain how each applies. Issue: [paste].”
5. Evidence Mapping Prompt: -
“Map each allegation in the SCN with the exact document, proof, or record required to rebut it. Text: [paste].”
6. Procedural Violation Checker: -
“Check the SCN for procedural defects (limitation, jurisdiction, natural justice, pre-SCN notice, missing documents, etc.). Text: [paste].”
7. Reply Drafting Prompt: -
“Draft a structured SCN reply with:
– Issue
– Correct facts
– Legal arguments
– Case laws
– Evidence references
– Conclusion
Text: [paste SCN].”
8. Tone & Clarity Enhancer: -
“Rewrite this SCN reply in clear, assertive, professionally courteous litigation tone. Text: [paste].”
9. Weakness Detector Prompt: -
“Identify weak paragraphs, unsupported claims, risky admissions, and missing evidence in this SCN reply. Suggest precise fixes. Text: [paste reply].”
10. Burden-of-Proof Shift Prompt: -
“Rewrite this SCN reply to properly shift the burden of proof where applicable (valuation, ITC, classification, place of supply, etc.). Text: [paste].”
11. Quantification Error Finder: -
“Analyse the SCN and list all errors in computation, interest, penalty, or period selection. Text: [paste].”
12. Explanation → Argument Converter: -
“Convert these explanations into legally sound arguments backed by sections and case laws. Text: [paste].”
13. Alternative Argument Prompt: -
“Draft alternative/subsidiary arguments in case the primary defence fails. Issue: [paste].”
14. Draft → Hearing Strategy Prompt: -
“Create a hearing brief from this SCN reply with the 5 strongest points and the ideal oral-submission flow.”
15. SCN Tracker Prompt: -
“Convert this SCN into a compliance checklist:
– Documents to collect
– Evidence to prepare
– Case laws to rely on
– Deadlines
Text: [paste].”
16. Notice Severity Assessment: -
“Classify this SCN as low/medium/high-risk and justify based on quantum, allegation type, and legal vulnerabilities. Text: [paste].”
17. Summary for Management: -
“Prepare a short, non-technical management summary of this SCN, its risks, and defence strategy. Text: [paste].”
18. Precedent Conflicts Finder: -
“Check if any contrary case laws exist which the department may rely on and prepare counter-arguments. Issue: [paste].”
19. Penalty Immunity Arguments: -
“Draft arguments to eliminate penalty using mens rea, bona fide belief, voluntary compliance, and absence of suppression. Text: [paste].”
20. End-to-End SCN Defence Builder: -
“Create a complete defence strategy for this SCN from reply drafting → document collation → case laws → hearing → appeal preparation. Text: [paste].”
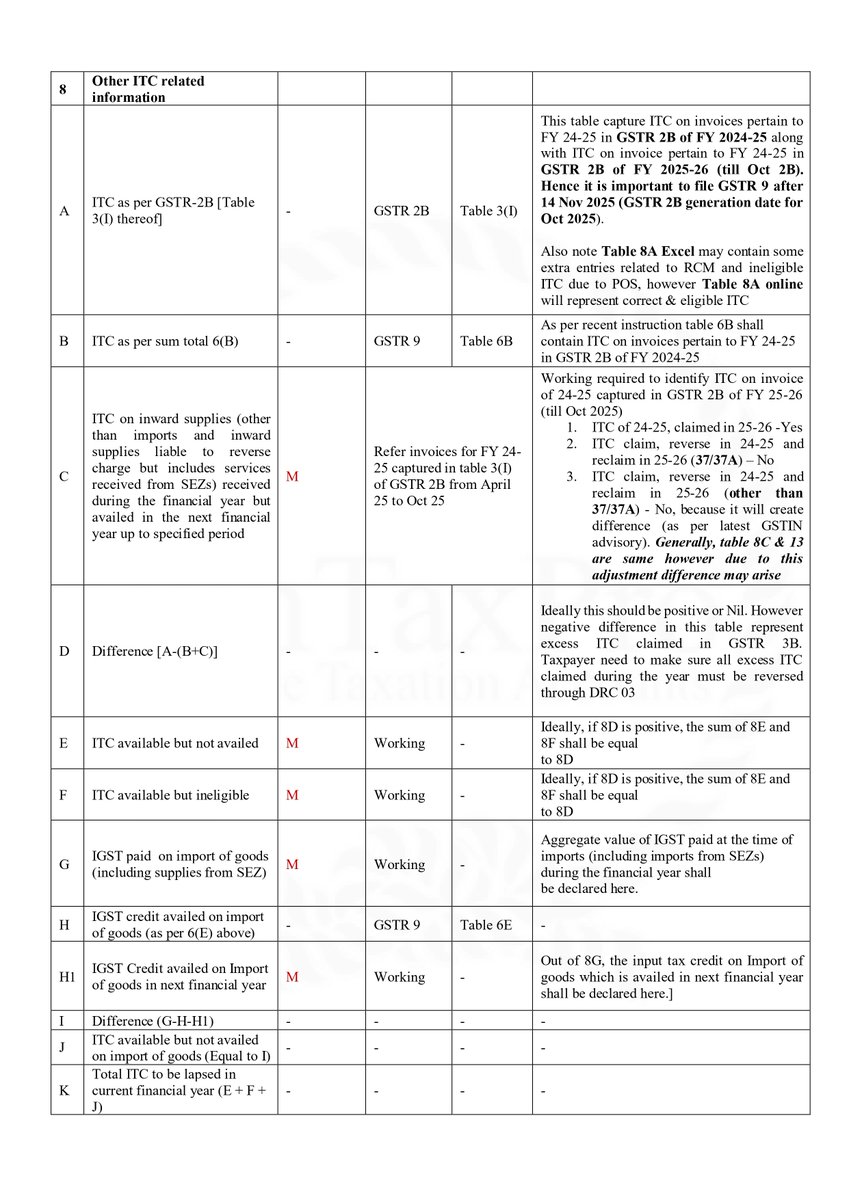
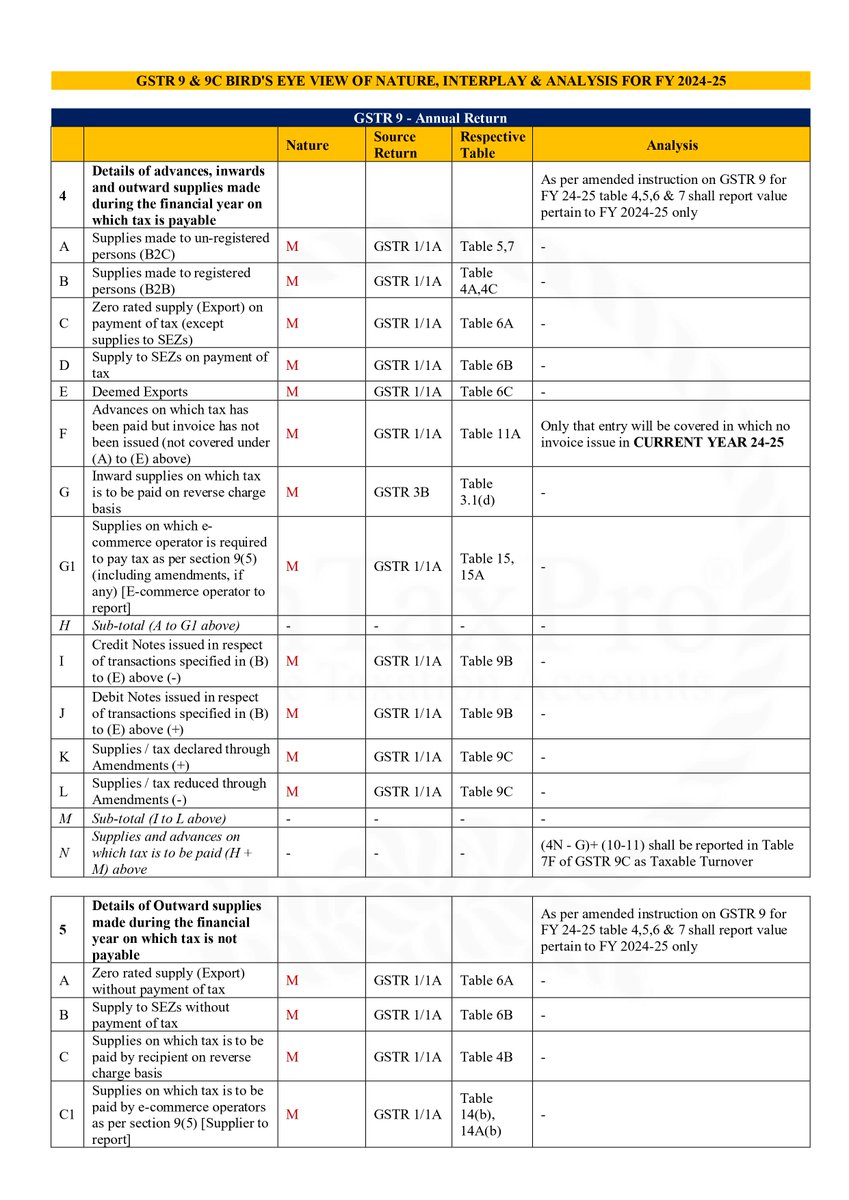
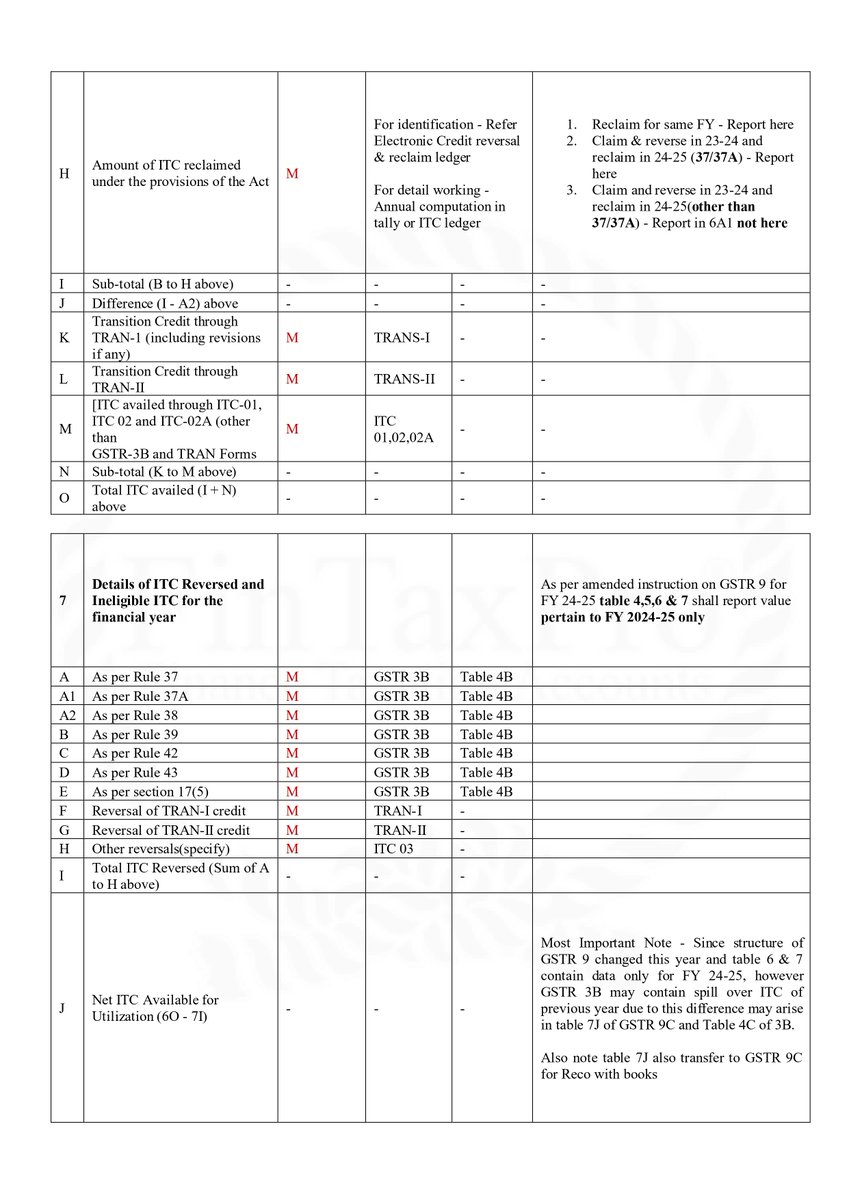
🚨 Major Changes in GSTR 9 & 9C for FY 2024-25!
Comment GSTR 9 and i will dm you all notes for FY 2024-25
This year, GSTR 9 & 9C come with several conceptual and reporting changes — and to simplify your understanding, here’s a bird’s-eye view covering three key aspects:
🔹 Nature – Understand which tables are mandatory or optional this year.
🔹 Interplay – Decode the linkage between GSTR-1, GSTR-3B, GSTR-9 & GSTR-9C.
🔹 Analysis – Learn the reporting logic, workings, and reconciliation points in detail.
📘 For comprehensive, step-by-step practical learning, enroll in
👉 Practical Course on GSTR 9 & 9C (FY 2024-25) available now https://t.co/r0CGr6QvIh
Regards,
Team FinTaxPro
The Central Board of Direct Taxes (CBDT) has decided to extend the specified date for filing various audit reports for the Previous Year 2024–25 (Assessment Year 2025–26), from 30th September 2025 to 31st October 2025, for assessees referred to in clause (a) of Explanation 2 to sub-section (1) of section 139 of the Act.