“To others, being wrong is a source of shame; to me, recognizing my mistakes is a source of pride. Once we realize that imperfect understanding is the human condition, there is no shame in being wrong, only in failing to correct our mistakes."
- George Soros @georgesoros
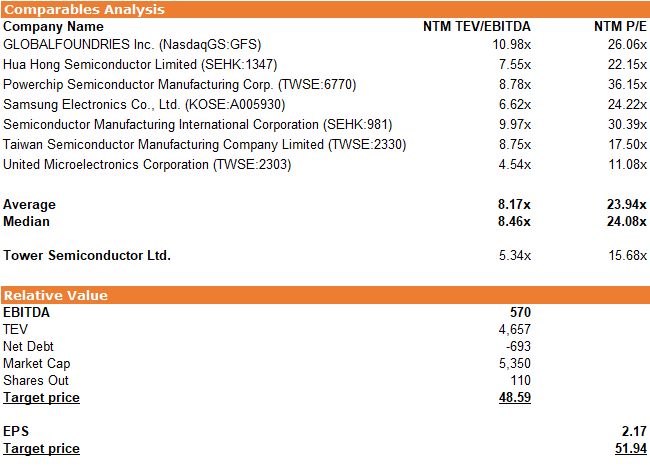
@trapso888 I'd use fundamental metrics rather than beta. but regardless, you might add the other global foundries such as SMIC, Samsung, Global Foundries, Hua Hing, Vanguard, and PSMC to those two. However, decoupling and tensions over Taiwan will boost TSEM's business either way
@MisterMartinII @Capitol_Forum Also, does Mobileye make chips for driverless vehicles for US companies or for Chinese ones?
If it’s a matter of National Security for China, why should SAMR allow the merger?
@MisterMartinII I can’t follow your point. As far as I understand from $TSEM public filings, the company has no manufacturing facilities in China, so I’d be curious to understand what you mean by Mobileye chips being made in China by TSEM.
@____GigA____ The average close for the three months before the announcement was $36.97 per share.
@Dealreporter has just come out with an article, have you read it?
@4drant The pre-announcement price was USD 32 per share. The standalone intrinsic value for $TSEM should be much higher than that, especially when taken into consideration that it's among the very few foundries with no assets in Taiwan and China.
@____GigA____ Is that PE net of cash?
Perhaps you could use total enterpise value to earnings? This way your multiple might make more sense.
During the period you picked, the company went from 1.5x net debt to EBITDA, to excess cash.