ADL is a relic of isolated margin systems copied from @BitMEX. It doesn’t work for options, and at best is a terrible experience for cross-margin users.
Paradex deliberately chose not to implement ADL.
It breaks cross-platform hedges, adds a lot of unpredictability to users’ risk management, and fails for complex assets and portfolio-margin setups. There’s also no guarantee of finding profitable ADL counterparties under cross margin, without further amplifying liquidations. @DeribitOfficial also operates without ADL.
Socialized loss (SL) is a far better experience for users and scales easily to more complex assets and margin types 👇
Portfolio-Level Integrity
ADL operates at the single-market level, without considering the user’s overall account exposure. The trader who is high on the ADL queue due to a highly profitable/leveraged position on one market isn't necessarily profitable on an account level.
Example:
BTC = $100,000, ETH = $4,000
Insurance Fund (IF) = $100,000 collateral + short 40 BTC perps.
Alice has a $4M BTC-ETH spread on, i.e. +40 BTC perps (long) and –1,000 ETH perps (short)
→ Both BTC and ETH rally +5%
→ BTC to $105,000, ETH to $4,200.
Under a normal scenario, Alice’s BTC and ETH positions offset, leaving her with flat PnL. But the insurance fund’s bankruptcy price is $102,500. To protect the fund, ADL is triggered and forces Alice’s BTC leg to be closed at $102,500 as it cannot afford a loss that is higher than $100,000. Alice realizes BTC profits based on a 2.5% move while her ETH short continues to lose 5%, leaving her with a $100,000 loss. This can, in theory, lead to an unfair liquidation of Alice's account.
"Ethena" Risk
The same is true for a trader that could be holding the opposite position on a different exchange. If the position is subject to ADL, it closes the profitable leg, leaving the user with a naked losing leg. This destroys the intended hedge and amplifies risk exposure. @ethena smartly negotiated this provision away for it's trading on CEXs but that now means the risk of ADL is being unfairly borne by the exchange's other users. Smart for Ethena but not scalable for the exchange.
Given the potential market exposure imposed on affected accounts, ADL often triggers a forced unwind of positions, leading to fire-sale behavior that further amplifies market volatility and erodes liquidity.
This mechanism is particularly unsuitable for exchanges with options, where users frequently hold multiple correlated instruments on the same underlying asset for hedging or risk-neutral strategies. In such environments, forcibly closing a single profitable leg through ADL can break portfolio hedges, destabilize the portfolio and, by extension, the market.
To our knowledge, NO EXCHANGE discloses how cross-instrument exposures are handled under ADL.
Conditional + Reversible
Under a SL mechanism, losses are conditional, deferred (not immediately realized) and give users a choice. They are applied only upon withdrawal, and only if the platform is still experiencing a solvency deficit at that time.
If the market rebounds, or if the insurance fund grows (either through profitable liquidations or additional allocations) and covers the deficit, the shortfall is erased and no SL is applied.
By contrast, ADL crystallizes losses instantly and doesn’t give the user a choice. If a sudden market move causes insurance fund depletion, the system immediately closes profitable positions via deleveraging. Those users now permanently lose their realized profits.
SL introduces time, and recovery potential into the loss-allocation process while giving users a choice. It penalizes only those who exit during insolvency, while long-term users benefit if solvency is later restored.
Fair + Predictable Risk Distribution
ADL targets specific traders (often highly leveraged and profitable ones), forcibly closing their positions to cover the platform shortfall. It penalizes traders for system-level insolvencies outside their control.
SL by comparison avoids arbitrary targeting and maintains fairness. All users share the risk evenly and only when a persistent shortfall exists.
Transparency
ADL is a complex, queue-based mechanism that is very hard to anticipate for users. In contrast, a SL adjustment is a simple, transparent function of the insurance fund shortfall relative to the platform’s TVL. As it affects users only when they withdraw, it ensures predictability and transparency in the loss allocation.
Compute Efficient = "Chain Friendly"
SL simplicity makes it straightforward to implement on-chain in a trustless manner. There is less compute complexity which means cost and throughput constraints are alleviated. ADL’s dynamic queue logic is computationally heavy as it requires scanning all accounts on the platform, making it very expensive and error-prone. It also adds congestion to a system that is likely to already be congested when ADL is triggered.
October 10 = Wake Up Call
If your CEX can’t guarantee portfolio integrity under stress, it’s the architecture that’s broken. Switch to DEXs with intelligent loss-allocation that protects hedges, distributes risk fairly while staying conditional and predictable.
Paradexio
This is so highly misleading by only focusing on the ADL on the largest coins, which suffered from far less price discolation and ADL overall than other coins
If you are running a long / short book as I was, you are long these assets below, not short them
This also looks at ADL in a vacuum, and without regard to anything else in an account
Your larger shorts are going to be in the other top 50 alts that are dog shit imo (ATOM, STX, APT, FET) - those shorts closed much earlier and blew you out leaving with only longs to liquidate your account
There are so many other places where the @HyperliquidX platform is broken for perps (no ADL transparency / queue, no flash crash protection, one touch price oracles for liquidation (non time based), no whale risk blocker, and zero insurance fund is laughable for someone at $hype scale
So please get this propaganda off my timeline, it is insulting. I can assure you @HyperliquidX did not perform well for anyone running a larger profitable long / short book, or even any sort of mild leverage on just longs. I cannot recommend to anyone serious or an instó to trade on hype when they don't even acknowledge these issues.
In fact, between @DriftProtocol and @dYdX where I run very similar books, only @HyperliquidX blew me out.
Still waiting for my @chameleon_jeff chat 🫡
If you find any engineers working in crypto and not concerned about eMudhra, give them a strong rebuke
If they don’t listen, short their project to zero
Users deserve better
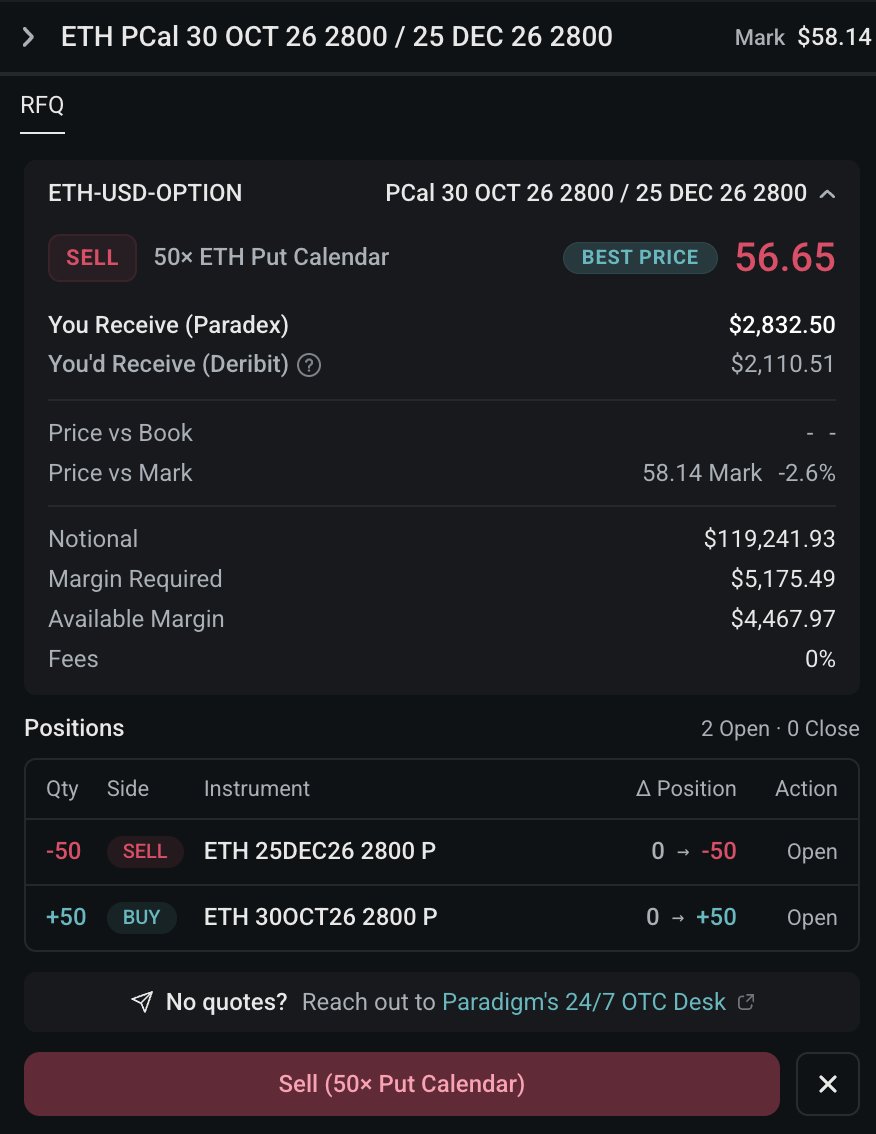
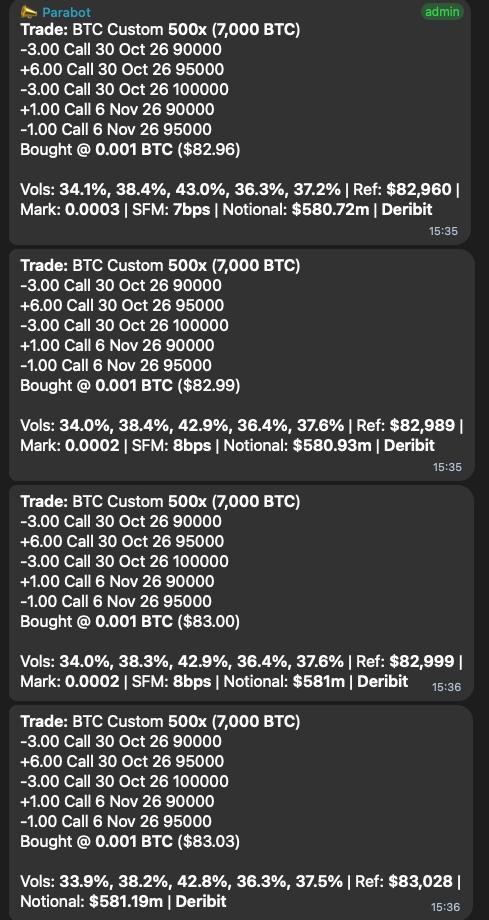
calling all options arb0ooors.
paradex prices are often significantly better than the price on other exchanges. free arb for anyone that can park capital on both venues. all you need to do is RFQ on both venues and pocket the difference
you're welcome ❤️
RFQ traders on @paradex saved ~$140k last month and the reason is simple - retail pays zero on Paradex.
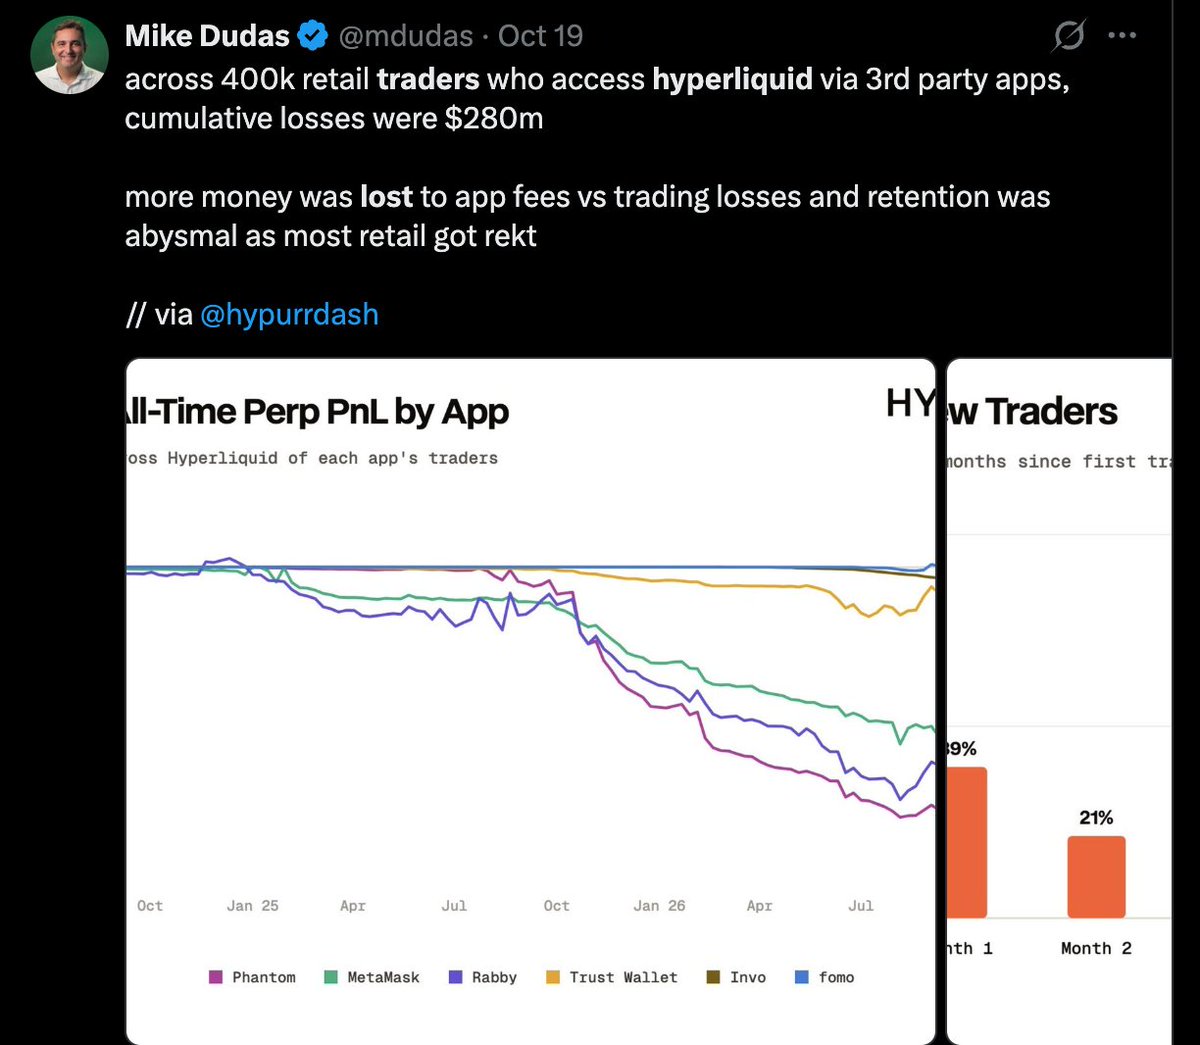
start contrast to the research making the rounds earlier this week that ~400k retail wallets trading on HL are down $280m..... with over half of those losses went to fees, not trades!!
these two trends are inevitable. the more retail loses to fee drag, the more it hurts retention and the more activity moves to zero fee platforms.
majors liquidity on options has improved 10x in the last month making us the most liquid place to trade options on chain.
but its not just majors... as @domdosu reminded me yesterday, our alts orderbooks also starting to look really good. still small size but this is just a glimpse of what is to come... i expect several orders of magnitude improvement in the coming weeks!
Reminder that you DON’T need
to split your trading
across multiple accounts
you just need BETTER tech ❤️
trade 100+ assets from one unified account on @paradex
You DON’T need to split your trading across multiple accounts
You just need better tech
Trade 100+ options and futures from ONE unified account on:
https://t.co/knrBXIybhG
vol compressing is a function of the market maturing. this is also. a huge structural reason for why options take time to mature. when vol is high it makes insurance very expensive so it means less buyers and it is then generally a seller driven market for the first few years. then once vol gets sold off the buyers step in the latter years and then the market really explodes volume wise. every other alt asset will follow this trend!
$BTC moves half as much as it did in 2021 👀
44% volatility over the past year vs 81% back then. Paradex is pricing the next month at 36%.
Calm market = cheaper options. Are you buying or selling here?
Try it yourself 👇🏻
https://t.co/JoZx9xi64S
📉 Bearish $ETH Put Spread 1000x ($4.8M)
🔴 Sell $2,100 Put · 30 Oct 26
🟢 Buy $2,200 Put · 30 Oct 26
Max Profit: $89.3K → if ETH at/below $2,100
Max Loss: $10.7K → if ETH at/above $2,200
You Pay: $10.7K | Max Profit → 8.3x your cost
Copy on Paradex 👇
https://t.co/Ba6kKptSbo
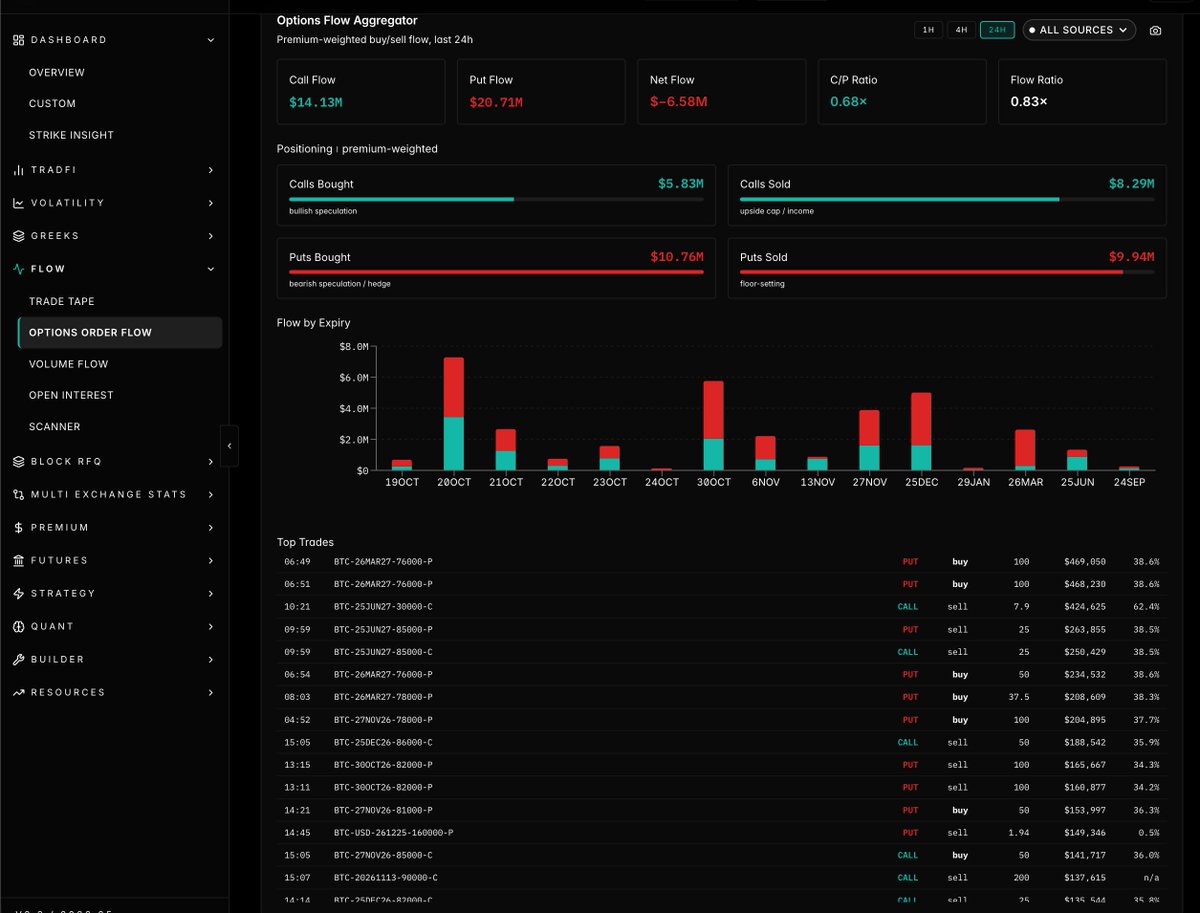
track every Options TRADE that go through via Tape or RFQ on https://t.co/3EroQ3Q57x :)
You can sort it by size, time & every metric literally under section Option Order-flow Section! Track trades from every exchange that offers options😏
Track every RFQs via aggregated Block RFQ section.
View analytics & p much any metric you need - view pay-off , entry at the exact time on chart & whats dominant in the market!
Good to see the Global Option Monitor live. We followed the first trade from the walkthrough all the way to settlement this morning. The BTC short strangle settled $40 below its put strike and the seller kept 96% of the premium it collected.
It was not a calm ride though. On the first evening BTC slid to 80,600 and the position sat almost $5k under water before it slowly came back.
That part never shows on a screen of blocks, where the entry is a single row. What it feels like to hold the trade lives in the marks that follow it every 10 min until expiry. One trade is still only one trade, of course.
Thanks @paradex and @0xEvinho for opening this up to everyone. We will keep following the blocks it brings to the surface on @DeribitOfficial.
Powered by #CayoLargo 👉 https://t.co/xeogMsemIl
across 400k retail traders who access hyperliquid via 3rd party apps, cumulative losses were $280m
more money was lost to app fees vs trading losses and retention was abysmal as most retail got rekt
// via @hypurrdash
Introducing the Global Option Monitor
every serious options trader knows
that block trades are where the alpha is
monitor block trade activity across ALL crypto exchanges
from ONE screen
or copy the whales with ONE click!
trading perps is a disadvantage to options
having an advantage is a function of being dynamic
being dynamic is a function of giving yourself options
be dynamic
trade options
that's my line and i'm sticking to itu
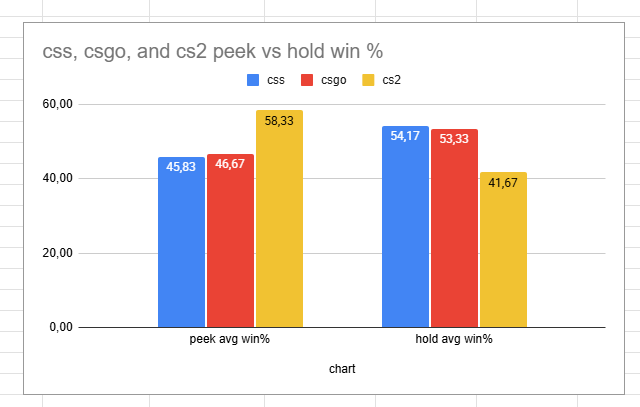
Holding angles in CS2 is a disadvantage compared to CS:S and CS:GO ‼️
Holder win rate (120 duels per game):
CSS: 54.2%
CSGO: 53.3%
CS2: 41.7%
Tested by @Gilboorg, video in the first reply.
for fucks sake when will people get it
L2s are apps themselves (businesses)
L1s are govts...
there is no general purpose L2, it doesn't exist
L2s like Arb and Starknet struggled with their sense of identity for years. they were all trying to be the base layer but as an L2. Starknet moving to an L1 is also symptomatic of the same identity problem.
all L2s are special purpose app-chains.
L2s can't own the base layer, so the apps on top can always leave. 🏚️
@kain points to @megaeth, where he says most curated teams left once they had traction. With @tayvano_ and @austingriffith on Uneasy Money.