#SME#PPEL#PoojaaPrecision#PoojaaPrecisionEngineering
Poojaa Precision Engineering Limited H1 FY27 Concall Highlights:
👉H1 FY27 & Future Outlook :
▫️Revenue from operations ₹210 Cr, up 68% YoY; EBITDA ₹40 Cr, up 73% YoY; PAT ₹25 Cr, up 88% YoY
💠H1 FY26 base: revenue ~₹125 Cr, EBITDA ₹23 Cr, PAT ₹13 Cr
💠EBITDA margin ~19%, PAT margin ~12%, ROE ~25%
▫️FY27 revenue growth guided at ~50% over FY26 (₹294 Cr); FY28–FY30 growth guided at 30–35% CAGR
💠Target annual turnover of ~₹1,000 Cr by FY30
💠Revenue path cited as ~₹630–640 Cr next year, ~₹800–820 Cr the year after, and ~₹1,000 Cr by 2030
▫️Margin outlook: management expects fixed costs of the new plant to be already absorbed, with future costs largely variable
💠No startup-related margin dip expected; no exact margin range given beyond current levels
💠Gross margin down from ~59% to ~53% YoY, attributed to a shift toward larger components (40–80 kg vs 1–9 kg earlier)
▫️Revenue per tonne up ~39–40% in H1: ~8–9 percentage points from raw material escalation, balance from product mix
💠Aluminium moved from ~$2,800/t to ~$3,300/t; management says the full cost is passed through to customers and does not hit the P&L
▫️Working capital: inventory ~₹60 Cr against last month's sales of ₹42 Cr
💠Die stock ~₹20 Cr; die sales ~7–8% of top line, so a small die stock will persist
💠Normal inventory cycle of ~1 month expected to reduce further
👉Order book / projects and pipeline :
▫️Order book ~₹1,180 Cr
💠Mix: ~52% auto (two-, three-, four-wheeler and commercial vehicles), ~48% engineering and non-auto
💠Execution path: ~₹630–640 Cr next year, ~₹800–820 Cr the year after
💠New business added at ~₹160–180 Cr each year over the last three years; RFQ pipeline above ₹2,000 Cr at an 8–10% strike rate
▫️Unit III expansion:
💠Status: 20% of new capacity (~110 t per month) already added; full machine delivery targeted by September 2027
💠Capacity: melting from ~13,800 MTPA to 28,800 MTPA; casting and machining from ~6,000 MTPA to 12,600 MTPA by September 2027
💠Funding: IPO proceeds of ~₹1,598 Mn; capex amount not disclosed on call
💠Revenue potential: capacity built to support ~₹1,000 Cr turnover by FY30
💠Current utilisation ~82% including the expanded capacity (monthly capacity ~610 t; September output ~480 t)
▫️Defence and aerospace:
💠HAL has approved the company for prototype parts; Indian Air Force has approved it after audit and a vendor code issued
💠Certifications required; minimum four years to commercial production, with initial quantities low
💠Defence to be served from Unit III; aerospace from Unit IV (four years out)
💠Alloys: aluminium and aluminium-magnesium
▫️Magnesium components (R&D):
💠Prototyping started; magnesium and aluminium-magnesium strategy to be finalised over the next two years
▫️Customers and exports:
💠Customer count rose to 58 in H1 FY27 from 39 in FY24; five Fortune 500 companies cited as customers (names under NDA)
💠Indirect exports via Indian OEMs at present; direct exports to OEMs expected over the next few years
👉Q&A :
▫️Seasonality: management says the business is tender-based, not seasonal; H2 was ~57% of FY26 revenue, versus 43–47% for H1 historically
▫️Segment margins: auto EBITDA margin ~19%, non-auto ~24%; non-auto contributes ~60% of margin
▫️Revenue mix: auto ~62% and non-auto ~38% in H1 FY27 (FY26: 72:28); long-term target of 33:33:33 across auto, EV and engineering
▫️Energy segment: revenue rose from ~₹17 Cr to ~₹48 Cr in H1, already above FY26's ~₹31 Cr; management frames this as Fortune 500 tender-based business
▫️Alloy sourcing: ~40% bought as primary alloy and converted in-house; ~60% bought as ready-made alloys from customers' validated suppliers
▫️Offloading (~10% of revenue, within other expenses): simple components and surface treatment are outsourced; critical machining stays in-house
▫️Process mix: GDC ~70%, LPDC ~25%, HPDC ~5%; HPDC retained as a customer support process
▫️Win drivers: technology, capability and infrastructure, rather than price alone; company says it is typically among the top two vendors for key customers
👉Others :
▫️Balance sheet: D/E 0.08x, current ratio 4.18x, ROCE 36%, ROI 22%
▫️Debt: management plans to repay the entire loan by the second quarter, with minimal finance cost thereafter
▫️IPO: ₹1,598 Mn raised at ~259x subscription on BSE SME; deployment progressing per schedule
▫️Competitive edge: integrated in-house tooling, casting, machining, surface treatment and testing (CMM, spectro, radiographic, helium leak)
SMEs getting hammered since start of October like anything.
People have lost majority of gains what they made since April to September.
Smallcap Index is not showing right state of broader market.
Markeg never fails to teach and humble.
#SME#DEVSON#DevsonCatalyst#DevsonCatalystLimited
Devson Catalyst H1 FY27 Concall Highlights:
👉H1 FY27 & Future Outlook :
▫️H1 FY27 financials (vs H1 FY26):
💠Revenue ₹31.69 Cr (₹3,168.78 lakh), +1.14% YoY
💠EBITDA ₹9.71 Cr (₹971.62 lakh), +10.13% YoY
💠EBITDA margin 30.66% vs 28.16%, +250 bps YoY
💠PAT ₹7.50 Cr (₹750.36 lakh), +13.12% YoY
💠PAT margin 23.68% vs 21.17%, +251 bps YoY
▫️Margin driver: higher catalyst sales
💠Catalyst ₹2,531.80 lakh vs ₹1,326.22 lakh in H1 FY26
💠Adsorbents ₹249.53 lakh vs ₹428.52 lakh
💠Ceramic balls ₹381.35 lakh vs ₹1,345.30 lakh
▫️Geographic mix: domestic 93.28% vs 57.05%; export 6.72% vs 42.95% in H1 FY26
💠Exports hit by Middle East supply chain disruption (Strait of Hormuz)
💠Middle East was ~70–80% of exports
💠Freight on a 20 ft container rose from ~$600–800 to $6,000–8,000
💠USA was affected by tariffs
💠Revenue would rise drastically if Hormuz normalises; export sales expected to improve once shipping and logistics normalise
▫️FY27 growth: expected slightly higher than last year
💠Management can maintain the past growth rate
▫️Growth levers:
💠Catalyst business is 2–3 years old and Indian customers are not fully covered yet
💠New geographies: Russia, Africa, South Korea
💠Wider product portfolio
💠Business development head hired from an MNC
▫️Operating cash flow: net operating cash flow ₹6.37 Cr in H1 FY27
▫️IPO proceeds: fund the new manufacturing facility and long-term working capital
👉Projects and pipeline:
▫️Order book: over ₹28+ Cr as of 31 Oct 2026, scheduled for execution by March 2027
💠Mostly one-time orders, to be completed this FY
💠Export orders in hand ~₹25–28 Cr, similar to last year
💠Contractual order: a 100-ton contract with call-off POs of 10–15 tons, timing uncertain
💠Tender pipeline details to be shared later
▫️Second facility (new plant):
💠Operational by Q1 FY28
💠Expansion of ~5,000 MT; total planned capacity 11,293 MTPA
💠₹1.07 Cr advance paid for the factory shed; PEB structure ordered, labour quarters complete, erection ~3 months after Diwali
💠Machinery order to close in ~15 days; machinery delivery in 3–4 months
💠4,000 sq m vs 7,000 sq m for the existing plant; more automated, catalyst-oriented process from the first stage
💠Fungible between catalyst and adsorbent
💠Utilisation can reach ~50% in FY28; saturation sooner if a new product is commercialised
💠Funded from IPO proceeds
▫️Third facility: only once the second reaches 70–80% utilisation or is saturated by a new opportunity
💠Land already acquired
▫️Current utilisation: 80–90%
▫️Ammonia Decomposition Catalyst: commercialised through in-house R&D
💠Commercial orders received from NMDC and Tata Steel after customer evaluation
▫️PE catalyst: cage trial and physical property tests complete; chemical results awaited
▫️Pipeline: 4 more catalysts planned, along the lines of an existing catalyst and using the same raw materials
👉Q&A :
▫️Realisation per kg: not disclosed; varies by catalyst
▫️Raw materials: ~97% indigenous
💠Oxides: aluminium oxide, silica, zinc oxide, titanium, sodium carbonate
💠Anatase titania sourced from outside India
💠Ceramic inputs (clays, minerals) from Gujarat (Surendranagar/Thangadh) and Rajasthan
💠Natural gas price doubled and is passed through to customers
👉 Others :
▫️Competition: Süd-Chemie Clariant (German MNC with an India plant)
💠Entry barrier is the process know-how
▫️Reach: customers across 22 Indian states/UTs; exports to 15+ countries
▫️End sectors: oil and gas refining, petrochemicals, natural gas and hydrogen, fertilisers, steel, emission control, specialty chemicals and pharma
#SME#VIVIDEL#VividElectromech#VividElectromechLimited
Vivid Electromech H1 FY27 Concall Highlights:
👉H1 FY27 & Future Outlook :
▫️H1 FY27 results: revenue ₹91.53 Cr (+29.7% YoY), total income ₹92.15 Cr (+30% YoY)
💠EBITDA ₹19 Cr (+37.5% YoY), margin 20.62% vs 19.49%
💠PAT ₹13.08 Cr (+38.5% YoY), PAT margin ~14.2%
▫️FY27 guidance: 35-40% YoY growth maintained, ~₹300 Cr revenue target; on track despite the ~1 month delay in the new facility
💠Orders already in hand, drawing stages done, execution started
💠Management sees no doubt in achieving or bettering the numbers
▫️H2 weightage: H2 is generally ~2x H1 revenue
💠H1 fixed costs are spread over ₹91 Cr revenue, so full-year margins look higher than H1
💠H2 margins expected in line with H2 FY26
▫️Margins: H1 FY27 margin is similar to H1 FY26; current levels are a "floor", with margins kept in focus while negotiating orders
💠Exit from residential/commercial (cutthroat competition, bad debts), focus now on infrastructure and data centres
💠Larger ticket sizes; data centre floors are designed once and repeated across 8-9 floors, which lowers engineering cost
💠Bulk discounts from vendors; among the top 1-2 ABB system integrators, giving better raw material pricing
▫️Revenue mix: LV panels 82%, MV panels 17%, balance traded products and services
💠Industry: data centres ~52%, infra & real estate 24%, industrial 17%, solar & others 7%
💠Geography: Maharashtra 77%; domestic ~91%, exports ~9%
💠71 customers served in H1, average revenue per customer ~₹1.28 Cr
▫️Exports: ₹8.1 Cr in H1 FY27 vs ₹2.5 Cr in all of FY26
💠Markets: Tanzania, Kenya, Mali, Burkina Faso, Ghana
💠Supply-only, LC-backed orders with better cash flow; margins comparable to the infrastructure segment
▫️Working capital: elevated in the near term, expected to ease as execution progresses and collections come in
💠Cash flow from operations ₹(55.49) Cr in H1, on higher inventories, short-term advances, lower payables, other bank balances and tax paid
💠Management expects a drastic improvement in receivables in the next balance sheet
▫️Funding: no cash flow issues expected for at least 18 months from September-end
💠~₹11 Cr of IPO money in FD, accessible only from April 2027
💠Non-fund based limits being increased to cover performance bank guarantees and defect liability retention
💠Pre-IPO limits of ~₹30 Cr with ICICI and Kotak (₹20 Cr repaid); unutilised limits can be drawn within ~10 days
▫️IPO proceeds: of ₹104.56 Cr fresh issue, ~₹81.64 Cr utilised till 30 Sep 2026, ₹22.92 Cr unutilised
💠Used for borrowing repayment, capex, working capital and other approved purposes
💠₹9 Cr reallocated from manufacturing capex to working capital (shareholder approval at AGM on 25 Aug 2026)
👉Order book / projects and pipeline:
▫️Executable order book: ~₹307 Cr as of 26 Oct 2026, giving revenue visibility for the next two quarters
💠Execution cycle 2-9 months
💠Data centres ₹115 Cr, metro rail ₹46 Cr, other industries ₹146 Cr
💠Exports ~₹66 Cr (~22% of order book)
💠43 customers; ~89% of order value from existing customers, ~11% from new
▫️Ambernath facility (Phase 1):
💠Machines received and under installation; operations starting on the ground floor
💠Commercial operations expected by end of November 2026, subject to statutory approvals
💠First dispatches from the new facility expected from end of November
💠Phase 1 adds ~5,000 verticals of capacity
💠Phase 2 (without office / experience centre block) targeted by end of December 2026
💠Full facility adds 15,000 verticals annually, taking total capacity from 7,500 to 22,500 per year
💠Full utilisation expected in 1 to 1.5 years
💠Robotic fabrication, automation and in-house testing
💠Capex of ~₹34 Cr incurred so far
💠Revenue potential at full utilisation not quantified
▫️Current capacity utilisation: Navi Mumbai and Pune facilities both at ~95%
▫️800V LV panels: launched, type tested at CPRI Bhopal as per IEC 61439
💠Targeted at renewable energy applications
▫️Mactech Infra Solution: acquired 99% partnership interest
💠Siemens licence partner for 8PU LV switchboards
💠Aimed at broadening the product range in industrial electrical and automation
▫️Data centre customers: Sify Global Data Centers, CtrlS Data Centers, AdaniConneX
💠Other customers: NCC, Afcons, JSW, Spenomatic Solar
▫️Order inflow: management is deliberately not taking skid-solution data centre orders (supply of transformers on skid)
💠Those orders carry 1-2 year delivery timelines with price volatility risk
💠Current orders are SITC of LV panels and PDUs, with deliveries within ~6 months
💠Priority is executing the existing order book; fresh bookings for the next 2-3 quarters likely from January onwards
▫️Solar manufacturing plants: solar cell, ingot and wafer plants flagged as a big focus segment
💠Ticket sizes are large
💠Some orders already won and announced on NSE
👉Q&A :
▫️Receivables: ₹116 Cr at March 2026, ~₹124 Cr after H1 billing (₹91 Cr + GST), ₹119.75 Cr at September 2026
💠Management says ~₹120 Cr was collected in H1
▫️Data centre payment terms: ~10% retention for 1-2 years, balance milestone-based
💠After commissioning another 10% is released, and another 10% after the final integrated test
💠Data centre commissioning is delayed 3-6 months after supply due to site-related factors
▫️Receivable improvement steps:
💠ICICI and Kotak have enhanced non-fund based limits, and issuing performance bank guarantees has started
💠A recent Chennai data centre order was negotiated with up to 90% LC-backed payment terms
💠Cost is ~0.25% of margin, but cash flow is 2-3x faster than a regular data centre project
▫️Segment disclosure: no segment-wise margin bifurcation yet
💠Facility-wise breakups started this quarter; segment-wise breakups expected in a couple of quarters
▫️Export counterparties: ~50-60% direct customers based in East Africa, ~30-40% Indian EPCs (NCC, Shapoorji, Afcons)
💠All export orders are LC-backed, with no open credit
💠Minimum 10% advance in USD, balance 90% on 60 or 90-day LC
💠Due diligence done on LC-issuing banks; no LC devolvement seen so far
▫️V-SET (own brand): type tested at CPRI Bhopal, CPRI Bangalore or ERDA
💠Switchgear-agnostic, so any of the type-tested OEM switchgear can be used, giving more negotiating power with OEMs
💠PDUs are included in V-SET figures
💠V-SET vs PDU split not available on the call; management to share it later
▫️ArTu K dependence: ArTu K was ~65% of FY26 revenue
💠Share fell in H1 as own-design products (V-SET, PDU) replaced it, and it will be held at the lower level
💠Own products earn better margins, since the switchgear brand is open (ABB, Siemens, Schneider) while ArTu K is ABB-only
▫️ArTu K licence cost: ~₹45-50 lakh paid ~7-10 years back
💠Royalty to ABB only ~₹7-10 lakh a year
👉 Others :
▫️Borrowings: total borrowings ₹24.27 Cr vs ₹33.30 Cr at March 2026
💠Long-term borrowings ₹1.76 Cr vs ₹19.66 Cr; ~₹23.02 Cr repaid in H1
💠Short-term borrowings rose to ₹22.51 Cr to fund procurement and execution of ongoing orders
💠Net cash positive ₹1.15 Cr at September 2026; debt/equity 0.15x vs 0.56x at March 2026
▫️Working capital items: inventories ₹17.29 Cr vs ₹6.66 Cr, on procurement ahead of scheduled project execution and dispatches
💠Trade payables reduced after supplier settlements
▫️Cash flow: investing outflow ₹(28.23) Cr, on capex of ~₹34.08 Cr towards capacity expansion
💠₹23.32 Cr of IPO proceeds parked in other bank balances/FDs is included in the operating outflow
▫️OEM partnerships: ABB, Hitachi, L&T (Lauritz Knudsen), Siemens
💠Execution presence across 15+ states
Indian Railways has recently sanctioned 765 crore for traction system upgrades and digital communication infrastructure.
VANS Electroengineering manufactures single- and double-pole vacuum circuit breakers/ interruptors used in railway traction systems, including the 2×25 kV system being adopted for modernisation.
A niche railway electrification player worth tracking.
Having said that - Stock has rallied significantly in a short span since its ipo.
People are asking why FII are moving away from India
It’s because if zero innovation and poor government policies
Also the valuations at which Indian companies are trading are far more rich with similar or even lower growth than US counter parts
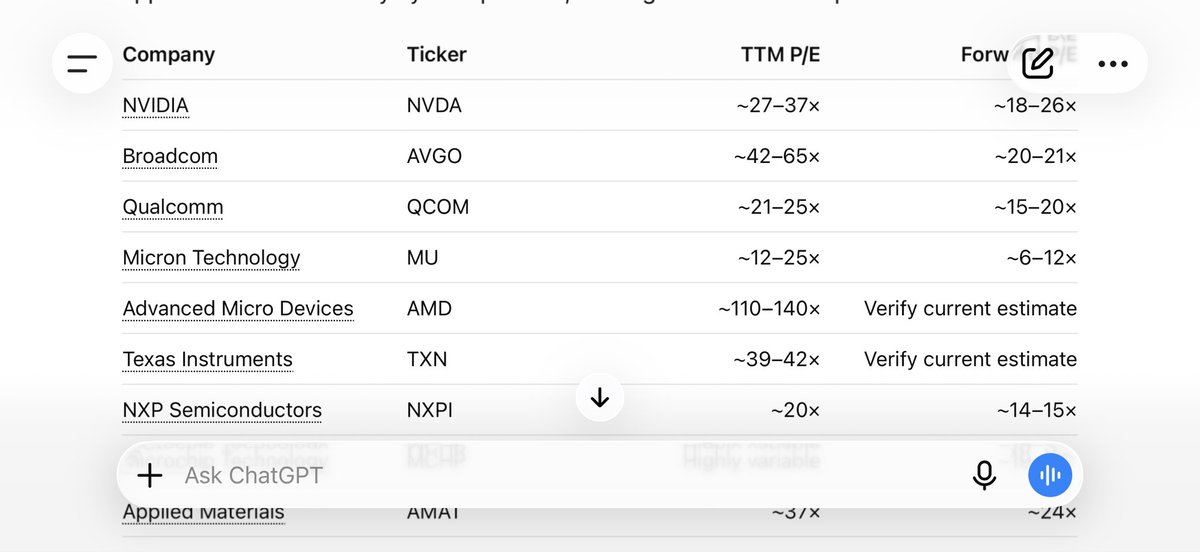
Take semi conductor stocks for example:
Companies like micron are trading at 5-6 forward PE and 10 TTM PE
here is a reference table for example, so if valuations are cheap in US why will they invest in overvalued Indian companies ?
Same is the story in Neo cloud companies too.
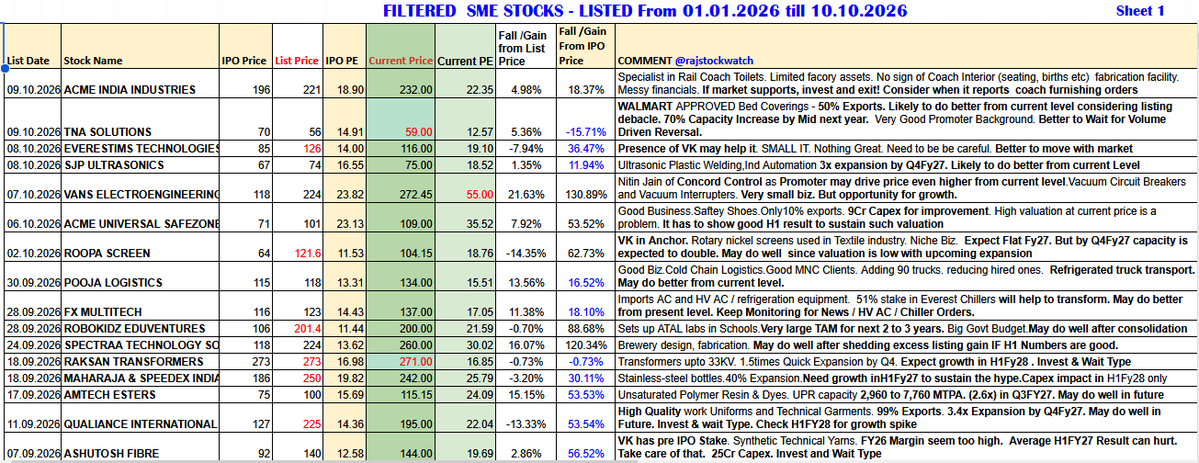
🌟🌟LIST OF GOOD SME IPOs LISTED FROM 01 Jan 2026 (Sheet 1, Sheet 2 & Sheet 3)
🗒️Data Covers: IPO Price, IPO P/E, List Price, Current Price, Current P/E, % Gain with respect to IPO Price. For most recent stocks, Capex Completion target time is given in Comments.
🩷LIKE, SAVE in 🔖BookMarks for Detailed Study
Some stocks start discounting future earnings , very early, considering capex. But not all. If price is still at lower valuation, BUT major capex is ongoing, it's an opportunity to track and enter, when price action starts. 👍
Suggest not to take Promoter's every word in Investor presentations, as Ved Vakya. Lot of fluff and inaccurate stuff will be there in their talks. 👎
Please go through recent NSE order announcements / capex status / business updates too before investing.👍
Do note , even some of these stocks could fail, 👎since we are yet to see First Post-Listing Financials. And there can be cooked up 👎revenue and extra high margins which could disappear with H1 result. So one has to track results closely. No blind bets.
SHEET 1
ACME INDIA INDUSTRIES
TNA SOLUTIONS
EVERESTIMS TECHNOLOGIES
SJP ULTRASONICS
VANS ELECTROENGINEERING
ACME UNIVERSAL SAFEZONE 9
ROOPA SCREEN
POOJA LOGISTICS
FX MULTITECH
ROBOKIDZ EDUVENTURES
SPECTRAA TECHNOLOGY SOLUTIONS
RAKSAN TRANSFORMERS
MAHARAJA & SPEEDEX INDIA
AMTECH ESTERS
QUALIANCE INTERNATIONAL
ASHUTOSH FIBRE
🩷LIKE, SAVE in 🔖BookMarks for Detailed Study
Sheet 2 and Sheet 3 in Thread below 1/3
💠 Continuing the coverage from Arihant Capital’s Bharat Connect Conference 🚀🚀
👉 Bringing more management insights from the next batch of emerging SME & microcap companies.
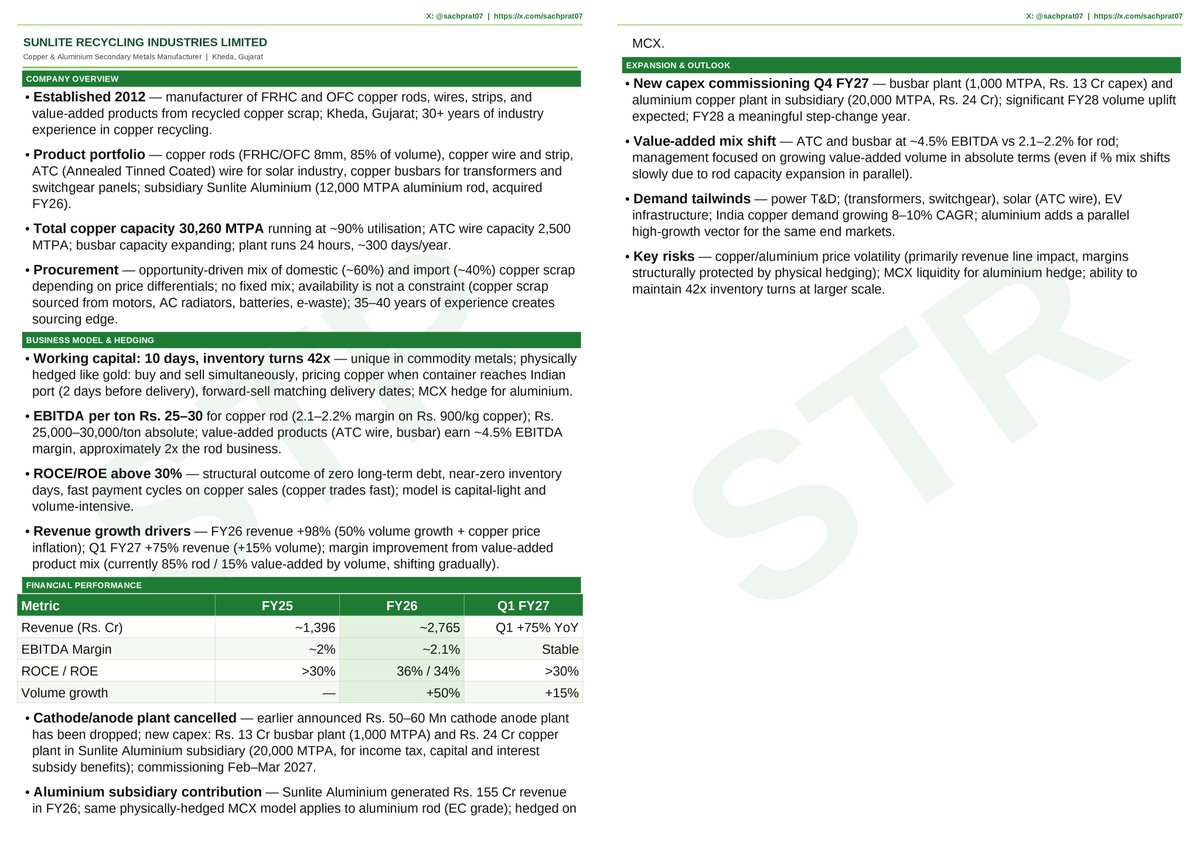
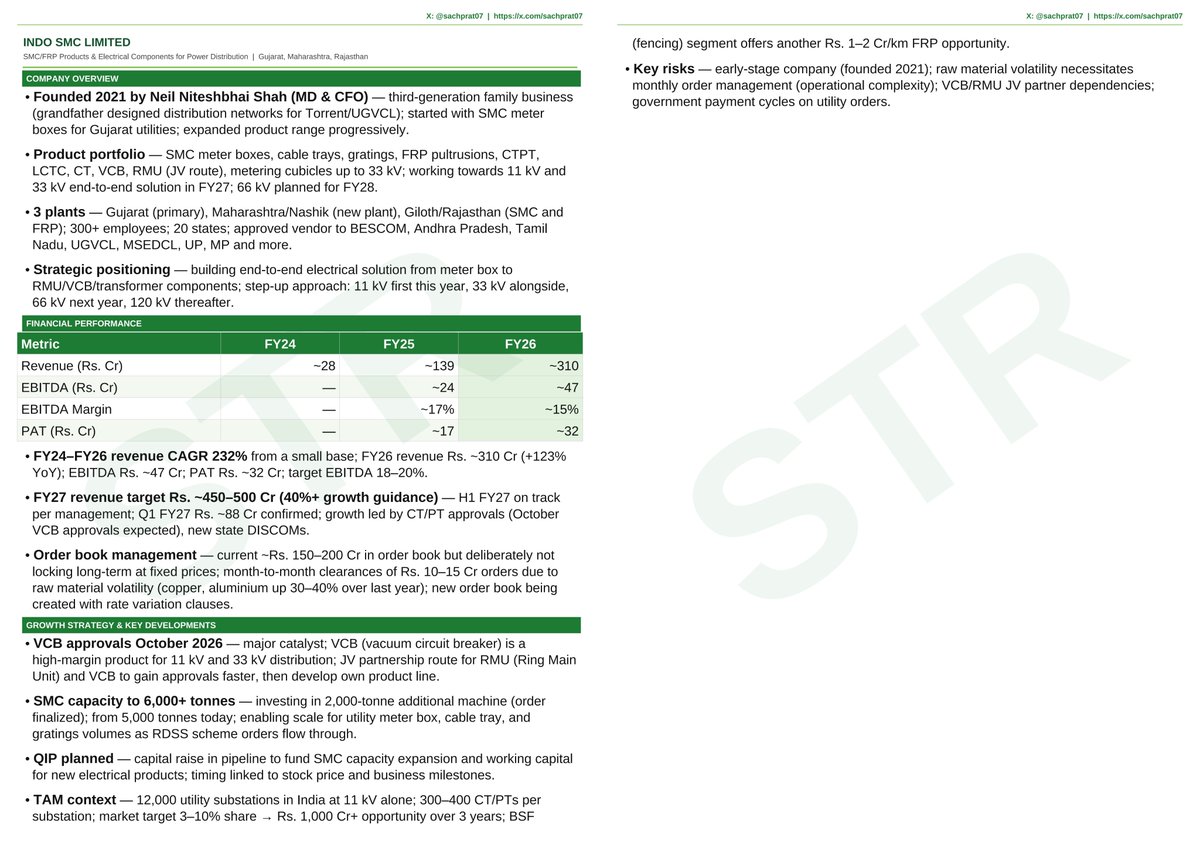
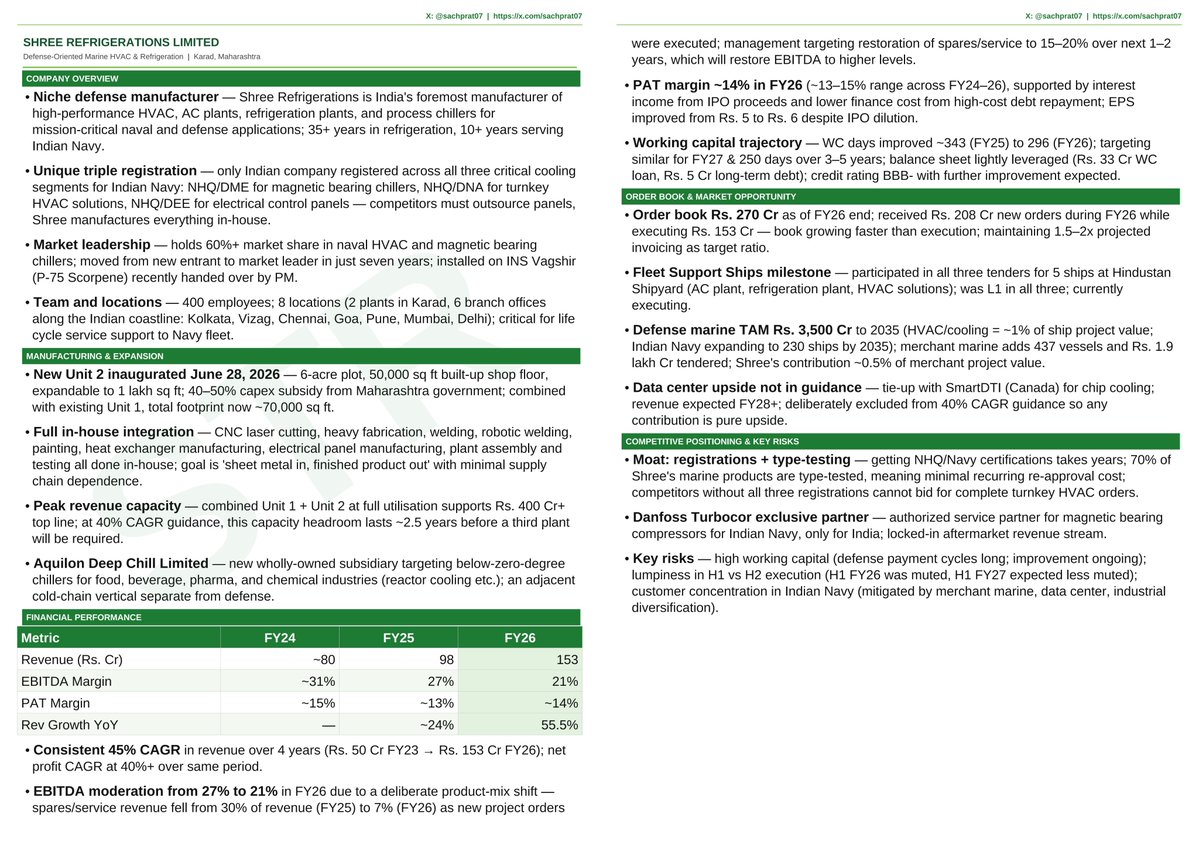
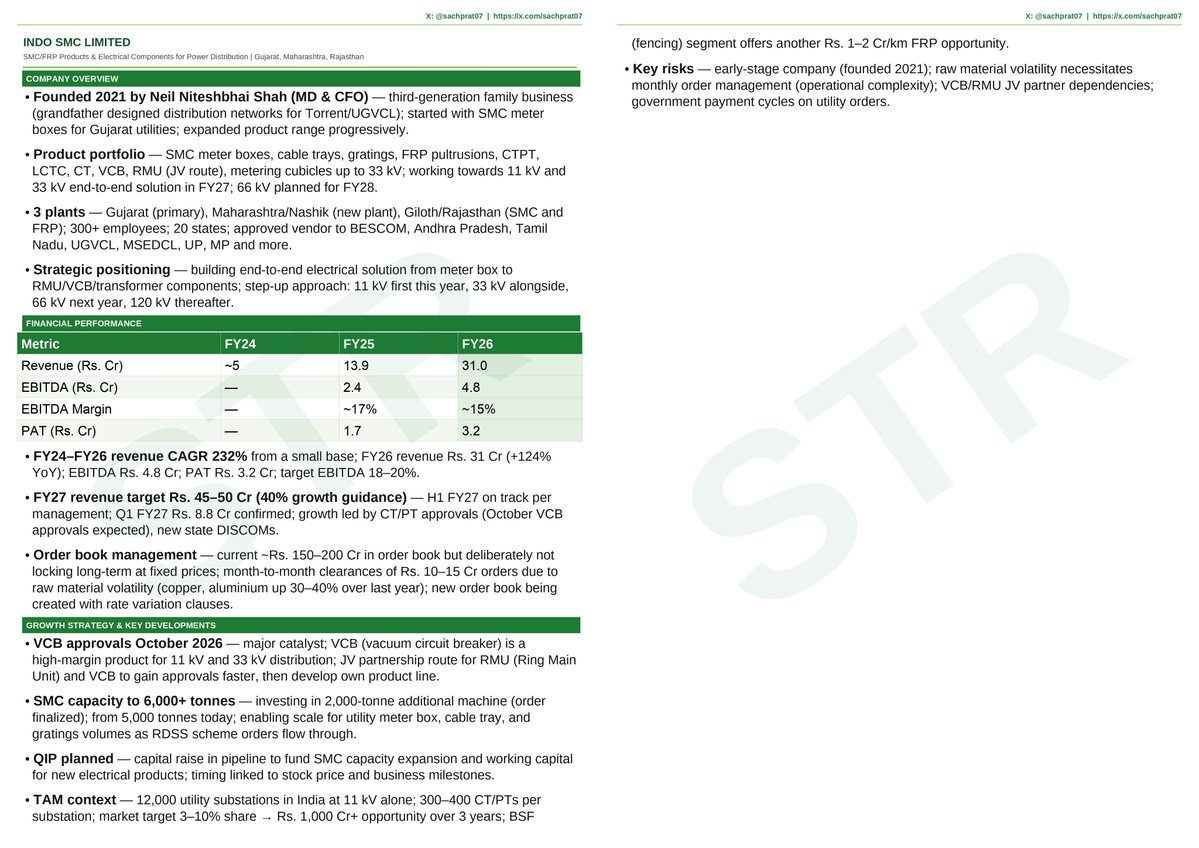
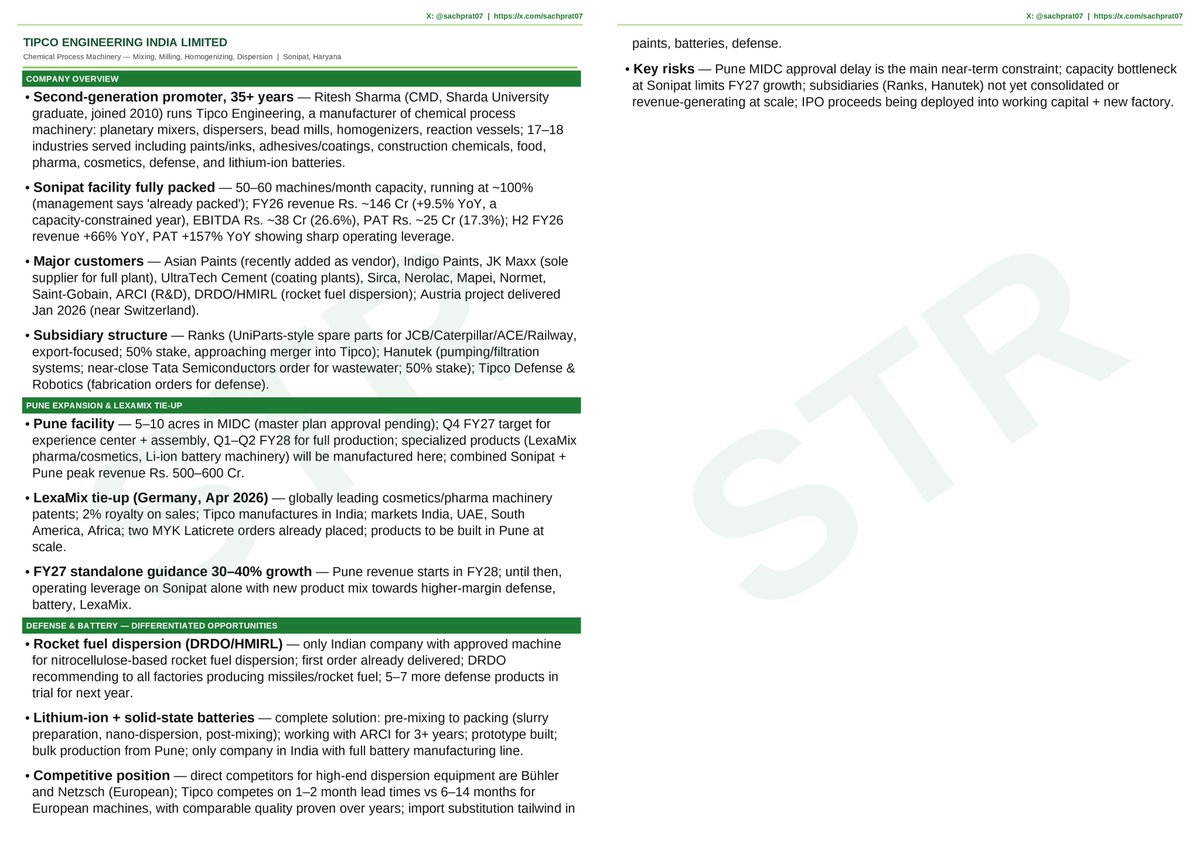
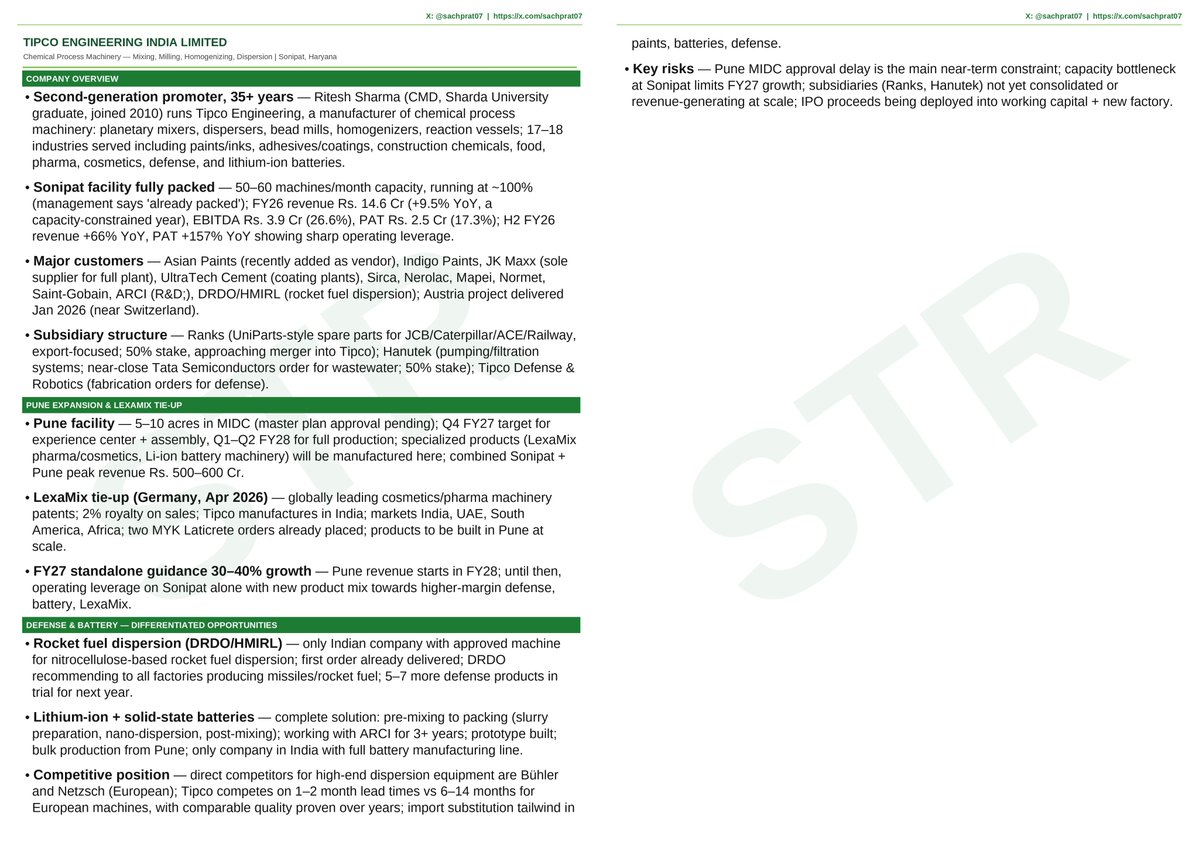
👉 Note: Due to some compilation errors in the financial figures previously, Shree Refrigerations, Indo SMC, Sunlite Recycling, and Tipco Engineering are being attached again to ensure data accuracy.
👉 And like last time, do point out any errors or corrections; if you spot them !!
👉 Stay tuned for more insights from Day 2-4 ⏳⏳
👉 Combined Coverage Day 1 Part 2 :
#ShreeRefrigerations
#IndoSMC
#SunliteRecycling
#TipcoEngineering
#AVPInfracon
#ClayCraft
#GulshanPolyols
#HRHNextServices
#PajsonAgro
#KarnikaIndustries
#ShriKanhaStainless
#VirtualGalaxyInfotech
#PaluckTechnologies
#NeochemBioSolutions
#CanarysAutomations
#DachepalliPublishers
#SathlokarSynergys
#VishnusuryaProjects
#SrivariSpices
#AllETechnologies
#PNGSGargiFashionJewellery
#IndianPhosphate
#LeadReclaim
#InflameAppliances
🤖 A Vijay Kedia-backed EdTech company is coming to BSE SME next week.
Robokidz Eduventures builds Robotics, AI and STEM labs for schools across India.
IPO opens 21 Sept. Here's why it caught my eye 🧵👇
Marquee investor Vijay Kedia holds a 7.02% pre-issue stake through Kedia Securities Pvt Ltd.
And this is a 100% fresh issue with no OFS. Every rupee raised goes into the business, not to existing shareholders.
The growth is hard to ignore 📈 (₹ lakhs)
Revenue: 3,817 → 5,875 → 9,322
PAT: 242 → 498 → 1,006
(FY24 → FY26)
That's ~2.4x revenue and ~4x profit in just two years.
Margins are expanding every year:
EBITDA: 12.8% → 15.2% → 17.8%
PAT: 6.4% → 8.5% → 10.8%
Debt-to-equity has come down from 3.26x to 1.19x, and FY26 ROE is 56%
Strong visibility 🔭
The outstanding order book is ₹75.29 Cr (as of 3 Sept 2026), roughly 80% of FY26 revenue already lined up.
The model is smart:
Lab setups get them into schools (77% of revenue).
Subscriptions and services keep them there.
Subscription revenue grew from ₹2.1 Cr in FY25 to ₹11.9 Cr in FY26, about 5.7x in one year 🔁
It's no longer just a Maharashtra story 🇮🇳
Maharashtra's share fell from ~90% to 53% as other states grew.
Delhi alone contributed ~20% in FY26.
The company is present in 25+ states.
What sets them apart:
✅ In-house https://t.co/3Ifm8m2lcW coding platform, LMS and RC app
✅ Made-in-India kits (Autobotix, Mechbotix, Grabot and more)
✅ ESSCI-recognised training provider
✅ Atal Tinkering Labs work since 2017
✅ Young Engineers Academy franchise, with 4 centres live
*Big tailwinds* 🌊
NEP 2020 is pushing hands-on, skills-based learning.
The global educational robot market is projected to grow from $1.38B (2024) to $5.84B (2030), a 28.8% CAGR (per the DRHP).
IPO snapshot 📋
🗓 21–23 Sept | Listing 28 Sept (BSE SME)
💰 Price band ₹100–106
📦 Size ₹31.09 Cr
🎟 Min 2,400 shares (₹2.54L at the upper band)
🎯 Proceeds go to working capital (₹23.46 Cr) and debt repayment (₹2.2 Cr)
EdTech + robotics + a Kedia-backed cap table. One to watch 👀
Disclaimer: Not investment advice. SME IPOs carry higher risk, so read the RHP before applying.
#IPO #SMEIPO #VijayKedia #EdTech #Robokidz
Massive bull run about to hit #sme segment
While there will be some pullbacks in between
But this time expecting a massive 2 years breakout and the chart of BSE SME Index also reflects the same
This is the time to enter and sit in long term sme stories which will become 6x-10x in upcoming 1-2 years
Personally expecting massive inflow of liquidity in many of the quality names which delivers the results.
No buy sell recommendation
💠IPOs / SMIDs are buzzing and within them the SME space continues to show incredible resilience and momentum! 🚀🚀
👉 A sincere effort to distill management insights and fundamentals from a stellar lineup of emerging companies via Arihant Capital’s Bharat Connect Conference 🏦
👉 A gentle reminder to keep analysing, track leadership execution, and sharpen your research; especially in the microcap & smallcap universe. 🪙💰
👉 While care has been taken to ensure accuracy, errors do happen—point them out or correct them if you spot any !!
💠 Stay Tuned for more insights ⏳⏳
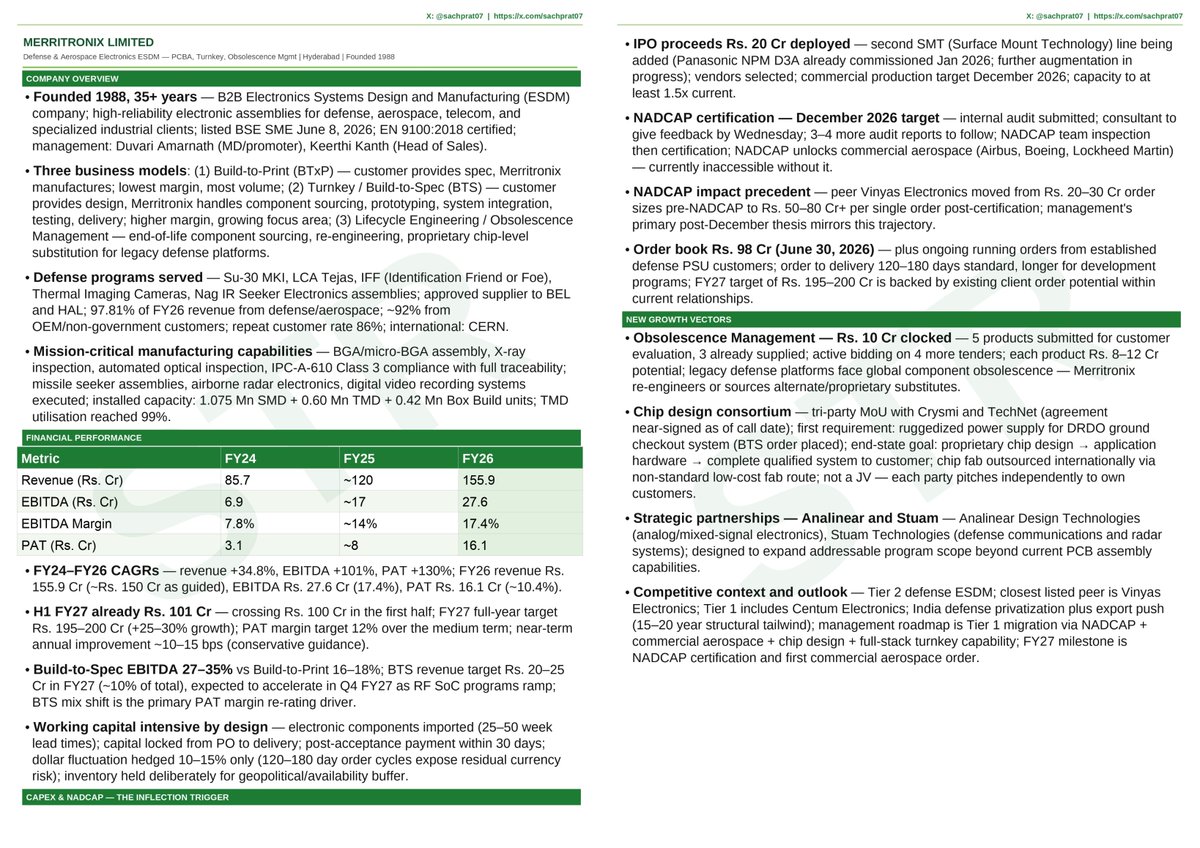
💠 Combined Coverage Day 1 Part 1 :
#ShreeRefrigerations
#Merritronix
#IndoSMC
#TipcoEngineering
#AccordTransformer
#InfluxHealthtech
#NamoeWaste
#NeetuYoshi
#PrimeCableIndustries
#SystematicIndustries
#TechnocratsPlasma
#TelgeProjects
#UnihealthHospitals
#VilasTranscore
#BahetiRecycling
#EnergyMissionMachineries
#GaneshInfraworld
#GenxAIAnalytics
#GrandContinentHotels
#Identixweb
#Infollion
#JDCables
#KhazanchiJewellers
#MadhusudanMasala
#PuneEStockBroking
#SunliteRecycling
#TridentLifeline
#DivinePowerEnergy
#arihantbharatconnectconference
#bharatconnectconference #arihantcapital
Our Love 💎 INDO-MIM 💎 Is Making Us To Go Wow 😍
Stock Hits Whooping 1200+ 🚀
One Of The Greatest, Fastest & Biggest Jackpot Money Minting Ride Is Here For You All... Ofcourse Sponsored By Us 😉
Right From Listing Zones Of 700 To Till 950 Repeatedly Shouted To Don't Miss This Bullet Train Ride & Now See How World Is Mad For It!!!
Hope You All Loving My Conviction 😎
Keep Showing Your Love & Support Folks ❤️
#IndoMIM
CDMO - In a massive bull run
Companies in this sector will go up massively
I will cover this in details and opportunities available in this sector in next post
#cdmo