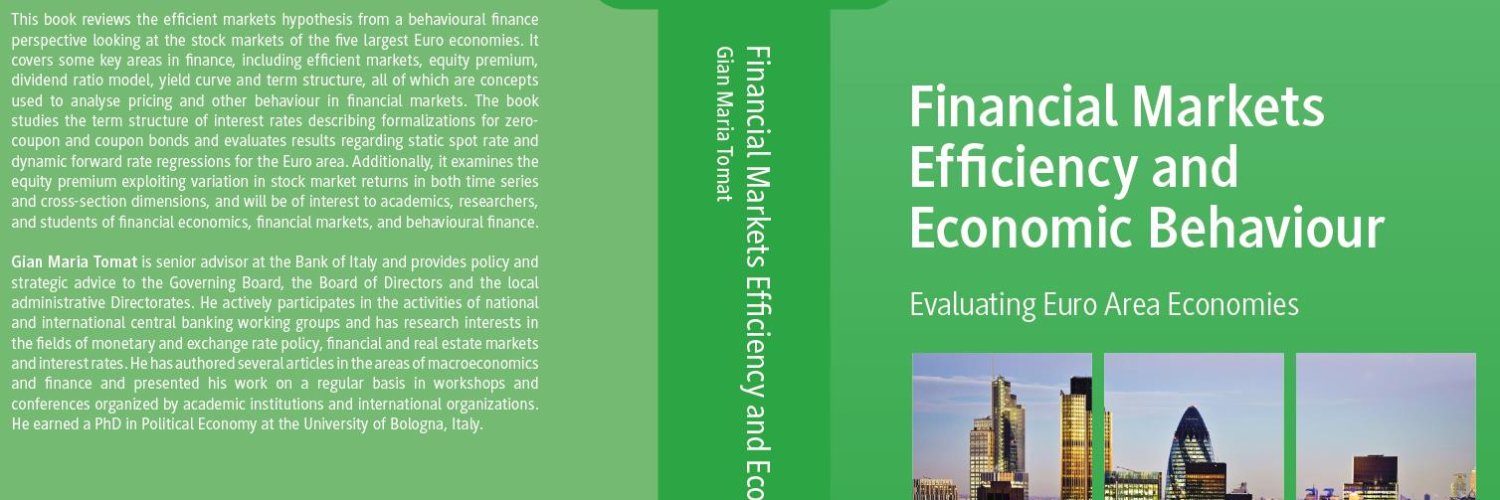
In a recent work I review my research on financial markets #efficiency and #econometric evidence for #Euro area asset, fixed income security and housing markets, in a #behavioural perspective. The softcover edition is now out: https://t.co/MAJmn0JJF4.
@SpringerNature@Palgrave
Euro area #inflation expected to be at 3.3% in August 2026, up from 2.9% in July 2026. Components: energy +14.3%, services +3.0%, food, alcohol & tobacco +1.2%, other goods +1.2% - flash estimate https://t.co/vf2IVGZB5C
Interesting to read @GitaGopinath’s opinion on US tariffs. While I share her views, the perspective we have of a broad support for these measures in the American economics profession, or at least that is my take from a number of recent talks at the Bank of Italy, is striking.
In my summer readings ‘Nexus’ by @harari_yuval provides essential insights that should seriously be considered worldwide, when thinking about the prospects that are currently being brought by #AI technology innovation and its possible applications.
https://t.co/PARC0BOvHR
Florence’s monetary system was bimetallic, with a gold coin, the florin used in international trade, and silver ones, grosso and denaro. A gold inflow from Asia, leading to its depreciation against silver, was a factor behind the XIVth century crisis.
https://t.co/ZcK4Ie6B8I
While we have recently lost members, integration matters most. Gradual forms of accession conditioned on the consequences for the EU decision process could be a way forward.
‘It’s now or never.’ Is the EU serious about letting in new members? https://t.co/8Vi9AdH2xA via @ft
There was a significant rise in #Eurocoin in July, due to improving business and household confidence according to our staff. We may be heading in the right direction, although we will have to work further to find a new normal.
#Eurocoin rose to 0.54 in July (from 0.39 in June). The indicator benefited from the improvement in business and household confidence, especially in forward-looking assessments.
👉 https://t.co/gczAXpuHZu
Considering the sheer size of China’s economy, this is not an easy issue. The lower growth path to rebalance China’s economy should be followed with redistribution of income to households. Corporate profits could work, although we are talking about a different structure here. 😁
The Chinese yuan is no doubt undervalued. But demanding that China revalue the yuan gets both the diagnosis and the cure wrong. Our piece, with @pogourinchas & @helene_rey in the @TheEconomist is out: https://t.co/DB8pOQdF6b
What will the new euro banknotes look like?💶
The @ecb is redesigning euro banknotes and citizens all across the EU are invited to take part in the survey to help decide on the final look.
You have time until 21 September 2026 to share your opinion: https://t.co/aLZExnw5f1
The @ecb has unveiled ten proposals for the new series of euro banknotes. The making of banknotes is a very fascinating subject and a nasty business for central banks. I would suggest studying the proposals as a summer reading, for those with an interest in monetary economics.
Ten selected design proposals for the next series of euro banknotes have been unveiled.
Explore the proposals and tell us which ones you prefer.
Have your say https://t.co/VvcczFFxX3
Today we kept our key interest rates at their current levels.
We are well positioned to cope with the uncertainty created by the conflict in the Middle East and the economy has been able to weather the difficulties so far https://t.co/mTcdgIbzkh
On the current AI frenzy and overconfidence it is interesting to read CEOs statements as: “It’s getting close to as good as it gets. We just don’t know how long it’s going to last.” While markets may be overconfident on future AI prospects, they price in high dividend growth.