Trades today:
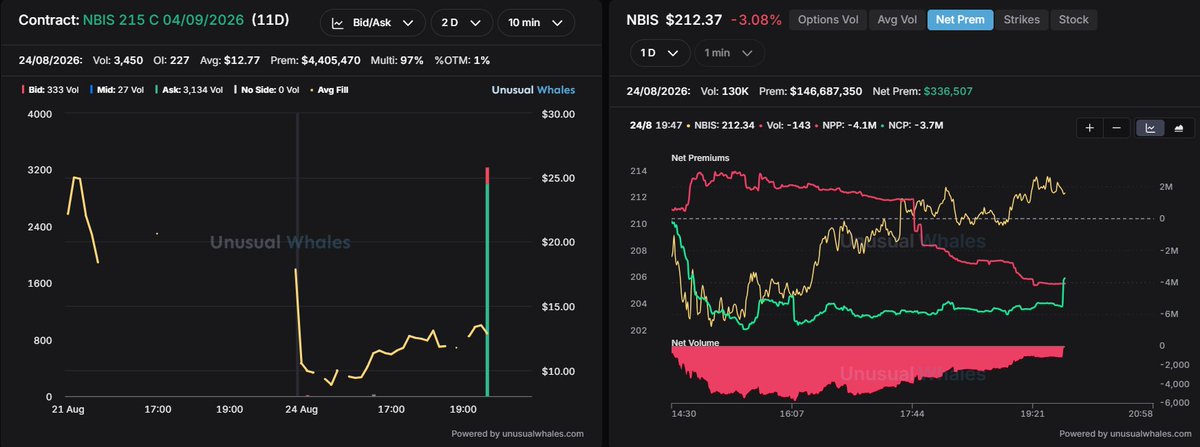
$NBIS 9/11 260C sold at 5.50, +$550.
Same shares that paid $640 last week on the 285C. Sold after earnings ripped, bought back 80% cheaper on the pullback, reloaded at 260 for the next round.
Second call on shares I was paid $1,140 to buy. Wheel keeps turning.
People see $NBIS raising $5B in convertible debt and exchanging $800M of old debt for 15.8M shares, and panic.
Those old notes already represented ~15.55M potential shares. 98% of that "dilution" was already reflected in the fully diluted share count.
In return, Nebius wiped $800M off the balance sheet and saved $20M a year in cash interest (not a lot in the grand scheme of things, but better than nothing).
Effective conversion prices are set between $344 and $405 a share (conversion terms on the new $5B debt).
Future dilution only triggers if the stock rallies massively from here.
Yes, if the stock stays flat for years, the accretion penalty at maturity will hurt.
Lastly, this is less about short-term share-count bloat and more about who can fund the AI cloud-infrastructure race at scale.
$NBIS will take care of you.