"Being a founder is like riding a lion. People look at you and think, ‘Wow, that person's really got it together! They're so brave!' And you're sitting on the lion thinking, 'How the hell did I get on a lion, and how do I keep from getting eaten?'" - Toby Thomas, former CEO of EnSite Solutions.
(1/x continues ...)
Saipemʼs acquisition of Subsea7 is getting fresh scrutiny in Brazil while antitrust agencies around the world coordinate to examine the deal, CTFN reported.
Enforcers in Europe and Brazil are working together closely, along with antitrust officials in Australia and several African nations, as the deal consolidates two of the largest providers of subsea infrastructures, umbilicals, risers, and flowlines (SURF).
#mergers #antitrust #oilandgas #offshore #goldentriangle $SUBCY $SAPMF
$QGEN
While CTFN (@ctfn_news ) reporting suggests a potential takeout price in discussions of around $50 per share, Spitzer Data metrics show a potential valuation range up to the low 60’s.
Use our tools to easily generate your own estimates based on your chosen assumptions.
#corpfin #mergers
Following an M&A deal should be easy.
Here's how Spitzer Data's Live Metrics page brings live pricing, spreads, break prices, closing odds, etc. into one view.
Take a look ↓
Does your work touch M&A?
Save time daily with our tools.
Spitzer Data’s truly unique M&A database with dated, regulator driven events and outcomes has what you need.
Every deal we track carries a structured history of each agency's actions — FTC/DOJ second requests, EC Phase I/II, CMA Phase 2, SAMR, CFIUS, FSR — that you can screen instantly by event type, date range, sector, status and EV.
Do you want to find "recent second requests in non-therapeutic healthcare"?
This could take you a dozen web searches to assemble publicly. Fetch the output in seconds with Spitzer Data.
The five most recent second requests in non-therapeutic healthcare (services, devices, distribution, staffing — no pharma/biotech) are, for example:
1. Cencora (MWI Animal Health) / Covetrus — FTC second request, May 2026. $3.5B animal-health distribution merger; would cut national vet distributors from three to two. $COR
2. Boston Scientific / Penumbra — FTC second request, March 16, 2026. Medical devices (vascular/neuro). HSR filed Feb 13, second request ~30 days later. $PEN $BSX
3. Alcon / LENSAR — FTC second request, May 21, 2025. Ophthalmic surgical devices (laser cataract systems). $ALC $LEN
4. CrossCountry Healthcare / Aya Healthcare — FTC second request, February 20, 2025. Nurse staffing. (The deal ultimately died.) $CCRN
5. Owens & Minor / Rotech — FTC second request, October 11, 2024. $1.36B home medical equipment deal — terminated in 2026 after regulatory clearance "proved unviable."
Get the list with a few keystrokes. You can prompt in plain language.
Same goes for other regulatory histories, such as CFIUS (seven dated clearance events this year, for example, across energy, gaming, insurance and media), which can be found instantly.
For law and finance broadly, Spitzer Data is the most universally useful single tool for public company M&A.
For investors, along with precedent info, find one-line live deal summaries and full one-page situation summaries, tracking and analysis. See relevant spreads, break prices, instant market-implied probability of any live deal closing, comps, closing date estimates, and more.
#mergers #corpfin
Total value of ongoing deals per target sector:
Consumer, Retail & Leisure: $276.9B
Energy & Resources: $253.9B
Media: $159.0B
Healthcare & Life Sciences: $153.7B
Industrials: $145.9B
With all the attention on Media M&A this year, are you surprised it isn't higher on the list?
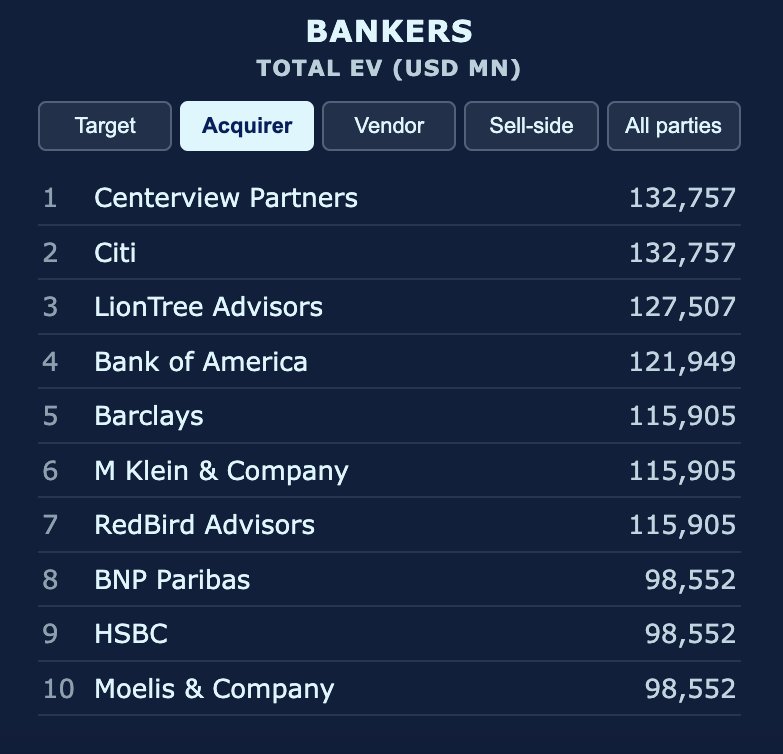
Media M&A banker league table since 2022. Top acquirer financial advisors ranked by total EV. Centerview and RedBird being on the list isn’t too surprising given the size of the $WBD / $PSKY merger.
Which firms will take on the next big media deal?
Per Bloomberg:
"Behind the scenes, Newsom was also active, serving as an unofficial mediator in settlement talks, some of the people said."
Post below not terrible in light of that.
CTFN is delighted to announce that Will Cain has joined our team and will sit in our London office. Will's expertise brings additional coverage to European pre-event and PUSU situations, along with a seasoned analyst's perspective on the M&A and event-driven space. CTFN subscribers may schedule a Direct Consultation to connect with Will when they have questions about his reporting.
#MergersAndAcquisitions #EventDriven #LondonBusiness #MarketIntelligence
Warner Bros/Paramount:
Our algorithm swapped out DISH for CHTR in the comp set (the 43% attributable to cable & satellite TV comps) post Cox/Charter, but this contributed to moving the estimated break price down from $7.76 to $7.19.
Is it a reasonable swap?
The Spitzer Data platform allows you to use pre-loaded comps from our industry classification framework or swap out your own, and vary your other assumptions as well.
Presently the all-in annualized spread to the estimated closing date of June 1 is 17.5% vs gross downside of 74%, suggesting market-implied odds of closing are 85%, notwithstanding the states’ lawsuit.
These odds are roughly flat from mid August. But again, you can adjust assumptions on our platform per your own research and recalculate.
$WBD $PSKY #mergers #corpfin
Between fund management and personal investing, I’ve looked at thousands of businesses.
One uncomfortable reality is that 99% of them are just companies - good people with a reasonable product, doing the best they can. This is absolutely admirable and important to the economy.
Maybe 1% are truly special. And usually, that’s because they have the courage to focus and also do the fundamental things exceptionally well.
Unfortunately, this also makes it hard to explain exactly what makes them special. There is an element of just knowing it when you see it.
Spending your time learning to identify these companies is the highest-return activities an investor can pursue.
Since Aug 21 $TXNM’s break price has drifted higher.
The break (before taxed reverse-termination fee) has recovered to $50.26 from $46.45, so gross downside tightened to 12.84%.
Net picture: 6.2% gross return / 11.8% annualized against a near-50/50 close and a 5/31/27 closing estimate.
Want to try this exercise with different comps or a different undisturbed date or closing date?
Our tools let you adjust and even provide suggested comps or let you pick your own.
$AUC.AU $AUSGF
Ausgold trading near deal terms (or arguably slightly through).
Closing likely mid Dec.
Deal risk seems low other than shareholder vote which looks more like bumbertrage than deal break.
Gadfly/activist Jeremy Raper (@puppyeh1) says deal is unnecessary and struck too cheap. He also questions selling to a Canadian-listed miner that left the ASX.
In his words: “Approximately 55% of this register is Australian, including roughly 41% retail. What exactly are those shareholders being offered in this transaction? Compulsory exposure to a Canadian-listed entity that no shareholder asked for or wanted.”
On valuation he writes: “At spot, the first four years of production represent roughly A$560-590M per annum of pre-tax cash margin: the Company is being sold for approximately 1.3 years of that margin — below its own 52-week high, and far below both published broker valuations (Canaccord, A$3.45; SCP Resource Finance, A$2.65).”
Nevertheless, one argument against greater value is that Katanning is not in the traditional Western Australia goldfields, meaning no nearby mill to feed or existing circuit. On the other hand, being situated in the agricultural Wheatbelt means there is existing infrastructure (roads and water) and even a workforce that may not need as much remote support.
Meanwhile, quick sector review yields a list of credible possible alternative buyers, though there are reasons why none may be interested.
So it seems the most likely course of events will be determined by shareholders’ views and whether they are happy with the deal terms or if they instead have the conviction to withhold votes in an attempt to force a higher offer.
Approval needs at least 75% of votes cast and a majority by number of holders voting.
The jumping off point for my research above was Spitzer Data.
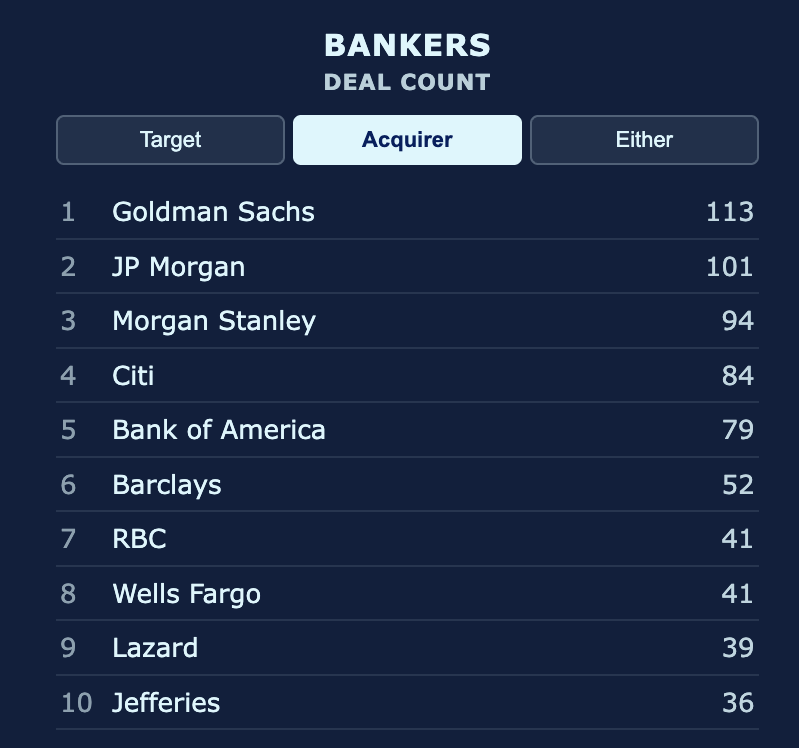
Went to Spitzer Data's league tables and looked at the top 5 banks advising acquirers since 2022 by deal count: Goldman Sachs, JPMorgan, Morgan Stanley, Citi, Bank of America.
Came back to the M&A Database and pulled which of these banks had the lowest average EV/EBITA ratio each year for the last 5 years:
2022 - JPMorgan: 16.7x
2023 - Goldman Sachs: 8.9x
2024 - Citi: 10.0x
2025 - Citi: 11.1x
2026 - Goldman Sachs: 13.5x
Did these surprise you? Come back tomorrow to see who had the highest each year, or look for yourself on https://t.co/291OrFB7LO
Vestis, the uniform-services company spun off from Aramark in 2023 and one of the industry's “big three” alongside Cintas and UniFirst, hired its own Washington DC lobbyist to amplify its concerns about the UniFirst/Cintas merger, CTFN reported.
$VSTS $UNF $CTAS #mergers #antitrust #businessservices
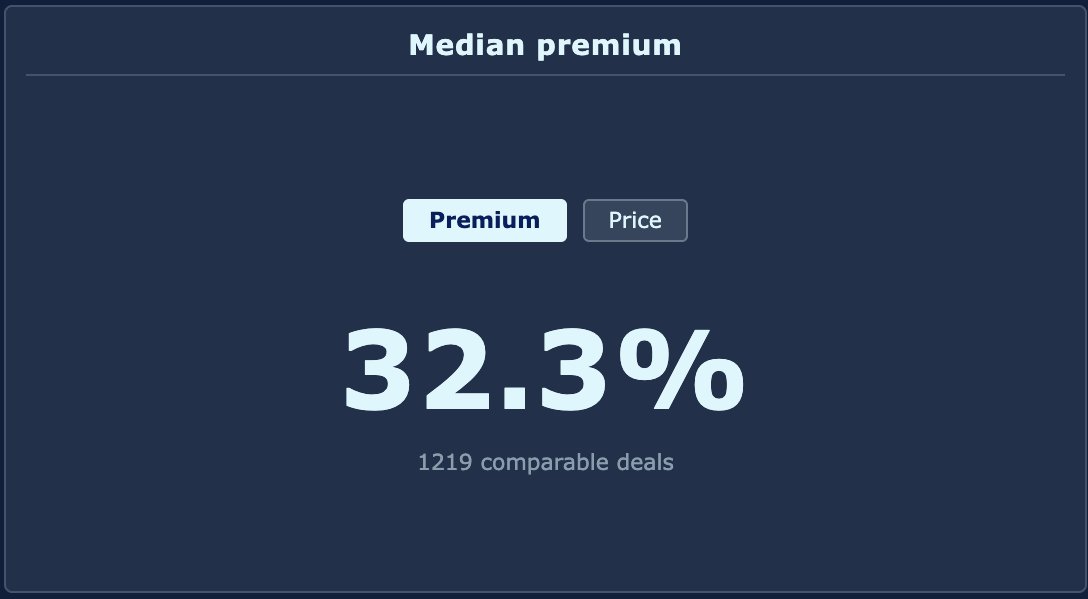
A 30% acquisition premium might look expensive in one sector and completely normal in another.
Median premiums in our database:
Healthcare: 40.5%
Industrials: 35.0%
Consumer: 31.8%
Financial Services: 25.3%
A good reminder that the right precedent set matters.
You can dig into the transactions behind these numbers on Spitzer Data.
#MergersAndAcquisitions #CorporateDevelopment
A Montana judge has ruled that state Public Service Commissioner Brad Molnar will be required to serve out his one-year suspension without pay stemming from allegations of workplace sexual harassment and retaliation against commission staff.
Lewis and Clark County judge Mike Menahan wrote in a 21-page order that he was unpersuaded by Molnar’s claim that he was not given a chance to defend himself before governor Greg Gianforte suspended the elected commissioner last July.
“Molnar was given multiple opportunities to participate in the investigation prior to suspension, which he denied,” Menahan wrote. “Rather than engage in meaningful dialogue, Molnar chose to attack the process. His due-process rights were not violated.”
Molnar, a Republican whose district encompasses south-central Montana, had been a vocal critic of the pending merger of NorthWestern Energy and Black Hills Energy.
Molnar, who chaired the MPSC from January to October 2025, has contended that one reason for his confrontation with fellow commissioners is his opposition to the pending merger. A decade ago, he voted to deny NorthWestern’s plans to merge with an Australian company.
The governor last week named Kirk Bushman, a Republican who had served on the MPSC from 2013 to 2016, as Molnar’s temporary replacement. Bushman will serve through July 8, 2027.
$NWE $BKH #mergers #utilities #infrastructure
Largest potential downsides to break prices (including taxed reverse termination fees) for public deals globally with an EV $12.5bn and above:
Warner Bros/Paramount 66.2%
Telecom Italia/Poste Italiane 63.0%
Delivery Hero/Uber Technologies 56.8%
Caesars Entertainment/Fertitta Entertainment 36.2%
Schroeders/Nuveen 35.8%
InPost/Advent 35.6%
Segro/Prologis 34.5%
See break price estimates for all deals in developed markets worldwide $100mn and up at Spitzer Data.
#mergers #corpfin
Dear Corporate Development officers,
Your bankers do a ton of work for you, digging up precedents, showing you comparables, analyzing timelines for similar deals, doing quick valuation estimates.
How would you like to have the tools at your fingertips to understand all of this and more?
It’s easy with Spitzer Data, the ultimate M&A database.
Deal histories, live deal trading dynamics (with news flow and filings) - in short, everything you need.
Reach out today to schedule a quick tutorial.
#corporatefinance #mergers #data