Robotics VC just hit an all time high at over $16 billion in a single quarter. The smart way to play it is not guessing which robot wins. It is owning the parts that go inside every single one of them.
Here is an easy way of playing that with some robotics and memory stocks.
The brain. $AMBA makes the edge AI chips that let a robot see and process the world in real time without the cloud. No brain, no robot.
The eyes. $OUST makes the lidar that lets a robot perceive depth and navigate the physical world. The eyes are not optional.
The sense of touch. $VPG makes the force and pressure sensors that let a robot feel how hard it is gripping. Picking up an egg without crushing it takes force feedback.
The memory. $DRAM gets you the memory makers, and every robot running real time AI on device needs a massive amount of it.
When the VC money floods in like this chart shows, it flows to the robot companies. But the suppliers get paid no matter which robot wins.
People are talking about $AAOI being in a distribution formation.
But, most the time, distribution turns into accumulation.
Let me explain:
I'll use $OPTX as an example here (but it is the same with any stock that looks like this):
The stock accumulates for a bit.
It has a breakout, then goes into distribution (selling off).
But eventually, it goes into another accumulation (once it hits support) -> (which leads to a) breakout.
Almost every chart has this.
It is the natural state of human psychology.
Especially when the company is only performing better.
This is what is happening to some names we know.
Think $ASYS, $OPTX, $AAOI, etc., now is not the time to be selling imo.
So, as people scream about "we're in a distribution zone here," remember, distribution turns into accumulation which turns into a breakout.
The accumulation is coming, then the breakout will happen.
With due time.
Few...
June is almost over.
Overall, a very successful month for my Short-term Portfolio in terms of trades completed.
The vast majority closed green, with 11 of 12 trades finishing in profit. Only one ended slightly in the red.
A few notes for context:
- These are the completed trades from my Short-term Portfolio.
- $HIMS and $OUST were moved over to my Long-term Portfolio, so I'll be holding those going forward.
- $PENG appears twice because I reduced my position in two separate trades.
- Some of these were stocks I bought back in May and sold in June, so the gains reflect positions held across both months.
- 11 of 12 trades closed green. Roughly a 92% win rate for the month.
- Currently own 8 stocks in my Short-term Portfolio.
DELPHI DIGITAL JUST DROPPED THEIR 2026 STATE OF THE TOKEN MARKET
HERE'S THE TLDR:
1/ 2024-25 had every ingredient of a bull market. But for altcoin holders it was one of the most dilutive periods in crypto history. Institutional money went to BTC and ETH. Everything else got left behind.
2/ Of tens of millions of tokens minted this cycle, only ~1,700 (under 0.01%) generate $250K+ in daily volume. The long tail is basically a graveyard.
3/ Buying every CEX listing from Jan 2025 destroyed $329K of every $652K invested. Median return: -82%. Gateio alone listed 348 tokens, more than the other four exchanges combined, with an 85% loss rate. Volume without curation was the whole business model.
4/ Most tokens spend their entire lifetime below their launch price. L2s are the worst, 80% of lifetime underwater. Consumer crypto is a lottery ticket. CEX tokens are the only cohort that actually got better over time.
5/ For most tokens in 2025, doing nothing beat buying and holding. Only tokens with real structural buyers on the other side (HYPE, SKY, ZEC, XMR) consistently held. Everything else just bled.
6/ Most VC-backed tokens launched this cycle are below their launch price. The worst are down 90%+. Inflated FDV, low float, brief pop for insiders and airdrop farmers, then relentless sell pressure as unlocks kick in. Holders have no revenue claim, no floor. Death by a thousand cuts.
7/ $TRUMP launched Jan 17, 2025. Peaked +576%. Collapsed. Took the whole memecoin category with it and the liquidity never came back. The Memecoin Index is down 75% since. 64 weekly rebalances across dozens of tickers couldn't fix it.
8/ Only 6 memecoin names held continuously since Jan 2025: BONK, WIF, FARTCOIN, FLOKI, PEPE, SPX. Everyone else is a round-tripper or dead.
9/ Launch FDVs fell 85% from Q1 2024 to Q1 2026. Still wasn't enough. Tokens lost another 30-80% in the 6 months after TGE anyway. The market reprices faster than teams can launch.
10/ Unlocks don't just hurt, they compound. Each event erases ~7% excess return vs BTC in the surrounding 3-week window. 28 of 33 tokens underperform BTC at every single unlock. Worst offenders: PEAQ -19.8%, VENOM -18.6%, W -15.6%, ZK -15.1%, ANIME -12.0%. The problem isn't the unlock. It's that the next one is 30 days away.
11/ Launchpads vs CEX: at 7 days every launchpad cohort is green, every CEX cohort is already underwater. The one exception is MetaDAO, where Futarchy governance let holders vote to unwind and receive $0.822 back on a $0.80 sale. A floor no CEX listing has ever provided.
12/ Airdrops are structurally dead. Sybil cost is now zero in an agentic world. Legitimate issuers can't legally do them. The CAC math is catastrophic (ARB alone paid ~$1.36B to users who left within a month). The ones that worked (Hyperliquid, Jito) were coincidences, not templates.
13/ Token holders have no rights when it matters. Pumpdotfun, SOL Strategies, Circle, Coinbase all did acquisitions this cycle. In every case equity captured the value. Token holders got nothing or close to it. Until token rights are legally enforced, holders rely entirely on team goodwill.
14/ The DAT premium is gone. Of $104B across 59 pure-play DATs, Strategy alone holds $63B. The other 58 trade at a median 0.81x mNAV and 36 of 59 trade below the actual value of their crypto holdings. The staking yield edge over ETFs is gone. MARA is already selling BTC. The deleveraging cycle has started. Strategy was the only real winner of that model.
15/ Revenue-weighted portfolios returned +30.6% since Jan 2025. BTC -17%, ETH -35%, SOL -58% in the same period. Cash flows beat narratives. It's not even close anymore.
16/ Fundamentals were always priced in. The market just took two years to prove it. CEX tokens, the only category backed by issuers with measurable recurring revenue, trade at 8.9x the broader market at the 2-year mark. L2s collapsed to 0.16x. The data sorted what narrative couldn't.
17/ The fee switch era is here. Between late 2024 and early 2026, every major DeFi protocol with real revenue either launched with value accrual or voted it in. HYPE, SKY, AAVE, JUP, PUMP, MET, UNI, PENDLE all flipped. "The fee switch didn't arrive. Teams stopped fighting it."
18/ But buybacks alone don't save a token. HYPE +533%. SKY +25%. AAVE -25%. JUP -40%, despite having the highest buyback yield in the set at 18.83%. Token-specific pressures can overwhelm any buyback program. "Buybacks are the mechanism. They are not the moat."
19/ The math shows why. Aave barely covers its own emissions (0.90x coverage). Jupiter is overwhelmed: $3.70 in unlocks for every $1 bought back (0.26x coverage). You can't buyback your way out of a broken token structure.
20/ The ETF holder base quietly rotated. Brevan Howard -27%, Tudor -72%, Hunting Hill -97%. All basis-trade unwinds. Who replaced them: Morgan Stanley +177%, BlackRock proprietary (brand new position, built to 51.4M shares), Mubadala/Harvard +54%. Advisors up 204%, sovereigns and endowments up 228%. The leverage trade left. Real long-term capital arrived.
21/ Emissions must become a function of performance, not time. Five mechanisms are emerging: performance-gated unlocks, retroactive supply destruction, supply-cut governance, fair-launch structures, and liquidity-adjusted vesting. Before 2025 the trigger was a calendar. Going forward it should be earnings.
22/ The protocol scorecard is brutal. HYPE passes on everything. AAVE passes on nearly everything with a partial on value accrual. JUP and PUMP fail on emissions. PLUME and BEAR fail on product, revenue, and emissions. TAO has narrative but no revenue. Most tokens have not earned the right to exist as investment assets yet.
23/ The market stopped buying stories. KAITO -76%. PLUME -94%. BERA -94%. LINEA -87%. All had great narratives, none had traction. HYPE, AAVE, UNI won because the numbers were real. "A clean story still helps. It just isn't enough."
24/ Memecoins that pretended to be revenue protocols got wiped. AI16Z -95%, ZEREBRO -96%, GORK -98%, ACT -98%. The survivors (DOGE, SHIB, PEPE, WIF/BONK, FARTCOIN) are the ones that were always honest about what they are. Tradeable attention. "The most interesting thing that can happen to memecoins is for them to become honest."
25/ The whole 2021-2024 era was crony economics. VC cap tables, governance-only tokens, calendar dumps, pay-to-play listings, retail as exit liquidity. All of it is being replaced. Fewer tokens, real revenue, holders with actual rights, and buyers who don't exit in 30 days. That setup has never existed in crypto before. Now it does.
These stocks will be the next 10x
The most mentioned tenbagger picks from my comment section ranked by the amount of likes:
1. $AMPG
2. $OUST
3. $AMBA
4. $VIVO
5. $ADUR
6. $EOS.AX
7. $DGXX
8. $NLST
9. $SIVE
10. $LIB.V
Let’s see how this plays out.
The AI infrastructure buildout is barely in its first innings.
Everyone on here is trying to figure out where in the stack they want to be.
Power. Compute. HPC DCs. Photonics. Memory. Networking. Cooling. Models/Apps.
Some of those layers I understand well. Some I understand just enough to be dangerous.
That is why I keep coming back to the most physical parts of the stack.
Land. Power. Buildings. Capacity. Hyperscalers and AI labs who need more compute than the world can currently provide.
That is $IREN to me.
The market spent years treating it like its old business, and probably still does to some extent until AI revenue really shows up.
I think the real story is power-backed infrastructure as compute becomes one of the scarcest resources on earth.
$DGXX is earlier, smaller and more execution heavy, but that is part of the appeal to me.
It feels closer to an early mini $NBIS style setup if they execute.
Same bet: compute demand is a 2 to 3 decade buildout.
The sheer deficit in compute gives me sleep at night comfort. That is why I have sized these names accordingly.
And dare I say it, I think this sector can 100x over the next few decades.
I think we are still early in figuring out who owns the real choke points.
People like @jiahanjimliu, @Agrippa_Inv and @FransBakker9812 are deeper in parts of this stack, but this is how I’m framing it.
The market pays for judgment, not hours.
But the “1 hour per month” only works after years of doing the reps, losing money, building pattern recognition, and learning what not to touch.
🚨FINAL WARNING:
If you’ve ever doubted $IREN, $NBIS, $CIFR here’s your sign:
Jon Gray is President and Chief Operating Officer of Blackstone Inc.
“It start with the picks and shovels, with things like chips, data centers and power at massive scale.”
“We have really focus on the right two circles here.”
Blackstone is the world’s largest alternative asset manager, with approximately $1.24 trillion in assets under management.
Strange thing about the internet is you can learn more in three days from the right strangers than you can in three years around the wrong people.
Good reminder to choose the room carefully.
Chips are still asymmetrical.
Photons are still asymmetrical.
GWs are still asymmetrical.
Memory is still asymmetrical.
Rockets are still asymmetrical.
Metals are still asymmetrical.
Drones are still asymmetrical.
Don't be a panican. Pick your infra.
OWN. IT.
Making yourself known online had some real downsides (one reason I'm anon too).
Look at all the crypto and rich people who get broken unto, robbed, and sometimes killed over their $.
It's a shame, and the #1 reason why I don't post portfolio values either.
No need to explain yourself bro, you're a great trader and we all value you here on X. 🙏
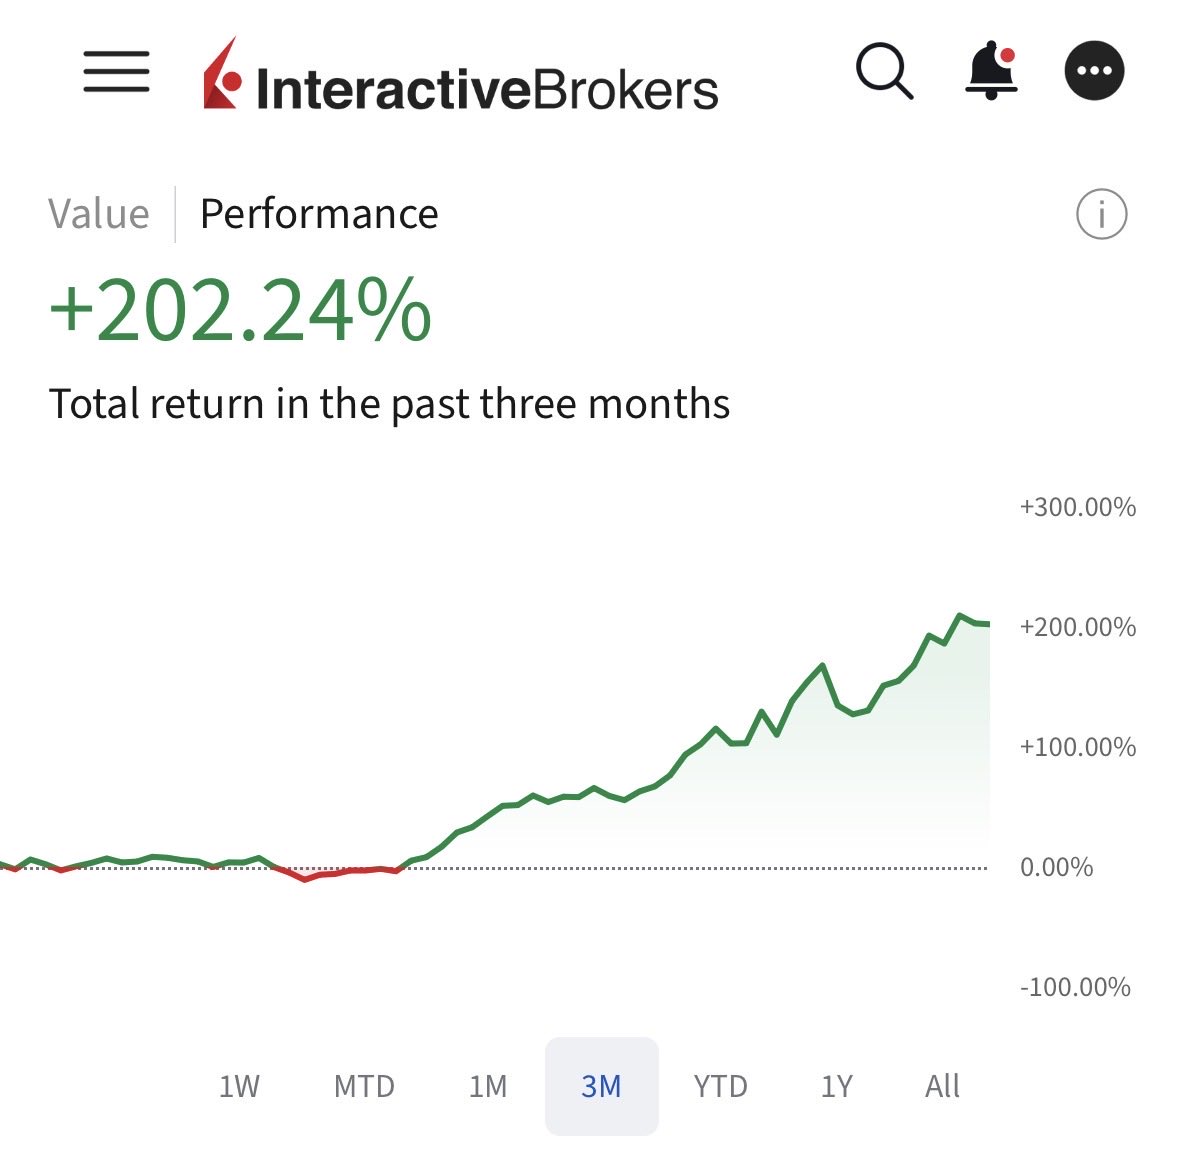
The past 3 months have been an incredible run for my portfolio, through names like $BRUN, $SIVE, $DGXX and many more.
Many of you might not know this but I have actually been following @dannycheng2022 for more than a year now. Our styles are slightly different, I aim for small cap companies while he prefers to compound gains in larger cap stocks.
Although the difference in style, his Patreon provides so much macro guidance and it keeps me invested in the markets despite all the FUD (e.g. A.I is a bubble, we’re bound for a huge correction). I have also learnt the importance of position sizing from him (and that’s why I went balls deep on $BRUN). Pairing the insights from his Patreon along with my investing framework has enabled me to reap such gains for the past 3 months.
If you haven’t already, please check Danny’s Patreon out, his system is tried and tested, proven to provide value and alpha to many, trader or investor!
(I sincerely hope this screenshot doesn’t mark the top)
- Leki, the investing monkey 🙊
> markets went from doubting $SIVE customers ($150m MC)
Turns out it’s likely companies eg. $JBL, Ayar, $AAPL, Defense Primes, $MRVL celestial.
> to doubting their execution ($600m mc)
Turns out you skip the capex if you go with Win Semi
> to doubting what share they get vs competitors like $LITE ($1.2B mc)
Turns out it’s likely sole source for companies like $JBL and primary suppliers for Ayar.
> to doubting their revenue opportunities ($2B MC)
Turns out they got 77% pipeline growth in just a few months
> to doubting their partners like Win Semi’s ability to scale (we are here)
Anyone who thinks Win Semi… one of the worlds most important foundries for $AVGO, $LITE, SpaceX supply chains…
can’t scale capability by 2028 is a stupid bear.
We’re at the point where US retail investors acquired the float off Swedish investors.
But I’m expecting US institutions to find a way to shake out US retail like they did with $NBIS or $RKLB before the next supercycle.