ANT dropped the bomb. By my count, ARR is $69 billion in September and the pace of adds slowed to just ~$2bn/mth. We are going to need hell lot of acceleration to hit $110 billion.
https://t.co/Fgj8EiuSfI
Abit of chartcrime here, but seems like we have maybe... another 10%+ drawdown for soxx before we bottom? Take out the dotcom and GFC, most of the time we do fine after this next leg of drawdown.
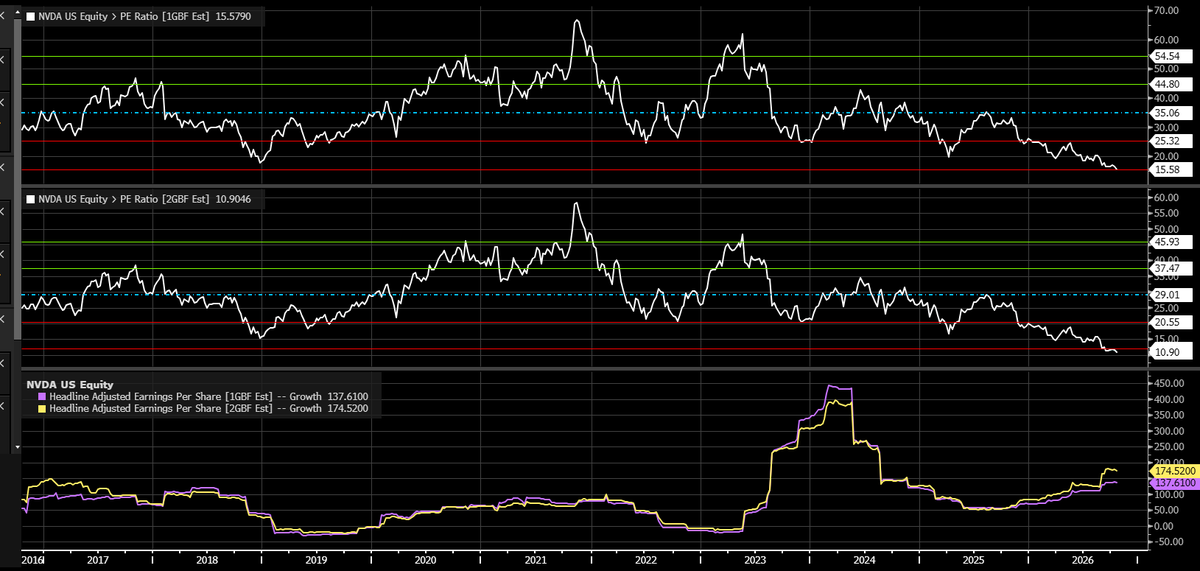
I want semi numbers cut, but this seems like a interesting long at 15x? (maybe low-teens buyside). If @JensenHuang is right that $NVDA has no LPS problem, then it should see deliveries and earnings rip. All the other semis die. Is it time we long $NVDA and short the othe semis?
@Ross__Hendricks The fact that you are saying $GEV get smoked because of AI shows how, lack of a better word, stupid? This take it. Yuo can argue about lack of LPS which pushes out DC builds and hit semi numbers, but $GEV? This guy sells turbines to utilities man. Are you using candles at home?
TLDR; we will probably never get another ARR number from Anthropic, which is healthy. Should force the market to move away from extreme focus on Anthropic/OpenAI ARR numbers to hyperscale growth rates, which are a much better metric for AI at this point given they capture Muse, Grok, Gemini and Open-Source.
Anthropic FCF positive in Q3 and reaccelerating in October on Opus 5.5 per third party data. Roadshow in several weeks will happen after this has been widely confirmed. Unit economics much better than expected given positive FCF with 75% of their compute going to training. All per public reporting.
OpenAI continuing to grow at the same pace per Sarah Friar interview after they took share vs. Anthropic in Q3. Means the sum of Anthropic/OpenAI growth is accelerating from the Q3 pace. OpenAI probably hits FCF positive in the next few months.
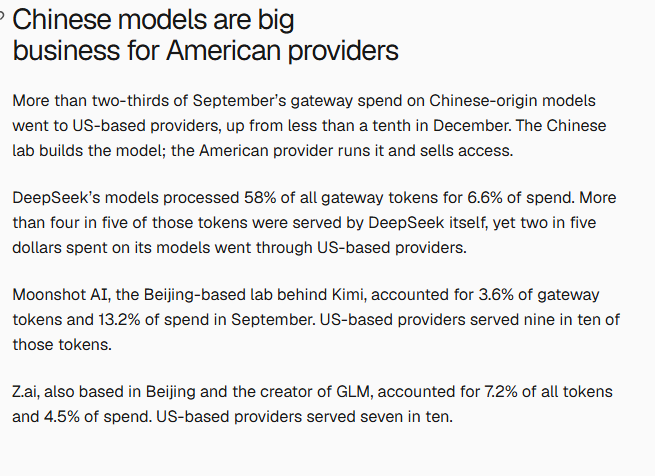
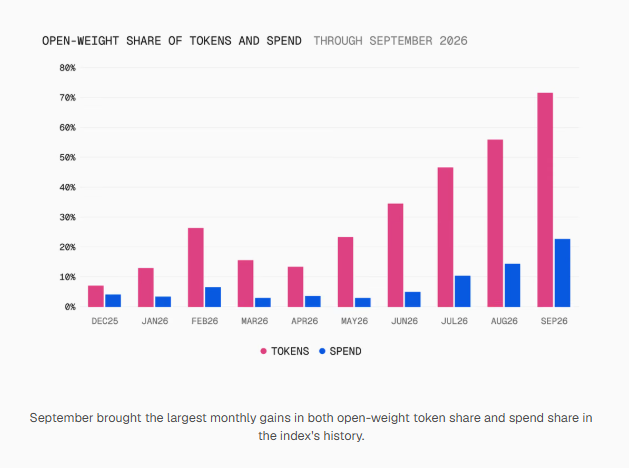
Open-source growing much faster than either Anthropic or OpenAI. Modal tripled since May and is 15x YoY per yesterday’s announcement. Open-source tokens generate more revenue and profit for the hyperscalers/neoclouds than frontier tokens. *Every* open source inference cloud I am aware of is growing faster both sequentially and YoY than either Anthropic or OpenAI. And their combined compute spend is becoming material.
Third party data pointing to hyperscalers continuing to accelerate in Q3. All report in the next two weeks. Acceleration should continue in Q4 and Q1 as installed base of compute slowly reprices higher closer to spot and new capacity comes online at higher prices. Continued acceleration in hyperscalers should help address external funding concerns.
10 year yield down in a straight line over the last 24 hours.
Some risk of escalation in Iran next few days, but earnings and mid-terms probably outweigh taking an ultra long-term view and looking out 30 days.
Biggest risk imo remains cyber and OpenAI/Anthropic dominating the model layer. Fragmentation, competition and lower margins at the model layer are good for everyone else in the ecosystem and for America.
Slower for longer is much better than an overbuild and an actual bubble.
Alright. So where is the floor here. Semi numbers need to come down? In order to match the lack of LPS dynamic. Maybe the final boss is hypers cut capex?