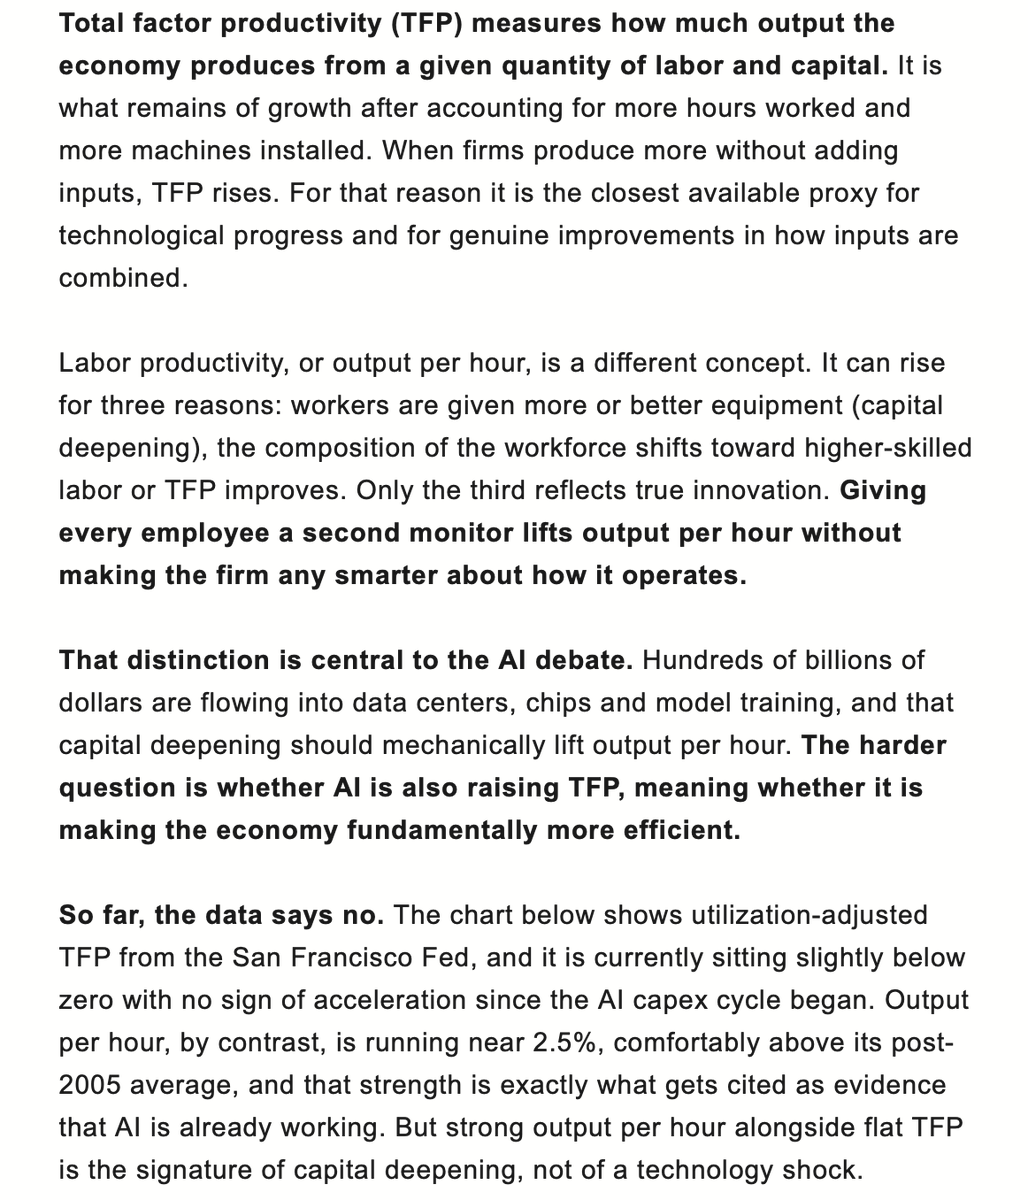
Torsten Slok had a good post this morning on why labor productivity is an incomplete picture.
We can get more work done if we're given AI tools, but how much capital was invested into the tool?
If 100 workers produce 10,000 widgets and they receive a machine that allows them to produce 15,000 widgets, labor productivity rose 50%.
The question is what does the machine cost?
@compound248 Anything quality housing tricky. A lot of businesses benefitted from 60 year bull market in rates. Think a lot of mults bleed lower as that reverses for next 30 years.
Feels like a lot of crude levered equities ($XLE, $XLB) underestimating the convexity in commodity prices here. People afraid to step in front of a Trump tweet but every day this drags on probably 2-3x multiplier on time to return to a "balanced" market.
@breadcrumbsre Depends on business cyclicality but in commodities the correct answer is hoard cash to buy capacity in the next down cycle from companies that overextend themselves.
Time to fade the LTLs again. Market back to pricing in a COVID stimulus + yellow bk up cycle, for what feels like the tenth time in the last 4 years.
$ODFL, $XPO, $SAIA
Crazy move in transports. $ODFL, $SAIA both need to double EPS in the next 3 years to justify the re-rating over the past month. Only two periods in the last 20 years where rev growth and margin improvement were that material over a 3 year period: post '08 crisis and post COVID stimulus. Good luck.
Once upon a time, IPP terminal value was 0 bc of renewables/ESS, now they are secular growth stories bc of the insatiable power demand for AI. Wild how far the pendulum has swung. Going to be epic shorts when generalists realize that nat gas drives power prices. $NRG, $VST, $CEG
Also pretty high cognitive dissonance here imo. Power demand hasn’t grown in 20 years. But demand for this powerful productivity technology is going to change that. But don’t worry, it won’t lower costs / create efficiency in the power markets. Just everywhere else.