Really fun to interview my old friend Bret Johnsen in Mission Control.
Three parts of the @SpaceX story that I wish were more widely discussed:
SpaceX has created thousands of good blue-collar jobs: welders, machinists, electricians. Everyone talks about the need to bring high-paying, blue-collar jobs back to America. SpaceX and Tesla are making that happen. To the best of my knowledge, they have created more manufacturing jobs in the US than just about any other American company over the last ten years. It’s hard to imagine our nascent industrial renaissance succeeding without these companies.
SpaceX was started with the goal of putting humans on Mars. And along the way, they have massively improved life for many humans on Earth. Mars may be a starter planet, but Earth is our planet, and the technologies developed at SpaceX are already in use today connecting and safeguarding the people of Earth. Starlink is a really efficient way to bring internet to low-income countries. In Kenya’s remote Murang’a County, Starlink has made it possible for patients in rural villages to consult with medical specialists via telemedicine. In the rainforests of Brazil, Starlink has connected schools to reliable high-speed internet that will provide more educational opportunities to students. Here in America, Starlink has proven vital to emergency teams responding to natural disasters. During Hurricane Helene, the Starlink hubs dropped into North Carolina and East Tennessee were often the only contact point between cut-off towns and the outside world. Literally life-saving.
This IPO will be a big milestone for the company. It’s important to celebrate this, while also remembering that making humanity multi-planetary is the ultimate goal. Going to Mars is really hard. There have been many setbacks thus far, ranging from fiery explosions to failed landings. There will be many more. Ad Astra Per Aspera. But SpaceX is at its best *after* a setback imo. Their first 3 launches were “failures”. Had the 4th not succeeded, there might not be a SpaceX today. The company’s success in the face of such daunting odds is a testament to the resilience of the culture and absolute commitment to the mission shared by every employee I’ve ever spoken with. Some of the world’s most talented engineers have chosen to live in Airstreams at Starbase away from their families for weeks on end in service of this goal. I will never forget the welders who told me they signed every weld because they wanted to be accountable if they were responsible for a failure. True missionaries, all of them.
I am grateful to every single person at SpaceX for helping to make the future as inspirational as possible. And I will be even more grateful if I get to see a blue sunset on Mars!
More info on https://t.co/dLOPlKr0Un
@AdtechGod@trishlaostwal@MarkStenberg3@TheTradeDesk@OpenAI Recent high-profile departures from TTD include CMO Ian Colley, communications VP Melinda Zurich, and SVP Matthew Henick in April 2026, plus a CFO who lasted only six months and several board resignations...
My guest today is Paul Tudor Jones (@ptj_official), one of the greatest macro traders of all time.
He correctly predicted the 1987 stock market crash and shorted the Japanese bubble in 1990. For over 40 years, his flagship fund has had a negative correlation to the S&P 500. 100% of his returns are alpha.
He says today's market has so many similarities to 2000, "the easiest bear market I've ever seen in my whole life."
He makes the case for going long dollar-yen, why Bitcoin beats gold as an inflation hedge, and why he was wrong about Warren Buffett.
But what I'll remember most from this conversation is Paul's zest for life. He's 71 and still wakes at 2:30 every morning to trade the London open. He works out for two hours a day. He walks with his wife every evening. He travels the country chasing peak spring and peak fall. He's so excited about the songs picked for his funeral that he wishes he could be there to hear them.
Paul has lived five lifetimes in one. He's one of the most entertaining and interesting people I've met, and the conversation will leave you searching to be as passionate about what you do as he is about what he does.
Enjoy!
Timestamps:
0:00 Intro
1:00 The Kindest Thing
13:19 Trading vs. Investing
17:33 Lessons from Warren Buffet
22:24 The Existential Risks of AI
29:54 The Nature of Trading
31:46 Bitcoin
35:55 Bubbles
42:08 A Day in the Life of PTJ
46:00 Information Overload
47:07 Passion for Markets
50:49 The Robin Hood Foundation
54:18 The Workless World
56:03 Journalism
1:00:00 Principal Components of a Great Life
1:05:06 Kill Them With Kindness
Google $GOOGL loses the anti-trust case and the earnings multiple continues to drop. It's currently sitting at 17x while growing earnings in the mid-low teens.
This stock just keeps getting beat up. At 17x earnings and Google returning capital to shareholders now via buybacks & dividends how is this a bad investment here??
A few words of advice to $TSLA fans: Don't compare $TSLA to $AAPL
1) $AAPL had 3-4 major rivals at iPhone launch
2) $TSLA has 100 alone in China
3) That's why $TSLA *has to* spend 10% capex/sales
4) $AAPL capex/sales = 4%
5) $TSLA 5yr R&D/sales = 5.3%; $AAPL = 6.7%
Game Over
THE PRIMACY OF REVENUE GROWTH
Having grown up as a Tiger-style investor, one of the lessons that sticks with me the most is the value of revenue growth. As an impressionable 24 year old analyst, I will never forget Steve Mandel from Lone Pine telling our analyst group a simple but powerful truth - sustained structural growth is (almost always) chronically underpriced in the market, and sustained secular decline is (almost always) chronically overpriced in the market. In a market ecosystem keyed on P/E ratios, investors will get the proper P/E range directionally correct but will miss on magnitude.
Don't take my word for it. A simple 30-year DCF architecture structured to sensitize revenue growth will display this truth. To simplify a complex reality, here I take revenue of $1m at T0 and hold 10% operating margins, 6.5% FCF margins, 35% debt/EV (5.5% interest rate), 10x terminal multiple at year 30, and an 8% WACC in all cases (which is generous to the decliners as usually revenue has beta to margins both ways).
What stands out to me on this chart is how much more a 10% grower is worth than a 5% grower - roughly double in P/E ratio terms. This math shows that companies that can grow 10%+ on a sustained basis *should* have a floor P/E of roughly 30x, and companies that cannot growth revenue should trade with a 10x P/E ceiling.
In my observation, this simple math explains one of the biggest philosophical differences between the Tiger-style long books and classical value investors where the value trigger tends to be low multiples on current year earnings.
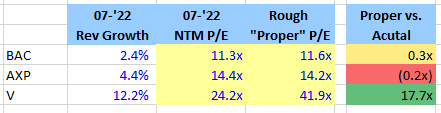
Let's pick on Buffett for a minute. Two of his largest holdings have been BAC and AXP. These stocks have been "cheaper" than the market historically trading ~11x and ~14x, respectively. V, in comparison, has seemed "more expensive". However, with perfect foresight, we can see that V's meaningfully superior revenue growth rate is "worth" a P/E over 40x. Price is what you pay, value is what you get. V has been demonstrably the cheaper stock over the last 15 years (and as such, a vast outperformer vs. BAC & AXP), despite never looking optically cheap on a near term P/E basis.
Certainly the pushback to this mindset is "well, hindsight is 20/20". In aggregate and over long periods of time, it pays to bet against the durability of double digit revenue growth. Almost always, the "next AMZN" is not the next AMZN, and investors can fall into survivorship bias here. As the base grows, sustaining 10%+ gets mathematically more difficult. And the market tends to extrapolate these levels of growth, such that top line decelerations are usually painful events with a twin smackdown of revenue misses and de-rating lower (this is a key short alpha hunting ground). I don't dispute that.
What I would suggest is that one of the most powerful insights that a fundamental investor can reach is conviction in the next durable growth story. Applying your idea generation & due diligence process to uncovering the next business that can sustain 8-12% revenue growth for 10+ years is, in my opinion, one of the more broadly fruitful approaches and an enduring lesson that the Tiger investment community has taught us. And even in a hyper competitive institutionally driven market of quants & pods, my observation is that the market still hasn't gotten this message on its chronic mispricing error.
Hope that is helpful!
Brett
MY DAILY SCHEDULE AS A PORTFOLIO MANAGER
Last week in class at ASU I had a PM at a NYC hedge fund come in as a guest speaker.
A student asked him the typical "day in the life" question and we got a good laugh thinking about a "Hedge Fund Morning Routine" post...his first step was "wake up in a panic" and oh man it brought me back...
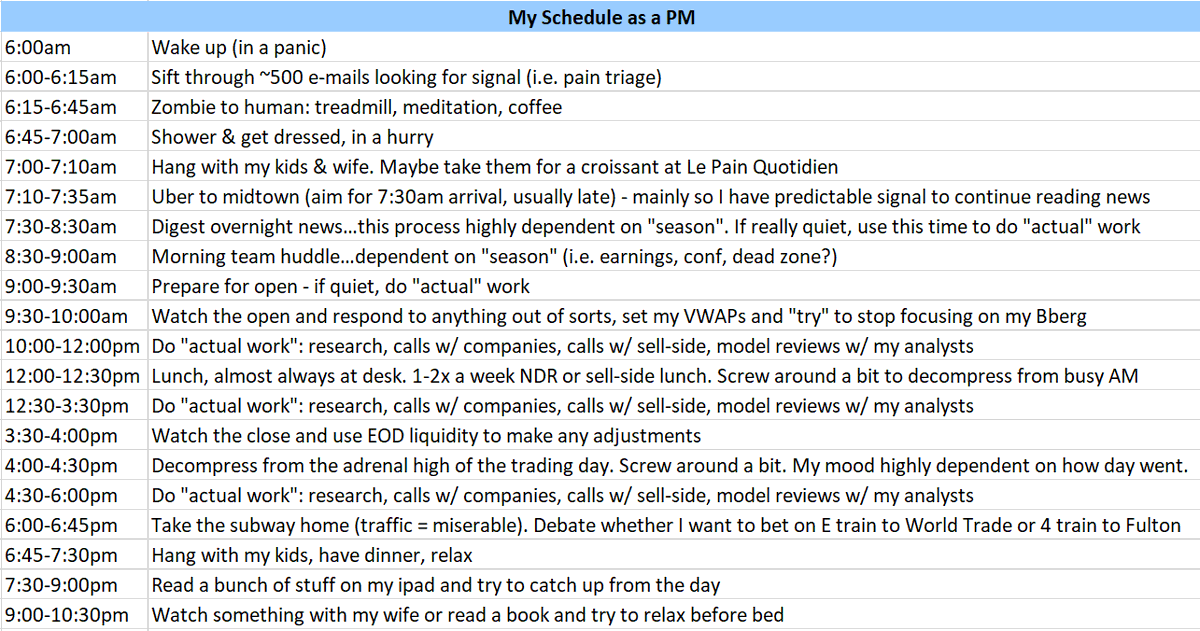
Rather than attempt to be purely comedic, I thought it might actually be helpful to some analysts to see the day from the PM perspective and a few takeaways from my ~5 years of the daily balancing act of being a PM. The reality is that the PM seat (this is from my pod era) is an incredibly demanding life, which I'll discuss a bit here.
I do occasionally hear the perspective from analysts of "what does my PM do all day" - it may feel to the analyst like YOU are doing all the work - building the models, generating the thesis, etc., and that the PM is just overseeing that process. I would push-back on that view, in most cases, and hope to give you a perspective from the other side of the table.
BREAKING DOWN THE DAY
First, a caveat: I can give you a much more accurate "quarter in the life" than a "day in the life". The quarters are predictable...earnings, conferences, dead zone, repeat. The below script makes the day look much more predictable than it really is. Is it earnings season? Am I at a conference? Did my biggest long blow up and I'm in all-hands-on-deck triage mode?
With that caveat, my *general* day was a 16.5 hour day with 7.5 hours of sleep (I did and still need my sleep). About an hour of time for personal needs, 1 hour with my kids (part of the reason I retired...I wanted more), 1-2 hours with my wife, and 1 hour commuting.
That left roughly 12 hours for work focus. That seems like a lot, right? It gets chopped up quicker than you think.
In this scenario, I'm spending 2-3 hours on my phone / iPad reading news, sell-side research, spec sales notes simply digesting the news flow of the day. Some of this while I'm on the treadmill in the morning, in an Uber, the rest at home in the evening. With a portfolio of 60-80 stocks and a broad coverage of 250 stocks there is a LOT going on each day.
In this scenario, I'm spending 1-2 hours on the tactical considerations of the day. The morning huddle, speaking to my trader, making nips & tucks on positioning, watching the open, watching the close. This part has a gravitational pull as the blinking lights on Bloomberg can really pull me down a rabbit hole...
This leaves 5-6 hours for actual research work. The outbound, intentional, rigorous work that is required to generate differentiated investible insights needed to generate consistent alpha. Speaking with companies. Calls w/ sell-side & other investors. Reading source documents. Joining expert calls w/ my analyst. Evaluating data sources w/ data science team & analysts. Doing analyst model reviews. This is on an ideal day, which happens about as often as an ideal NYC weather day (i.e. 20 times a year). More often, this gets compressed to 2-3 hours per day as my calendar gets filled with compliance training, internal interviews, broad sector meetings, etc. Doesn't seem like enough? Doesn't seem like enough to me, either. This was a genuine struggle I had. How do I carve out enough time to generate alpha insights when my day is crowded by these other considerations? My only real answer was to lean on my team, build the trust in other team members to do good research. But that can be a chicken & egg problem...if I don't have enough time to train my juniors & engage with them deeply on a due diligence process and lead by example, how will they ever learn?
Thinking through this reality, as an analyst, and this is mostly pod-specific but has applicability to other firms as well, there are four things I would propose at takeaways from the typical PM schedule.
1) A 24-HOUR PARANOIA ON NEWSFLOW. Even if your PM "seems" like he or she is not working 14 hour days, your PM is almost certainly tied to e-mail / Bloomberg / Street Accounts / company IR alerts with an intense paranoia about news. Steve Schwarzman said there are no old brave people in finance. Senior PMs live with an intense paranoia around news, pretty much around the clock. This doesn't make for a peaceful life, but you as an analyst should align with that...i.e. wake up early and distill news for your PM, constantly monitor news around the clock and contextualize key news / sell-side actions with your specific expertise. If your company blows up on news at 7am, you should be digesting that immediately and responding to your PM as close to real-time as you can. These are the moments when your expertise of being closer to the situation matter.
2) VERY LITTLE ACTUAL RESEARCH CAPACITY. BY FAR the hardest transition for me from Tiger style analyst to pod PM and from single man to married man with 3 kids was the compression of my research capacity. As a 25 year old Tiger-style analyst so many days I could work 7:30am-10:30pm and get 12 hours of true research done in a day. I was a psycho and intentionally lived at 56th & Lexington by the Harley Davidson store so I had a 5 minute walking commute. I was all in. Per the schedule below, as a 32 year old father of 3 living in Battery Park City that was no longer possible. On a BEST case day I had 6 hours to lock in and dig through companies. On a more typical day, that is 1-3 hours. How can I hope to do differentiated stock research in that situation? I can't, unless I have good team members around me. It's also the reason after I left Citadel that I considered a concentrated boutique small cap long only strategy where I could go back to 8-10 hours of true research in a day, but that's a story for another day. Know that in this context as an analyst, your job is the be the lead on the due diligence process.
3) ANALYST TRAINING. INTENTIONS VS. REALITY. I've beat this dead horse a million times here. But my opinion is a junior analyst needs 100-150 hours of training & mentoring to get up to speed in the first 6 months on the buyside. Our Academy is 60 hours over 6 weeks. With this schedule I led a team of 9. 100 hours of training for 4-5 junior analysts was just not time in my schedule that I could spare, despite my good intentions. If your PM is neglecting you as a mentor, my hunch is that it's the same story. It's (likely) not personal, it's just the simple reality of the crushing responsibility of the PM seat. This creates an environment where being a self-starter and a self-learner differentiate success vs. failure (insert obligatory plug for the Fundamental Edge Analyst Academy...)
4) A GENUINE STRUGGLE WITH BALANCE. The sad part about revisiting this schedule is the minimal time I had to spend with my kids. Many days it was only 10 minutes in the morning, 10 minutes in the evening. I get a pit in my stomach thinking about it now. This job can absolutely dominate your consciousness and I have insane respect for the PMs who can balance everything. I still mark my second son's birth to the day Valeant blew up and my third son's birth to the day our biggest short MRK missed and cracked. It's sad to me that my focus on my portfolio crowded into those special moments in my life. Not to mention, on this schedule below I didn't have much time to be helpful around the house / a super participatory parent outside of the weekends.
There are numerous reasons that my PM career was relatively short (4-5 years), not least of which is that I was not a top 5-10% ace, but ultimately the biggest reason was the nearly unending and crushing responsibility that comes with being a fiduciary of capital and being in a seat where the difference between down 3% and up 3% is the difference between being fired & ostracized and being paid 7-8 figures...the intensity of the incentive can create a real addiction. For me, it was a simple story of burn-out and shifting desires in life. If you are in that situation...I've been there, and unfortunately I never found the perfect answer to manage it.
Well per usual I intended to write a short tweet and I wrote a long one. I must get back to work!!
Does your business have a Financial Policy?
If not, you need one.
The Financial Policy is the rulebook that governs how you fund your business. And treat your shareholders.
It’s especially valuable in businesses where there are multiple complex stakeholders.
It provides the framework for making capital structure and balance sheet decisions. Ensuring everyone is working to the same plan.
If you are a Board, you need to have one.
If you are a Shareholder you should demand your Company has one.
If you are a CFO or CEO having one will make your job easier.
By setting clear guardrails you can take the emotion out of corporate finance decision making.
A Financial Policy has 5 Sections:
1. Overall Objective
2. Debt
3. Liquidity
4. Distributions
5. Capital Allocation
1. Overall Objective
Start with what the overall financial objective for the business is.
This will depend on the stage of business, and should speak to the financial risk and return appetite of the business.
Some examples for (illustrative purposes only):
- Dividend Stock: Deliver total shareholder return of at least a 6% premium to the base rate, with a minimum of 50% of after tax profits distributed to shareholders.
- Turnaround: Reduce debt levels to below $700m and Net Debt Leverage to below 3x EBITDA. Then recommence dividends.
- Startup: Maintain a minimum 12 months runway, and grow valuation by 2x each funding round
- PE Backed: Minimum Net Debt: EBITDA of 4x upon entry, maximizing equity value accretion over 5 years
- Prudent Balance Sheet: We never have more than 1.5x EBITDA of debt, and ensure we always have $100m of cash on balance sheet as a minimum.
2. Debt
This should set the rules around how and when you use debt, and sets some limits on how much.
Example Policies:
- Long Term Leverage Target is 3x. <aximum leverage tolerance in the short term is 5x reducing to 4x by 2025.
- Refinance debt a minimum of 18 months before its maturity.
- Prefer fixed rate debt but use interest rate swaps to manage rate risk on floating rate debt where there is arbitrage.
- For internal metric purposes treat all off balance sheet debt as debt.
Metrics that you could include:
- Net Debt : EBITDA Leverage (Target, and Limit)
- Total Balance Sheet Debt $ Limit
- Total Debt (Off & On Balance Sheet)
- % of Floating vs Fixed Rate Debt
- Average Duration of Debt
- Shortest Duration of Debt
3. Liquidity
The rules you set to make sure you don’t run out of money
Example Policies:
- Never hold less than $100m of cash on balance sheet
- Set internal liquidity headroom limit at $200m, with a warning level set at $250m.
- If a 12 month look forward suggests a breach, raise new liquidity from the following sources, in this order: additional working capital facilities, equity, term debt.
Metrics:
- Cash on Balance Sheet
- Total Liquidity Headroom (Cash + Committed Undrawn Facilities)
- Forecast Minimum Headroom (12 Months Rolling)
- Runway (for Cash Burning Businesses)
- Armageddon Survival Buffer: Liquidity Headroom / Avg Daily Sales
4. Distributions
How and when do you return money to shareholders?
Some examples:
- Distribute a minimum of 50% of after tax profits
- Buyback shares before dividends if the P/E ratio is below X
Metrics:
- Dividend % of Earnings
- Dividend % of Free Cash Flow
- Buyback:Dividend Ratio
5. Capital Allocation
How do you make decisions about where and how to allocate surplus capital? How do you prioritize?
Some examples:
- Prioritize capital allocation based on NPV Per $ Capital At Risk ranking by project / options
- First exhaust surplus capital on all growth projects with an IRR of greater than X%
- Appetite for M&A?
- Allocate capital to debt repurchase until Net Debt is below X.
Metrics to use:
- IRR %
- NPV Per $ Capital At Risk
- Payback Period
- WACC
At its simplest a financial policy could be just one sentence.
For example, an SMB owner operator might decide they will distribute 100% of after tax profits as dividends, and never buy any business, and never take any debt. That's enough.
At its most complex (an F500) it could run to several pages or chapters.
The more diverse the stakeholders, the more complex the Financial Policy will be.
The important thing is being deliberate about balance sheet management. Agreeing a framework bespoke to your business with all stakeholders.
Then documenting it.
And then living it.
The IPO process takes more time and is more intensive than any management team ever thinks.
For many Australian technology founders with a potential IPO on the horizon, listing on @Nasdaq and @NYSE has become an increasingly viable option, given Atlassian's success in doing so.
The IPO location conversation is one we’re very familiar with. As board members and investor partners, it’s our job to arm our portfolio companies with the facts and figures to understand the trade-offs between listing in the US and listing in Australia on @asx.
This post reviews a few of the key discussion points sitting in most executive teams' blind spots.
Capital Market Differences – USA vs Australia
The US capital markets are the deepest in the world, and with that comes more analyst coverage – however, given this, it can mean it’s harder to garner attention for smaller growth businesses in the US.
· There are 15x more listed software companies of scale (>$200 million in revenue) in the US than in Australia
· The median market cap of software businesses on the S&P500 is 9x higher than the ASX200. However;
· There is a higher concentration of analysts in Australia for businesses with an EV sub $3 billion.
A common misconception is that US-listed technology businesses receive higher valuations. Generally, we see zero impact between the two locations on valuation multiples. Both markets are highly correlated for valuation in terms of both absolute growth and efficiency. If there is any valuation premium, we actually see top-quality ASX tech businesses attract a valuation premium given there are fewer of them (see image 1 & 2).
Free float of US companies turns over about 3x faster than ASX-listed companies. A more stable register of longer-term investors gives businesses greater ability to execute longer-term strategic initiatives. Australia has the 5th largest pool of pension assets & global investors make up a significant portion of ASX-listed companies’ share registers.
It is far easier for smaller businesses to qualify for major indices in Australia. Inclusion in the indices can create meaningful demand. For example, the market cap threshold of an ASX200 is ~$510 million vs S&P500 ~$7.6 billion.
Operational Preparation and Governance Differences
The two markets have vastly different operational and governance requirements. Here are some we find most commonly discussed:
1/ Cost to list:
Listing in the US costs more upfront and ongoing. On average is it 2x more costly to list in the US – a difference of $10 million. The biggest variance in quantum is in underwriting fees – while the legal fees are almost 5x more expensive to list in the US, Directors and Officers insurance can be up to 10x more expensive in the US (see image 3).
2/ Timelines:
Pre-prospectus lodging: US 18-24 months, AUS 9-12 months.
The work streams are wide and varied, but most of these fall upon the finance function. Of course, there are other work streams relating to corporate and capital structure, compensation and post-IPO stock-based incentive programs, governance and board composition and committees.
Official IPO timeline: US 4-7 months, AUS 3-4 months.
Notably, the SEC review process in the US can take up to 16 weeks vs the typical ASIC review of one week (see image 4 for complete timeline).
3/ Secondary transactions (pre- and post-listing):
In Australia, it is easier to sell shares at IPO and raise money in follow-up offerings. The US, however, is better structured to facilitate founder and management selling post-IPO via 10b5-1 plans.
4/ Ongoing obligations:
The most obvious variation is that the US requires financial reporting quarterly vs Australia’s requirement for semi-annual. Beyond this, it is generally far more onerous to be a listed business in the US – audit and internal control requirements are cases in point.
5/ Directors and Board Governance:
There is a wide variety of nuances to consider in the two markets that you need to be aware of. By way of example, in Australia, all Directors are (re) elected at each AGM, while in the US Directors have set terms. Remuneration norms are also very different – for instance in the US often board members are issued RSUs, while in Australia there is no allowance for performance-based equity programs for directors.
6/ Foreign Issuer and Emerging Growth Company (EGC) concessions:
There are a variety of benefits of being both an EGC in the US – defined as being <$1.235 billion in gross revenue – during the IPO process as well as ongoing. For instance, only two years of audited financial statements are required vs three for non-EGCs and there is a more streamlined executive compensation disclosure on an ongoing basis.
As a foreign private issuer (FPI) there are reduced disclosure requirements but of course, this comes with the risk of reduced investor appetite and associated trading discount. Attached Example 3 is a more complete list of FPI Benefits.
TDM Additional Views
We have long preached the importance of acting and behaving like a public company well in advance of even contemplating listing.
Aside from the scaling of systems and processes, ensuring a high-impact board and having key executives in place and highly incentivised for the next 4-5 years more broadly, we encourage;
· Establishing and practising your financial reporting framework. Management must develop and foster the skill of providing formal investor presentations and financial forecasts on a semi-annual basis.
· Practising the rhythm of not only preparing regular forecasts but also making a good habit of meeting or exceeding them.
· Establishing investor relations and education. It is important to start now to raise awareness and understanding of your business among public market investors, using these opportunities to learn how to deal with a public market investor ‘Q and A’.
This post is a combination of public data and our views from regularly working through this process with our portfolio companies.
If you would like more IPO preparation resources, our quarterly newsletter will be including more detailed slides on this analysis and other IPO-related content : https://t.co/pYskOioEkz
If you want more IPO content now, linked is a chapter we wrote in the @ASX Entrepreneur’s Guide on IPO Readiness : https://t.co/g024mBUe8u