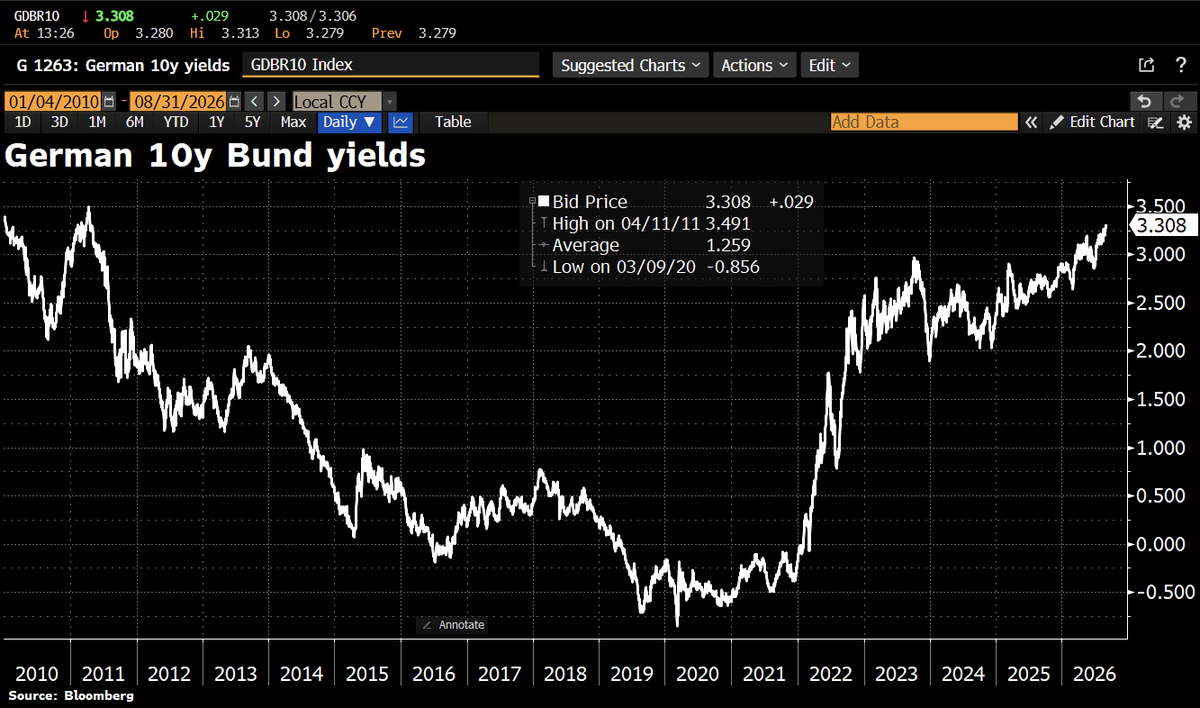
Good Morning from Germany, where borrowing costs keep climbing. The 10y Bund yield has risen to 3.31%, its highest level since 2011, as bond markets brace for the latest inflation data. Germany’s benchmark yield is now just ~18bps below its 2011 peak of 3.49%. The era of cheap money feels increasingly distant.
Yes, August and September are 'supposed' to be bad, but this year hasn't been like other midterm years.
Remember, Q2 in a midterm year was also supposed to be bad (it is the worst quarter out of 4-yr prez cycle), but instead we had the greatest Q2 midterm year return ever. Will Aug/Sept continue this trend? I think so.
Breaking!
The Japanese yen has weakened past 160 per dollar again, despite ‘the intervention.’
That intervention cost nearly $100 billion last month.
So, Mr. Bessent, how is that ‘smart intervention’ aimed at preventing Japan from outright selling U.S. Treasuries working out for you?
And have you called the Chairman of your ‘independent’ central bank yet to discuss where you want things to go?
The minute global bond or currency markets start to wobble as investors add up all the ‘inventive’ measures taken to prevent Treasury selling and yields from rising, the love affair between the Treasury and the Fed will be put to the test.
Because eventually, one side will have to give.
Got gold?
Good Morning from Germany, where the great inheritance wave is turning into a tax bonanza: inheritance & gift tax assessments surged 61% to a record €21.4bn in 2025. The main driver: tax on wealth transfers above €20mln jumped 147%. And the inheritance divide remains huge: just 2% of inheritance-tax revenue is generated in eastern Germany.
Global copper supply remains under pressure as all top 6 producers reported YoY volume drops in Q2 2026, led by sharp contractions at Freeport (-18.4%) and Codelco (-13.5%).
Even as select miners delivered quarterly gains, widespread annual output dips highlight the mounting operational and environmental headwinds facing global production.
8-28-26 The Bond Market Is Setting Up For A Massive Short Squeeze
$TLT $BND
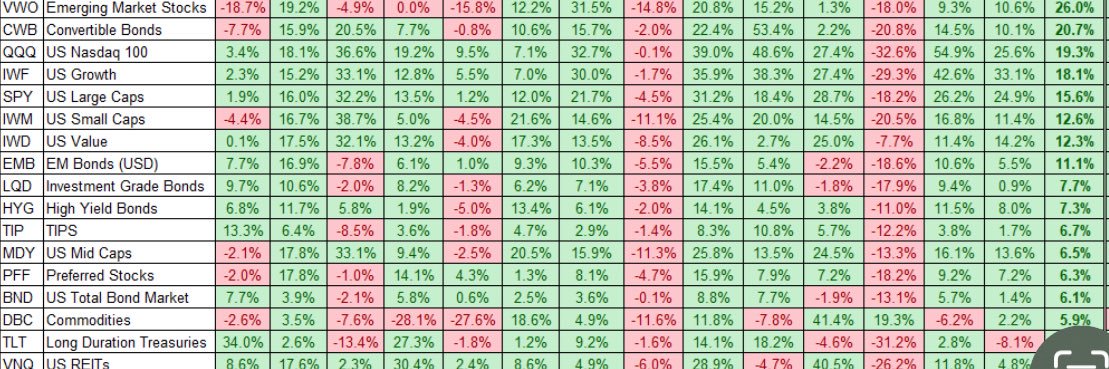
The bond market may be building one of its most interesting contrarian setups — not simply because inflation and wage growth are declining, but because positioning has become extremely stretched.
There is currently a massive short position against Treasury bonds, much of it tied to leveraged hedge funds running the basis trade. These funds attempt to capture small pricing differences between Treasury securities and futures, often using significant leverage and short Treasury futures as a hedge.
That creates the potential for a powerful unwind.
If an event causes Treasury yields to drop sharply, those leveraged short positions could come under pressure. Hedge funds would then be forced to cover their shorts, which means buying bonds.
That could create a self-reinforcing cycle: yields fall sharply → bond prices rise → Treasury shorts come under pressure → hedge funds cover → bond prices rise further → yields fall even more → additional shorts are forced to cover.
Goldman Sachs has highlighted similar dynamics in its conditional projections for the 10-year and 30-year Treasury markets.
This is why the bond opportunity right now isn't necessarily about making a long-term call that yields have peaked forever. It's about positioning, leverage and the potential mechanics of forced short covering.
Bonds are already extremely stretched to the downside. If the basis trade begins to unwind, there could be substantial upside in Treasuries as shorts rush to cover.
But there is an important catch: this needs a catalyst.
If yields simply drift gradually lower, it may not create enough pressure to force hedge funds out of their positions. The market likely needs an event that causes yields to fall sharply enough to trigger the initial wave of short covering.
Once that happens, leverage could amplify the move dramatically.
So the setup is there, but patience matters. This isn't necessarily a trade that happens tomorrow.
The key is watching for a sharp move lower in yields that begins forcing leveraged Treasury shorts to unwind. If that trigger arrives, what starts as a normal bond rally could quickly turn into a much larger short squeeze.
Please ❤️like, bookmark🔖, and 🔁share with fellow investors
Humanoid robots are not quite ready to take over factories, but they’re getting closer and fast. The potential is huge as analysts estimate the humanoid market could reach $5 trillion by 2050, with more than one billion in use. Adam Patti from VistaShares spoke to Reuters on this
Global oil trade, including oil, condensate and refined products, is expected to rise by nearly 25% by 2050.
Interregional crude and condensate trade stood at around 37.3 mb/d in 2025. By 2030, it is expected to increase to 41.8 mb/d, supported by rising oil demand in major consuming regions. After 2030, the rate of growth slows markedly but volumes still rise to a level of 47.8 mb/d by 2050.
#OPECWOO
API Inventory Moves 5/27
Crude -2.8 million
Gasoline -3.199 million
Distillates waiting for confirmation
Cushing -2.875 million
#oott#crudeoil#api#gasoline
A Technical Meeting to advance and activate the Charter of Cooperation (CoC) Objectives was held today at the OPEC Secretariat, via video conference. In his remarks, HE Haitham Al Ghais, OPEC Secretary General, shared that “almost six years on from its signing, and while we can acknowledge progress made under the CoC process, it is imperative that we take further steps to maximize the Charter’s great potential”. HE Al Ghais also thanked participants from all the countries in the CoC for their valuable contributions to the meeting and said that the CoC, alongside the Declaration of Cooperation, is focused on further evolving a new era of energy cooperation, around the principles of transparency, equity and fairness. He added: “The Charter of Cooperation (CoC), signed in July 2019, is a platform for oil producing countries to advance their interests, amplify their voices in international fora and consolidate advocacy. It also provides important direction and guidance for the OPEC Secretariat, as supporting its activities is a core component of our regular programme of work.”
The ETF market is shifting faster than ever with rapid new launches, accelerating delistings, and increasingly fragmented dividend schedules. @ChristineLShort's latest analysis explores how these structural changes are reshaping the need for precise, forward-looking ETF data. Read more: https://t.co/QrwEG1np4T #ETFs #MarketData #WealthManagement