5s30s has flattened by 33bps in the three weeks since we initiated the trade in our latest macro memo.
Did we write 36 pages of macro reasoning when we could have just said “don’t fight the fed/treasury”, yes…but that’s the beauty of macro research isn’t it?
Whenever Warsh turns to specifics and get precise, it really stands out (because so much of the rest is fillers). Today he introduces another “Warsh” indicator for watching geopolitics.
The three things he has told us he watches:
1) share of the 199 pce components at >3% inflation at 6 and 12 month annualized
2) the second derivative of ai capex
3) and today, on watching the inflation spillovers from geopolitical – the difference between spot prices for corn, soybeans, wheat and so-called crack spreads.
Of those 3, the first likely came down in August, the second probably ex post will have proved to have peaked this year.
I will repeat what I have said many times over the years on FOMC interest rate days:
The interest rate announcement is only as important as what is said 30 minutes later by the Fed Chairman.
I have seen more head fakes on an initial reaction after an interest rate announcement than I can count.
In my opinion, it is not worth making any new trades during the window between the interest rate announcement and the Fed Chair comments.
My take on FOMC tomorrow: there is NOTHING, within the realm of the possible, that Warsh can do to make bond yields go down and STAY down (big difference). Sure, he could hike 200bp+ and throw the economy into recession, that would do it. But is that in the realm of the possible? Hiking 25 and even matching the current market's implied terminal rate will do something, but it's all just a question of speed and YC shape, it won't ultimately reverse the higher yield trend. That needs restrictive rates that moderate the demand for capital and also reverse consumption demand. And that ain't happening.
David Kelly, Chief Global Strategist at $JPM had the most insightful comment on today's macro note /s:
"Treasury market still expects the Fed to, on average, hit its 2.0% PCE target over the next decade"
so everyone cool it.
inflation will be down in no time.
these people
lol
If Warsh hikes and Trump makes good on his promise to cut off trade with nations the US has a trade deficit with, market will throw a fit
If Warsh doesn't hike, policy uncertainty increases and the bond market goes back to tightening for him, market throws a smaller fit
I argued on CNBC this morning that:
1. The data have been consistent with not hiking rates. Core CPI came in at the lowest level since March 2021, and core PCE is about to be revised and brought closer in line with the less error-prone CPI levels. We are getting the evidence we need that the spring was consistent with a one-off energy shock, as core PCE moving averages slope down and come in line with a forecast to be back at target in the period after monetary policy lags, i.e. in about a year. We know from Trichet that hiking into an oil shock doesn't lead to the best outcomes.
2. If you held in June and July and become more hawkish as the inflation data come down, it speaks to an incoherent reaction function. The market needs to believe there is an economic framework underlying monetary policy decisions and they are not being made randomly. Typically, a central bank becomes more dovish as inflation data and forecasts come down, not more hawkish. If the Fed hikes, when the dust settles, I think this will speak to a larger credibility problem as the reaction function will appear closer to randomness than to a mapping from inflation data to policy outcomes. This would entail the need to specify why hiking was consistent with declining inflation data in an economically coherent framework, which to date has not been done.
3. The oft-repeated argument that the Fed needs to hike "to control the long end" is problematic. The premise is invalid: with term premia and inflation expectations well behaved, the move higher in long yields has been a result of improved growth expectations, i.e. a good increase in yields rather than a bad increase in yields, and not one that needs to be fought (other than in the sense of smoothing volatility as Treasury is doing through buyback liquidity). Moreover, even if one views "controlling the long end" as a valid goal for monetary policy, hiking in this environment will be counterproductive as a) an increase in short-term funding costs is only going to be passed through and raise long yields given the shifting buyer base for Treasurys; b) history doesn't really show that long yields come down with Fed hikes; and c) the incoherence of the reaction function will, when the dust settles and after initial reactions, lead to higher and not lower risk premia.
4. What, then, is the argument for hiking? Atmospherics. Market pricing and not wanting to cause additional volatility given market pricing. With well-anchored inflation expectations and the inflation data on the right path, credibility isn't really at risk here.
The argument "inflation has been high for x months" is backward-looking. Given monetary policy lags, policy has to be set for Q4 of 2027 and Q1 of 2028. Setting policy based on what happened in 2023 or 2024 or even 2026 is the type of thing Milton Friedman's "fool in the shower" would do.
Inline with ours on 14A - installed capacity of 6k by 4Q27 with first round of volume input in 1Q28. Current D0 ratio is tracking well.
Reiterate our post yesterday ⬇️
•Foundry yields improving: – 18A (Panther Lake) ~80% in 2Q26 – Larger server CPU (CWF) yields up to ~50% (from ~20% in June)
•Capacity reiterated: 40/60/80 KPM (18A) and 0/6/24 KPM (14A) by end-2026/27/28.
#INTC
So you spent the past year vibe coding various dashboards but you’re not, right now, vibe coding a “good enough” alternative to every app that has elevated margins due to human behavior and habit?
If 🚀 finishes above 15 this week (wont be be easy), I'll write an extended thread on why I'm selling so much RE
Doesn't mean I'll be correct but I think the probabilities suggest it an ideal time
Now up to 320K shares FWIW & not done
Servicing $ provides a floor IMHO
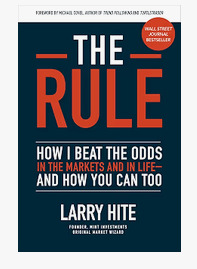
Picked this one up from the library too. Anytime a legendary market wizard writes a book, I tend to read it. Interesting I missed this since published in 2020.
(not a fan of the subtitle... too "self-help" marketing)