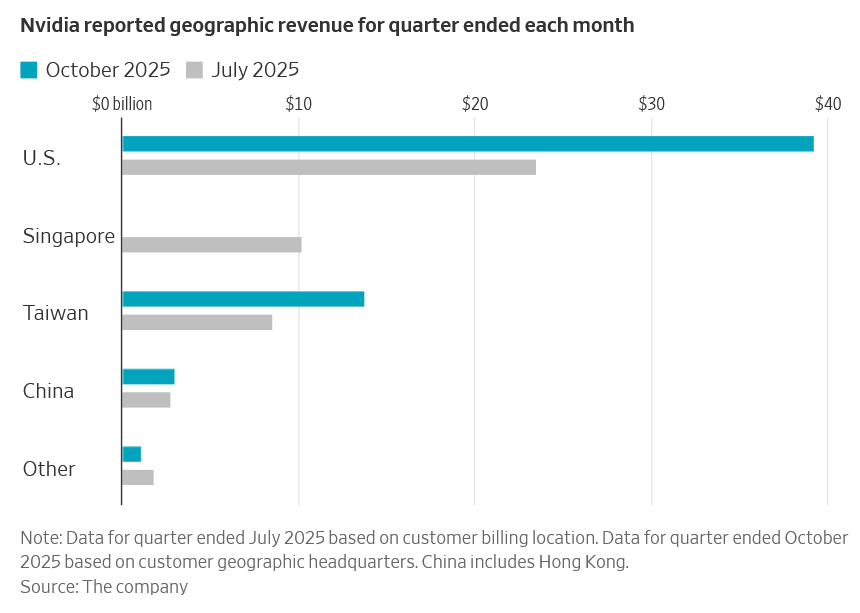Wow.
This Nvidia scandal just keeps getting worse.
Forget the spy scandal and infidelity, new questions are being raised about what Nvidia did with its Singapore revenue.
The country once accounted for 22% of revenue, but seemingly vanished from Nvidia’s geographic breakdown right after the customer behind the scandal was blocked.
Could this have been an intentional ruse?
Investors deserve to know whether that was a reporting change or something worse.
The Dollar just hit its highest in 19 months!
The DXY surged above 103 overnight.
What's driving this?
- CPI came in hotter than expected, with headline CPI rising 0.4%.
- Markets are pricing in another Fed rate hike in Dec, with a larger 50bps move now on the table.
- Wall Street banks are adding further rate hikes to their 2027 forecasts.
- Higher interest rate expectations are strengthening the dollar against major currencies.
What I’d watch next is whether capital keeps flowing into US assets even as growth slows elsewhere.
Wow.
Jensen had a second affair??
The Nvidia board is beginning to oust him?
This is seriously bad news for the company. He has been the sole CEO for over 30 years.
It shows the importance of succession planning for companies.
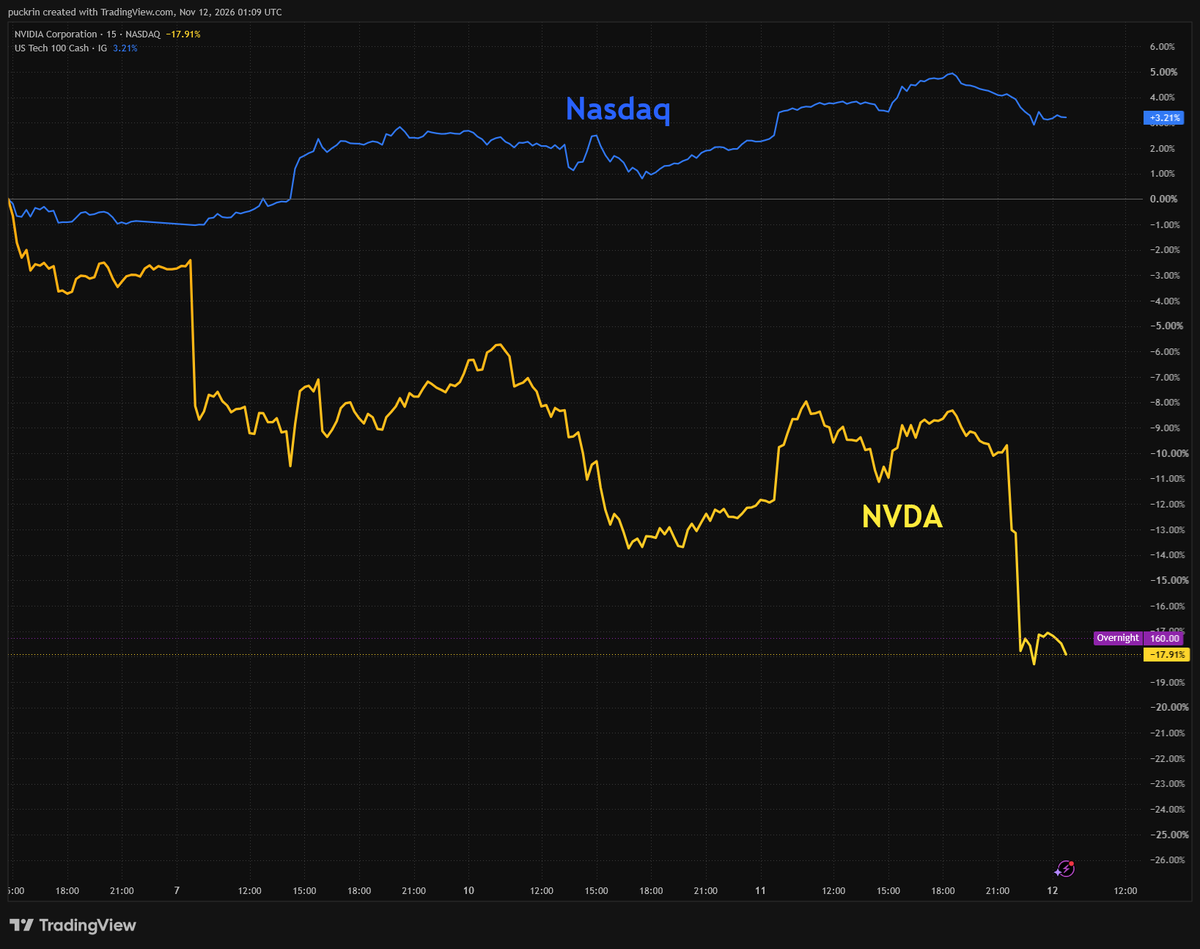
This explains the collapse in $NVDA overnight
📽️WATCH: CoreWeave owes almost $47 billion, and last quarter its interest bill was four times its operating profit.
Yet its stock jumped by double digits after earnings, so who’s right: the stock market or the bond market?👇
Man, the Nvidia story gets crazier.
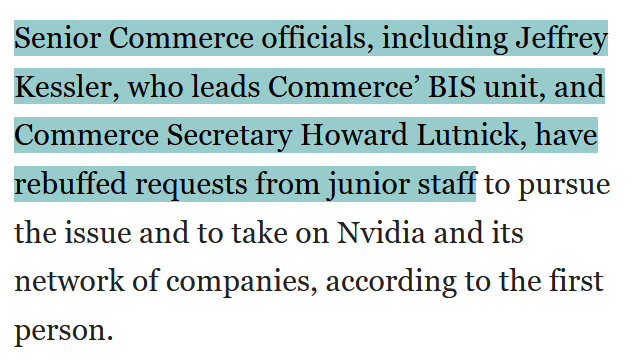
Not only did Trump know about the spy, but so did Lutnick.
He apparently shut down junior staff at the Commerce department who wanted to investigate.
The Dems are going to have a field day next year.
Anthropic’s IPO is multiple times oversubscribed.
A $1.3T valuation, roughly $900B of compute commitments, growth slowing, open weight competition and investors are still fighting for an allocation.
Suppose the markets just decided the "story" is better 🤷♂️
Why am I not surprised...
The bankers on the Anthropic IPO (including Goldman) want to increase the valuation to $1.5T.
That's the valuation many called "a stretch".
It would raise a record $100B for Anthropic and we all know how much the bankers could earn from that.
Quite a coincidence with Goldman's really optimistic forecasts from yesterday.
You don't understand just how exposed AI stocks are to SoftBank right now.
Its stock plunged 10% in oen day on reported Q3 $7B loss, including $3.7B hit from reversing US data-center power-equipment commitments.
They committed to 13+ GW of gas turbines, then lost billions scaling back.
Days prior, Elon Musk alleged SoftBank was defaulting on turbine orders!
Meanwhile:
- $64.6B invested in OpenAI
- Financing costs are 2x from last quarter
- CDS spreads hit a 4-year high
Here's what concerns me:
- SoftBank's bets on AI models, data centers & power all depend on the same spending boom.
- $3.7B loss shows how quickly expected growth can turn into REAL losses today.
- If financing tightens, neoclouds like CoreWeave & IREN could face similar pressure.
The bigger risk?
Billions in infrastructure becoming uneconomical BEFORE launch, threatening AI valuations built on future growth.
The banks are now coming out and saying it.
There's a chance of a 50bp hike in December.
Even Fed officials have said that a core CPI above 0.3% should lead to that outcome - yesterday's came in at 0.4%.
Another governor said they need to "move more rapidly"
Not priced in.
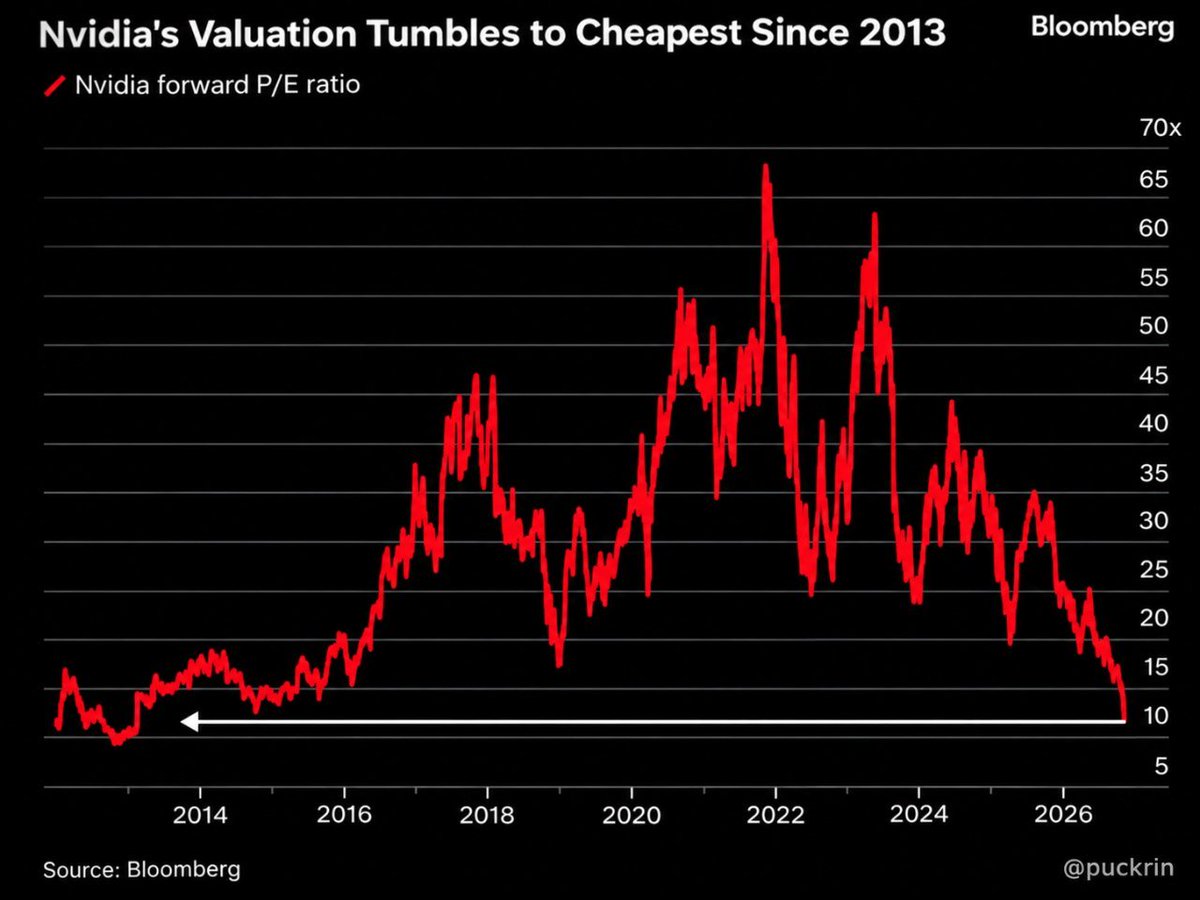
Nvidia is cheap right now.
Its forward PE ratio is at the lowest in 13 years!
Dip buyers have already been buying the premarket dip up 4%.
Is there value here?
And there we go.
Qatar has officially lost one of its long-term gas customers in Europe.
Orlen is a Polish company that had a contract with QatarEnergy till 2034.
All the Force Majure notices QatarEnergy was giving pushed them over.
The Hormuz disruption is costing them dearly.
Yes, CoreWeave's Q3 revenue jumped 168%, but the company still LOST $709M.
A closer look at the numbers explains why:
- $14.5B Q3 capex, nearly 4X revenue
- $46.9B total debt
- $846M net interest expense, over 4X operating profit
- Interest costs exp to top $1B in Q4
- $37B–$39B exp capex in 2026
And the spending doesn't stop there.
CoreWeave still needs billions more in GPUs, data centers & power to deliver on its $132.5B backlog.
What concerns me is that delays or rising borrowing costs could eat into profits before that backlog pays off, even if AI demand stays strong.
You don't understand just how exposed AI stocks are to SoftBank right now.
Its stock plunged 10% in oen day on reported Q3 $7B loss, including $3.7B hit from reversing US data-center power-equipment commitments.
They committed to 13+ GW of gas turbines, then lost billions scaling back.
Days prior, Elon Musk alleged SoftBank was defaulting on turbine orders!
Meanwhile:
- $64.6B invested in OpenAI
- Financing costs are 2x from last quarter
- CDS spreads hit a 4-year high
Here's what concerns me:
- SoftBank's bets on AI models, data centers & power all depend on the same spending boom.
- $3.7B loss shows how quickly expected growth can turn into REAL losses today.
- If financing tightens, neoclouds like CoreWeave & IREN could face similar pressure.
The bigger risk?
Billions in infrastructure becoming uneconomical BEFORE launch, threatening AI valuations built on future growth.
So, just so we're keeping track.
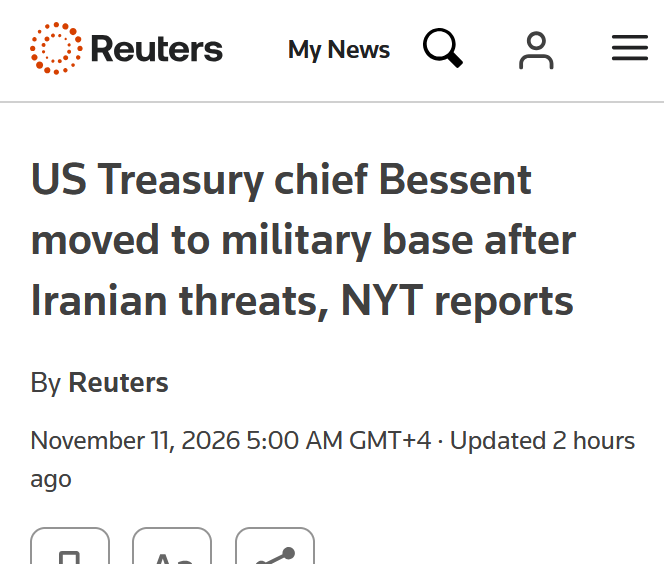
Because of Iranian threats, Trump had to escape Turkey in a catering cart, Bessent had to hide in a military base and the US had to evacuate its UK bases.
Definitely sounds like "winning"
$1 trillion of data centre debt comes due within 5 years.
Most of it sits with just 8 developers with CoreWeave the most at risk.
Banks are getting pickier about who they refinance
& CoreWeave's bonds already yield as high as 15%
The market has started pricing who can't roll their debt and that's perhaps why ING dumped its datacentre loans last week.