Over a decade in Machine Learning and large scale cloud infrastructure, IIT Kanpur, Full time Algo Trader, Founder Niuhi Quantitative Research, NISM-8 Certified
Last few weeks I have been focusing on finding systematic traders who are using algo and ai to trade peacefully. Expect more amazing #face2face in this subject like this one with @ripusingla
Not for entertainment seekers. Only serious traders pls.
https://t.co/1D7NysE7WM
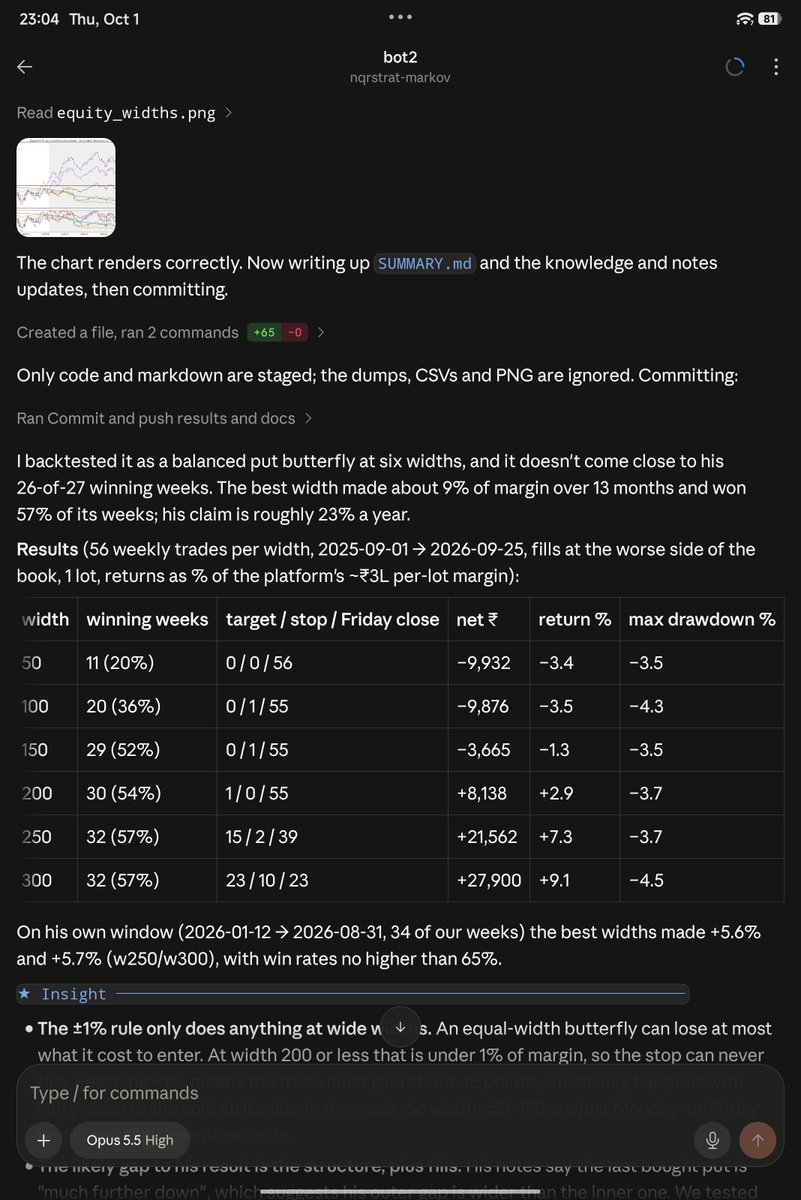
Results on a Rs 10L account for past 3 years :
Trades: 95 | Win rate: 65%
Gross: +Rs 3.62L (+36.2%)
Costs: -Rs 1.98L
Net: +Rs 1.65L (+16.5%, ~4.5%/yr)
Max drawdown: -6.5%
Backtest says different story after costs. Not worth it. Check thread for full report !!!
though we are all excited by AGI and work that gets done by claude/codex but the default mode of even Fable 5.1 is to right highly suboptimal code unless prompted. you give it a 80 core xeon gold cpu + 256gb ram with c, c++, rust, python installed, and ask to write
for you without surfacing and the model's list of apologies start. you ask astra, it says it was focusing on correctness. each prompt current needs explicit inclusion of some "optimal" adjacent keywords for model to consider the time or compute efficiency. these models are too
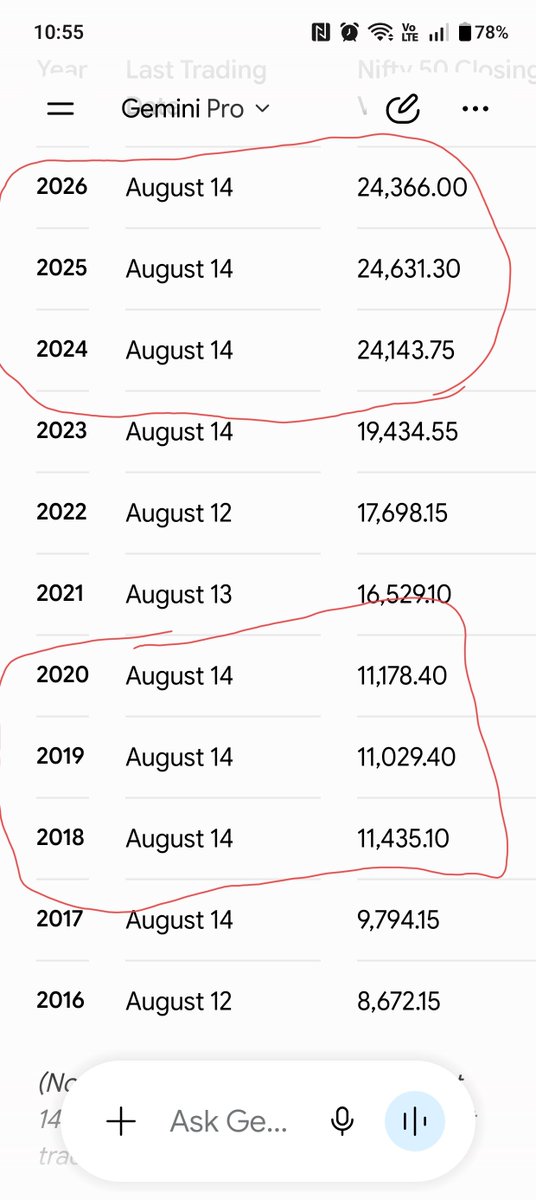
If you invested in Nifty near Independence Day 2024, you would now have approximately the same money and significantly more wisdom.
The returns were inside you all along.
such a stupid default for "cleanupPeriodDays" 30 days @AnthropicAI@bcherny just silently dropping invaluable project jsonl files after 30 days, people do so many different projects, it easily takes 30 days when one may come back only to find all the agent context is gone.
A top quant lost his job due to an AI reasoning model replacing him at his company. He kept applying to different companies and tried his hand at macro writing but to no avail.
Eventually he swallows his pride and talks to his school friend who is now a plumber.
"I understand your old position was a finance maths guy. Why don't you come to our company and apply for a plumber position? You will earn half your old salary but the overtime and the union benefits make up for the rest. But remember, when you apply, tell them that you completed only seven elementary classes. They don't like educated people."
So it happened. The quant got a job as a plumber and his life significantly improved. He just had to seal a screw or two occasionally, and his salary was good enough and he had zero stress.
One day, the board of the plumbing company decided that every plumber had to go to evening classes to complete "basic financial literacy" certification. So, our quant had to go there too. It just happened that the first class was retirement planning. The evening teacher, to check students' knowledge, asked
“If you invest half your money in stocks and half in bonds, how do you calculate the portfolio return?”
The person asked was the quant. He jumped to the board, and then he realized that he had forgotten the formula. He started to reason it, and he filled the white board with He defined a filtered probability space (Ω, ℱ, {ℱ_t}, ℙ) and posited two correlated geometric Brownian motions for the risky and “risk-free” assets. He invoked the Radon-Nikodym derivative to switch to the risk-neutral measure ℚ, then switched back because the question was about realized returns, not prices.
He filled the whiteboard with stochastic discount factors, covariance matrices, CRRA utility functions, and pages of Itô calculus. He derived the wealth process under a self-financing strategy:
dW_t = W_t[(w R_s + (1−w) R_b) dt + w σ_s dB_t^s + (1−w) σ_b dB_t^b]
Then he solved the HJB equation for the optimal allocation, noted that Merton’s solution collapses to a constant weight under log utility, and circled w = ½ as the given constraint.
He invoked the linearity of expectation. He cited Markowitz (1952). He drew a small efficient frontier in the corner for context.
Finally, exhausted, chalk-dusted, eyes wild, he arrived at:
R_p = ½ R_s + ½ R_b
Then forty plumbers, in perfect unison, slammed their wrenches on the desks and roared:
“YOU FORGOT THE VOLATILITY DRAG, YOU FUCKING TOURIST!!”
Last few weeks I have been focusing on finding systematic traders who are using algo and ai to trade peacefully. Expect more amazing #face2face in this subject like this one with @ripusingla
Not for entertainment seekers. Only serious traders pls.
https://t.co/1D7NysE7WM
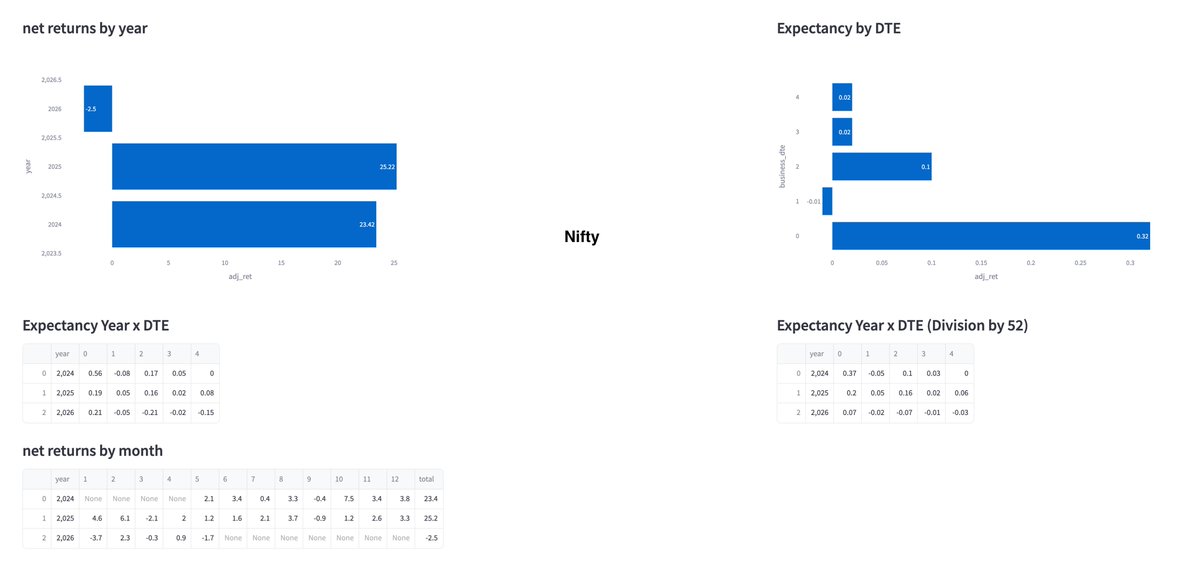
here is some data @PRAFULKULKARN18@Nick_khandelwal
this is very close to what you are describing, intraday delta hedged.
some params , flavours may differ based on preference. returns have been coming down, almost -ve territory
Is pure delta neutral trading currently a negative EV system?
Can anyone simulate if delta hedged short gamma trades are net negative for the year?
"Finding any edge, be it positive or negative, is quite difficult"
If you can get a negative edge, you can simply invert it.