Commercial banks create money, in the form of bank deposits, by making new loans. When a bank makes a loan, it does not do so by giving them ths of pounds of banknotes. Instead, it credits their bank account with a bank deposit the size of the mortgage. Then, new money is created
Three Macro Calls that Aged Superbly
1⃣ Treasuries as the New Plagues of Egypt, April 15: 10 Y Yield was at 4.2%
2⃣ How to enjoy the Japanese Miracle, July 15, JPY was at 163
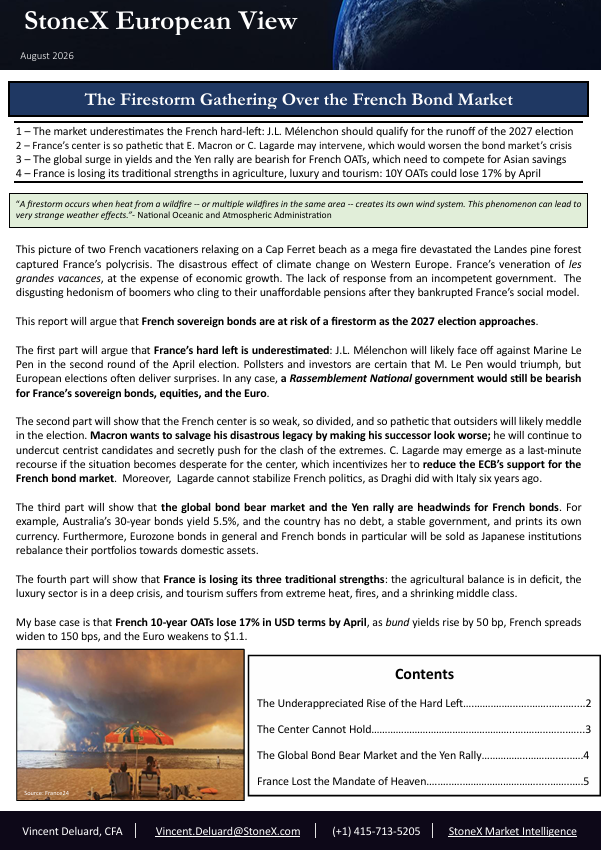
3⃣ The Firestorm Gathering Over the French Bond Market, Aug 12, 10Y OAT was at 3.9%
DM for the reports and sign up for a free trial 👇
https://t.co/VlsIPmOddn
The Ironman Economy
Despite the recent surge in oil prices and weak asset returns, households continue to cut their savings to support spending growth above income growth.
https://t.co/DL1gATrF8L
Moim zdaniem jeśli wreszcie nie porozmawiamy uczciwie jakim cudem w Polsce możemy utrzymywać przez 3-4 lata deficyt na poziomie wyraźnie powyżej 6% PKB bez wyskoku inflacji, czy zadłużenia zagranicznego, to będziemy bez końca bładzić we mgle agregatów fiskalnych.
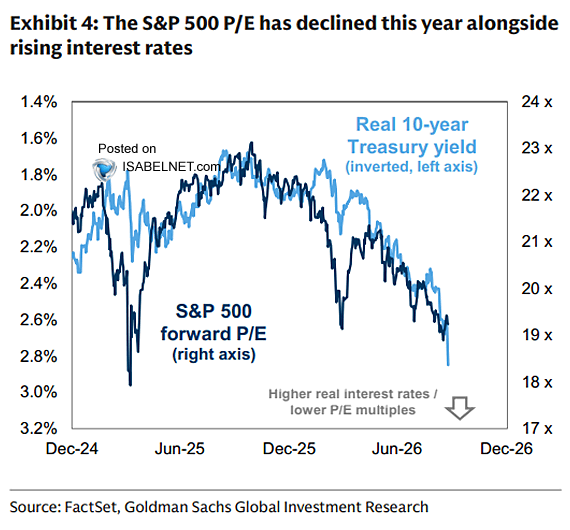
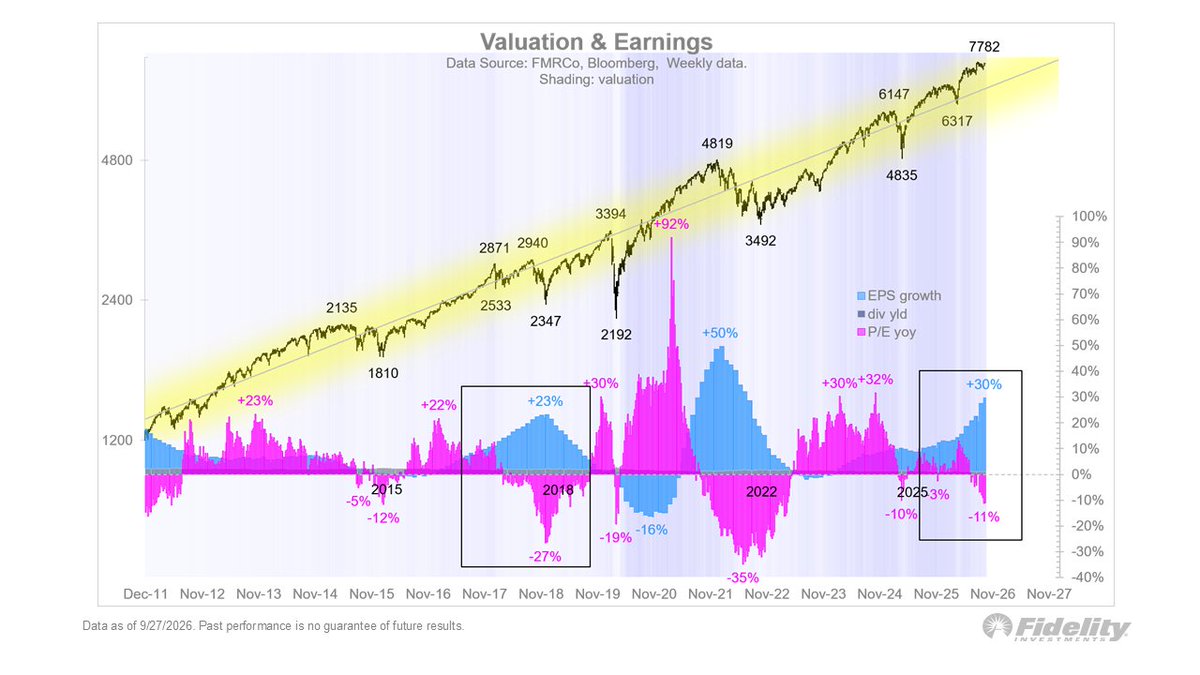
Earnings are still booming, which is good news considering that investors are no longer willing to pay high multiples for those earnings. I think it’s a combination of peak earnings growth and rising rates (per the Fed model).
🇺🇸 S&P 500
So far this year, rising real yields have forced the S&P 500's multiple lower, a classic setup where higher discount rates squeeze P/Es without necessarily triggering a price collapse
👉 https://t.co/yIk7SZYWVX
@GoldmanSachs $spx #spx#stocks#equity#yields#rates
@KamilZamojc I tak powiększałą się ilość banknotów w obiegu bez zawracania nikomu głowy ;-) W Szkocji słyszałem, że to złotnicy z Royal Mile w Edynburgu rozpoczęli ten proceder. Frisby jest Angielczykiem więc ten początek widzi w City.
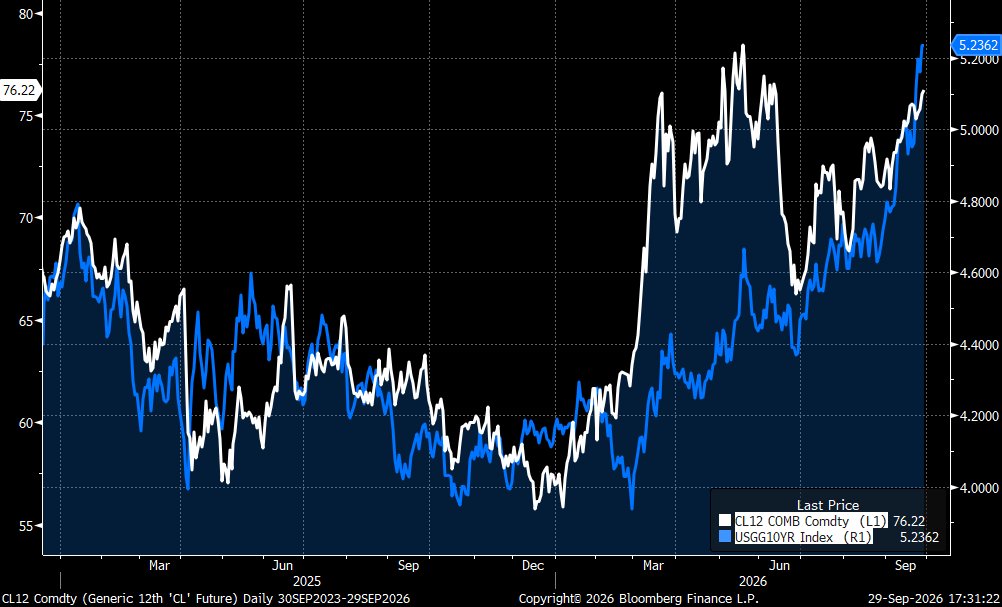
Oil and rates continue to rise together ... see the chart of 10yr yields vs 12m oil contract price. The front-end of the oil curve might be more noise than signal still.
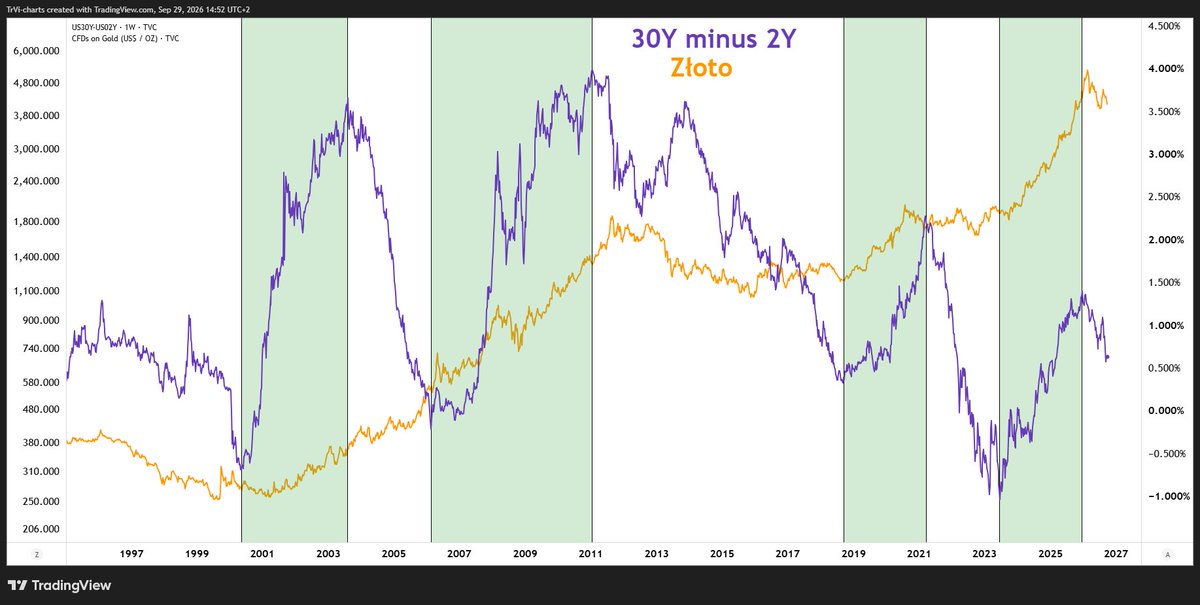
Złoto co do zasady nieźle radzi sobie w okresach wystramiania krzywej dochodowości obligacji.
Bardziej preferowanym scenariuszem jest jednak sytuacja, gdy wystromienie krzywej odbywa się poprzez spadek rentowności z krótkiego końca, niż poprzez ich wzrost z długiego końca (https://t.co/PHc50UyZuG. rosnące długoterminowe oczekiwania inflacyjne).