

Search results for data center
People

Doug "Censor" Martin 
@Censor

cented the hodler
@Cented7

Cisco Data Center and Cloud
@ciscoDC

AMD Data Center
@AMDServer

Data Center Contractor Report
@DCCReport

Regarding Data Centers
@RegardingDC

Data Center Knowledge
@datacenter

CENTR
@CENTR

Lenovo Data Center
@Lenovodc
NYU Center for Data Science
@NYUDataScience

ST Telemedia Global Data Centres (India)
@sttgdcindia

Cenpec
@cenpec

Data Center News
@datacenter365
CentOS Project
@CentOS

CENT
@Cent

National Snow and Ice Data Center
@NSIDC

OCHA Centre for Humanitarian Data
@humdata

CEN
@CENTWT

Center for Data Innovation
@DataInnovation

CENIEH
@CENIEH
Tweets including data center

Nvidia $NVDA just raised its outlook for next year on the earnings call, and it did it off a bigger base.
Interim CEO Colette Kress, about 5:05 PM ET:
"We are raising our fiscal year 2028 outlook. We expect revenue to grow approximately 75% year over year, up from 70% and off what is now a higher fiscal 2027 base."
Market consensus had fiscal 2028 growth at about 70%, with sales topping $690B. Nvidia is now guiding above that.
What she said is behind it:
"supply agreements extending through to the end of the decade"
Hyperscale revenue of $60B, up 23% sequentially, "driven by the Vera Rubin ramp and sustained strength in Grace Blackwell"
Data Center up 21% quarter over quarter to $108B
"Cloud industry backlog now sits at $2.5 trillion."
Hyperscale customers' cloud revenue growth "accelerated for the 6th consecutive quarter"
She also tied the outlook to three things it depends on: "data center readiness, the strength and durability of end customer demand, and our customers' access to capital."
Why it matters: this is the number that answers the post Jensen question. Revenue for the next year was supposed to be largely contracted already, and the interim team just moved it higher instead of playing it safe. The catch is in her own wording. Power, construction and customer financing now decide how much of that 75% shows up.
$NVDA $TSM $MU $CRWV $ORCL


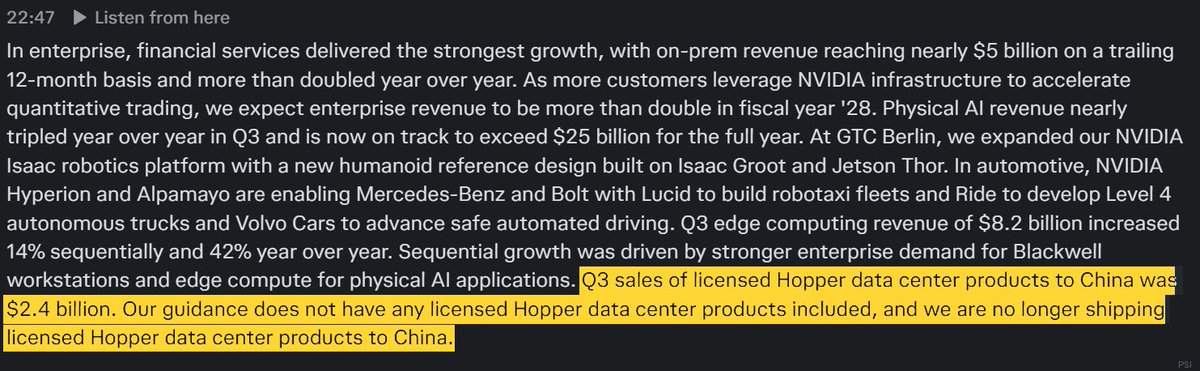
$NVDA sold $2.4B of licensed Hopper data center products to China in Q3.
On the call, management said Q4 guidance includes none of it and NVIDIA is no longer shipping licensed Hopper data center products to China.
$NVDA said on the call its compute remains fully utilized across every hyperscaler and neocloud it serves.
Neoclouds $CRWV, $IREN and $NBIS were named among the companies working with NVIDIA on OpenShell, its new agent safety stack.


NVIDIA INTERIM CEO: NO LONGER SHIPPING LICENSED HOPPER DATA CENTER PRODUCTS TO CHINA

NVIDIA INTERIM CEO: NO LONGER SHIPPING LICENSED HOPPER DATA CENTER PRODUCTS TO CHINA
Note: Hopper shipments to China 🇨🇳 were $2.4 billion in the third quarter, and Nvidia's Q4 outlook assumes no data center compute revenue from China.

Nvidia just posted a record $115.8 billion quarter, double last year, with $65.3 billion in profit. It's their first report since Jensen Huang resigned. And their forecast counts on zero data center sales to China.

Atención : @EPMestamosahi incursionaría en el negocio de la Inteligencia Artificial, generando energía para los data center, así lo anunció el @AlcaldiadeMed @FicoGutierrez


$NVDA reported. The short version: a clear beat, a guide that’s about in line, and a chart that hasn’t decided anything yet.
The numbers:
Revenue $115.8B vs. a $108B ±2% guide, data center $107.6B
EPS $2.68 vs. $2.47 expected
Q4 guide $130B ±3%. Roughly what the Street wanted, but Q4 has an extra week, and gross margin is guided down to 71–72% from 74.9%
Still no China data center revenue assumed
The “$150B buyback” making the rounds was added in September. New this quarter: $28.1B returned
The chart: today closed at 155.46, the first daily close under the quarterly S3 at 155.92. After hours it spiked to about 161.5 and stalled right under the yearly pivot at 161.77. Now 158.33.
That’s the same line as in my article. A weekly close above 161.77 puts the relief path in play. Below it, the road leads to the 105–112 zone.
The chart shows the Match from the article, the path I lean towards. A: down to 111.59, right at the yearly S1 (111.35). B: the bounce that convinces everyone, up to the 0.882 at 228.04. C: down to the −0.618 at 29.99, right where the 0.882 of the whole 2022–26 run sits at 37.80, with the yearly S2 at 36.20. That’s years, not weeks.
A good quarter doesn’t change the line. Friday’s weekly close decides.
Disclosure: I’m long $SOXS (3x short semis), no $NVDA position.
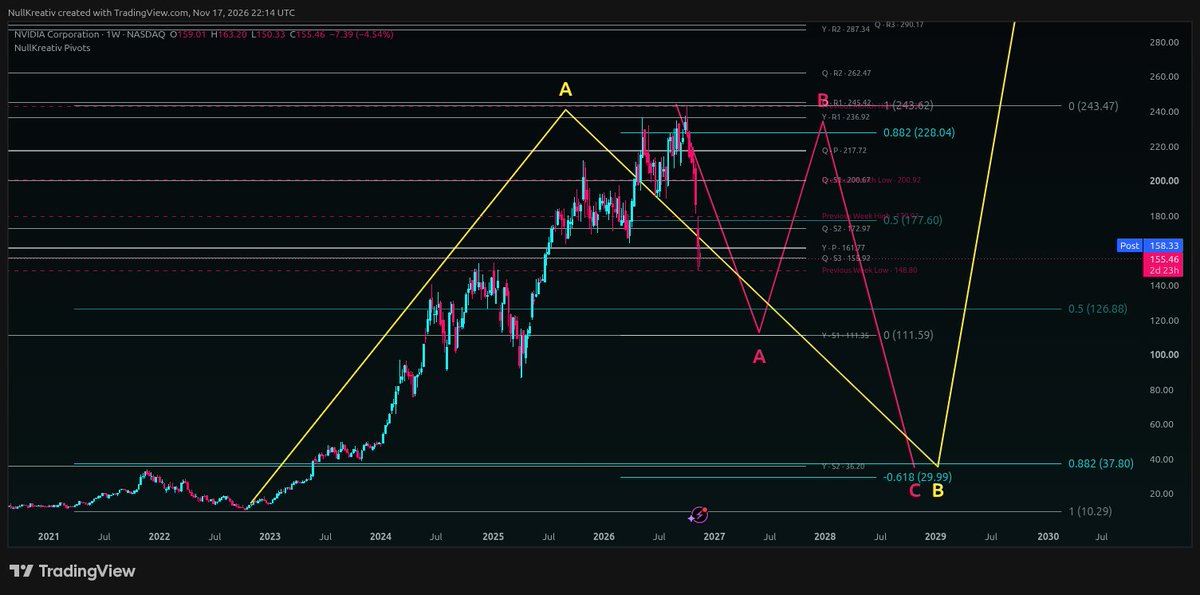
$NVDA closed at 156.14 today, about 5.60 under the yearly pivot at 161.77. Friday was a dollar above it. That’s why I didn’t call a path on Friday.
It’s still a weekly question, and earnings land tomorrow after the close. Below: last week’s low at 148.80, then the monthly S3 at 146.80. Above: 161.77 is the first thing to win back.


$NVDA
Os números são difíceis de ignorar:
Receita: US$ 115,8 bilhões, alta de 103% em um ano.
Data Center: US$ 107,6 bilhões, alta de 110%.
Lucro líquido: US$ 65,3 bilhões.
Projeção para o próximo trimestre: US$ 130 bilhões, com margem de variação de 3%.
A receita veio acima até do teto da projeção anterior da própria NVIDIA, que era de US$ 110,16 bilhões.
A empresa também tem uma autorização adicional de US$ 150 bilhões para recompra de ações. Importante: essa autorização já havia sido anunciada e não significa que os US$ 150 bilhões foram comprados agora.
Tem um detalhe na projeção: o próximo trimestre terá uma semana a mais. Não dá para comparar os US$ 130 bilhões diretamente com os US$ 115,8 bilhões sem considerar isso.
O negócio continua crescendo em uma escala que poucas empresas conseguem acompanhar. Mas resultado forte e ação subindo são coisas diferentes.
Eu sigo comprado, e vou aumentar a mão se vier para baixo. Não existe motivo para vender.

Memphis residents can apply for home improvements funded by the data center taxes. Now make it affordable housing.

SpaceXSI is committed to helping build and grow the communities our employees live and work in for the better. This includes ensuring revenue from the taxes we pay goes back into the community.
The City of Memphis is investing $3.26 million of the direct revenue from our supercompute facilities in Memphis toward housing, neighborhood improvements, and other services for local residents, helping them to make critical repairs and improvements to their homes → https://t.co/M5Ho464DOl

7 DAY SUMMARY
Tech is the story of the week. Nvidia’s Jensen Huang resigned after an affair with an alleged Chinese spy surfaced — the stock’s lost about seven hundred thirty-five billion in market value, the SEC is probing, and Huang publicly offered to come back if the board asks. Earnings drop after the bell today. Meanwhile Anthropic prices its IPO tomorrow, targeting up to ninety billion raised at roughly a one-point-five trillion valuation — the biggest test yet of whether the AI boom is real. Software’s already cracking: Salesforce down nine and a half percent after reportedly putting monthly budgets on employee AI tool use because token costs blew up last quarter. Upwork’s cutting thirty-seven percent, Atlassian ten percent, Canva twenty-two, Qualcomm fifteen hundred in India.
Finance: JPMorgan named Bregje de Best as its next CFO. Deutsche Bank dropped six percent on leaked records tying it to Epstein, Russian oligarchs, and Trump. The dollar’s near a nineteen-month high, and Fed minutes come Wednesday with a near-certain December hike priced in.
Healthcare: AstraZeneca cut six hundred US jobs in respiratory and immunology. Calidi’s slashing sixty-seven percent of its staff. Vertex dropped ten billion on Crinetics. Merck raised its dividend.
Energy: Chevron’s near a five-billion-dollar deal for a Blackstone-backed offshore producer. Brent’s around ninety-three on tanker attacks in the Middle East. Siemens Energy posted record revenue and its CEO is all-in on US data center buildout.
Retail and consumer: Home Depot’s CFO is taking over as CEO after a rough outlook, stock down two and a half. Amazon launched a prepared-meals line under eight bucks. PepsiCo’s cutting a thousand North American jobs. Nike fell six percent.
Aviation and auto: Boeing’s cutting twenty-five hundred commercial airplane roles. Renault’s cutting up to a thousand in France. Bosch’s trimming seven-fifty in its mobility division.
Telecom: Vodafone Germany’s cutting twenty-three hundred. Comcast a thousand. BT already finished shedding nearly eight thousand earlier this month.
Media: Disney confirmed more layoffs chasing three billion in annual savings by fiscal twenty-nine.
The thread tying it together: companies are cutting people to fund AI spend at the exact moment the market’s questioning whether that spend pays off. Nvidia’s scandal plus Anthropic’s debut is the pressure valve on that thesis this week.
One angle worth pulling: the California AG is also suing OpenAI over a cyberattack on Hugging Face it calls entirely foreseeable. That case could set the liability standard for every AI lab going forward.
AI disruption. Not job cuts from AI — the fear that a competitor using AI will eat their lunch before they can deploy it themselves. That’s why you’re seeing the weird split: companies laying off people to fund AI investment at the same time. The second thread is talent. Whoever locks up the best AI engineers wins, so retention and poaching became a board-level fight.
One angle worth pulling on: the CEOs who talked about AI as a cost-saver two years ago are now the ones getting replaced. The ones who framed it as existential — like Jensen Huang did — are the ones still standing, at least until last week.
True, and it’s self-serving in two directions. Externally it justifies buying more AI software and cloud contracts — which conveniently flow to the same vendors funding the hype. Internally it gives cover for layoffs they’d make anyway for cost reasons. The narrative does a lot of heavy lifting for people who benefit either way.
The part worth watching is when the incentive flips — like when AI starts producing work that directly competes with what the CEO’s own company sells. That’s when the honest conversation starts.
Yeah, it’s a loop. Fear drives the budget, the budget funds the vendors, the vendors publish the scare stats, and the cycle restarts. The one thing nobody’s asking is whether the ROI actually shows up on a P&L.


Y'all believe all you want but I don't believe shit from Jay Clayton, the National intelligence center or data centers I'm just here wondering how tf am gonna get my cake up with all these Cyber attacks 🤔 put a nigga ON! 🅿️

@Polymarket SpaceX turning the sky into a data center by 2029 is either the future we wanted or a very expensive glow stick.

🚨 $NVDA just DOUBLED its revenue… and that’s not even the biggest headline this week 👀
💰 𝗥𝗲𝘃𝗲𝗻𝘂𝗲: 𝟭𝟭𝟱.𝟴𝗕$ (+𝟭𝟬𝟯% 𝗬𝗼𝗬)
Up from 57.0B$ a year ago. Yes, more than double.
🚀 𝗩𝗲𝗿𝗮 𝗥𝘂𝗯𝗶𝗻: 𝗳𝗮𝘀𝘁𝗲𝘀𝘁 𝗽𝗿𝗼𝗱𝘂𝗰𝘁 𝗿𝗮𝗺𝗽 𝗶𝗻 𝗡𝘃𝗶𝗱𝗶𝗮’𝘀 𝗵𝗶𝘀𝘁𝗼𝗿𝘆
It added nearly 20B$ in revenue in just one quarter.
🏢 𝗗𝗮𝘁𝗮 𝗖𝗲𝗻𝘁𝗲𝗿 𝗸𝗲��𝗽𝘀 𝗳𝗶𝗿𝗶𝗻𝗴
Hyperscale: 60.1B$ (vs 35.1B$)
AI Clouds, Industrial & Enterprise: 47.5B$ (vs 16.1B$), almost 3x
📈 𝗣𝗿𝗼𝗳𝗶𝘁𝗮𝗯𝗶𝗹𝗶𝘁𝘆
Gross margin: 74.8%
Net income: 65.3B$
EPS: 2.70$ (+108%)
💵 𝗙𝗿𝗲𝗲 𝗰𝗮𝘀𝗵 𝗳𝗹𝗼𝘄: 𝟰𝟯.𝟴𝗕$
A record ~28B$ returned to shareholders, with ~227B$ in buybacks still authorized through FY28.
🔮 𝗤𝟰 𝗴𝘂𝗶𝗱𝗮𝗻𝗰𝗲: 𝟭𝟯𝟬𝗕$ (±𝟯%)
⚠️ Fine print: it includes an extra week, excludes Data Center sales to China, and the gross margin guide drops to 71–72%.
👑 𝗣𝗹𝗼𝘁 𝘁𝘄𝗶𝘀𝘁: 𝗝𝗲𝗻𝘀𝗲𝗻 𝗛𝘂𝗮𝗻𝗴 𝘄𝗮𝗻𝘁𝘀 𝗵𝗶𝘀 𝗷𝗼𝗯 𝗯𝗮𝗰𝗸
Days after resigning as CEO, Huang broke his silence today with a statement saying he would be “honored” to return if the Board decides it’s in the best interest of shareholders, employees, the company and America. A petition to bring him back has passed 180,000 signatures, but according to CNBC sources the Board is not currently considering it. For now, CFO Colette Kress remains interim CEO.
A $SPX500 and $NSDQ100 heavyweight doubling revenue while its founder is outside the building… 🤯
❓ Should the Board bring Jensen back, or is it time for a new era at Nvidia? 👇
Sources: NVIDIA Q3 FY27 Investor Presentation, NVIDIA press release (Nov 12), CNBC. Not investment advice.

$NVDA just said “Hold my beer”!!!
• Revenue $115.8B vs $108.7B est ✅
• EPS $2.68 vs $2.47 est ✅
• Data Center $107B vs $102B est✅
• Gross Margin 75% vs. Est. 74%✅
Q4 Guidance
• Revenue $130B vs $125B est✅


$NVDA primer balance sin Jensen Huang: los números de siempre, el balance de otro.
Facturó USD 115.800M (+103%), Data Center USD 107.600M (+110%) y guía USD 130.000M para el próximo trimestre, sin China. "Nuestro impulso es real", dijo Colette Kress, CEO interina.
Pero abajo del titular:
▪️ Deuda de largo plazo: de USD 7.500M a USD 32.400M en nueve meses
▪️ Cuentas por cobrar: de USD 38.500M a USD 81.000M
▪️ Inversiones en empresas no cotizantes: de USD 22.300M a USD 65.500M
▪️ El margen bruto baja de 74,8% a 71–72% en la guía.
Nvidia vende más que nunca, cobra cada vez más tarde e invierte en los mismos clientes que le compran. Es el nuevo soberano del que hablamos en el Newsletter, y también se financia con deuda.
#Nvidia #NVDA #IA #Merlin #Mercado

@teslayoda Good framing. Feels like both come down to manufacturing speed more than tech at this point. Which one do you think hits a bottleneck first: Cybercab ramp or SpaceX's data center buildout? That probably decides which way any merger ratio gets argued too.

𝐍𝐯𝐢𝐝𝐢𝐚 𝐣𝐮𝐬𝐭 𝐩𝐨𝐬𝐭𝐞𝐝 𝐢𝐭𝐬 𝐟𝐢𝐫𝐬𝐭 𝐞𝐚𝐫𝐧𝐢𝐧𝐠𝐬 𝐰𝐢𝐭𝐡𝐨𝐮𝐭 𝐉𝐞𝐧𝐬𝐞𝐧 𝐇𝐮𝐚𝐧𝐠.
$115.8 billion in one quarter.
Wall Street expected $109.3 billion.
Data center alone made $107.6 billion.
Next quarter guided at $130 billion, plus a $150 billion buyback.
The machine didn't even blink.
Does the board still say no to Jensen's return?


🚨 BREAKING
The European Bank for Reconstruction and Development has warned that emerging economies risk missing out on the global AI and defense investment boom, Reuters reports. In nearly half of the bank's countries, electricity grids cannot support even one data center.

@heyshrutimishra insane numbers china exclusion makes guidance conservative vera rubin ramp speed unprecedented watch data center revenue trajectory next quarter coreweave deployment validates demand