This is not especially surprising. The broader market has been driven by semiconductors and the hyperscalers. Look at the S&P 500 excluding Tech and it is hard not to argue we have been in a stealth bear market.
#SmallCaps#SP500#MarketBreadth#Semis#Hyperscalers
Morning Coffee Macro | Tuesday, September 29, 2026
Hormuz reopen hopes are fading into the week after President Trump rejected Iran's seven-day truce offer over the weekend. Mediators are still shuttling messages, but Washington and Tehran remain stuck on sequencing: Iran wants sanctions relief and an end to the port blockade before any strait reopen, while the US wants the nuclear file addressed in any deal. That stalemate keeps a geopolitical premium in crude, with Brent holding above $107 and WTI near $94 after another overnight bid.
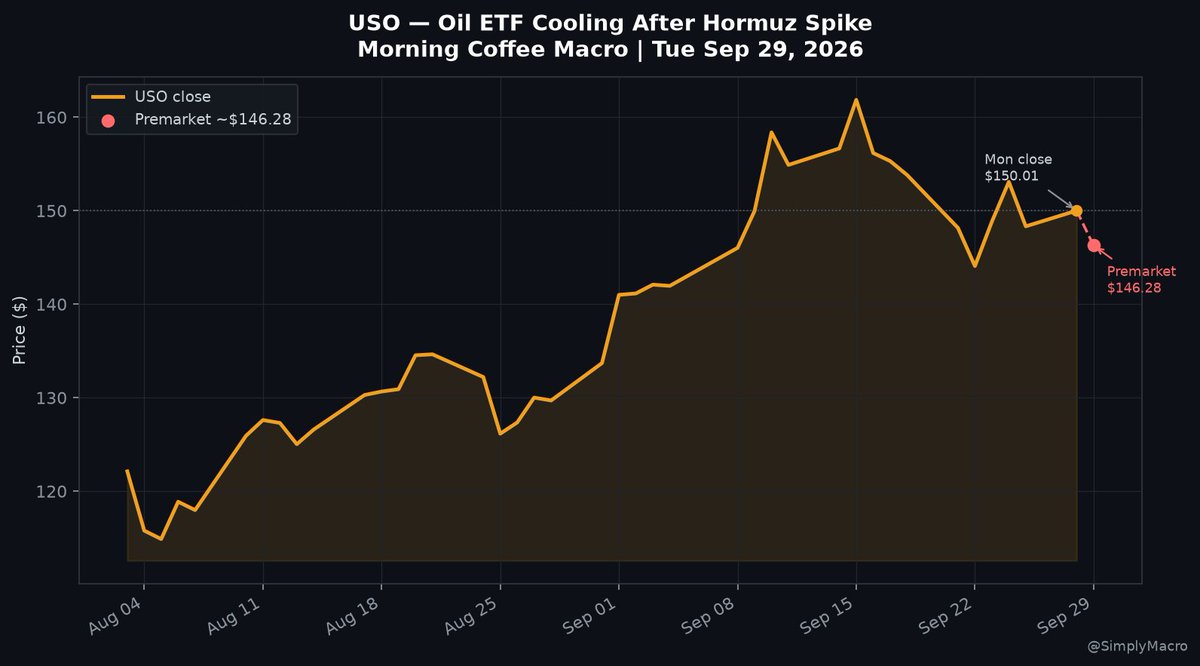
That oil hangover is still the main macro story, even as US oil proxies cool in the premarket after Monday's spike. USO is near $146 (about 2.5% under Monday's close near $150), and XLE is soft near $61.50, while the 10-year Treasury yield remains elevated after printing above 5.27% on Monday, its highest in about 19 years. Australia's RBA just hiked another 25 bp to 4.6%, a 15-year high, explicitly citing fuel-driven inflation, a clear echo of the same oil shock hitting global central banks.
Equity futures are trying a modest bounce after Monday's Wall Street slide (S&P 500 closed roughly 0.8% lower). Premarket, SPY is near $767.50 (prior close $765.61), QQQ near $739.80 (prior close $736.53), DIA near $515.60, and IWM near $281. Asia stayed heavy overnight, with the Nikkei off about 1.3% and the Hang Seng about 0.6%. Traders are marking the calendar for this week's US data stack, including PCE and Friday's jobs report, with markets still pricing a solid chance of another Fed hike in October.
Crypto is steadier than the overnight oil tape but still trading the same higher-for-longer rate backdrop. Bitcoin is marked near $84,300 (prior day open near $83,200), and Ether near $2,730, holding the low-$83k support zone after last week's fade from the mid-$86ks. Risk appetite is fragile: yields near multi-year highs raise the hurdle rate for non-yielding assets, so crypto stays pinned to the bond and oil narrative until PCE lands.
On the dollar side, DXY is firm near 101.2 as hike odds stay bid. EUR/USD is soft around 1.136, and USD/JPY sits near 157.4 to 157.5, still short of the 160 intervention watch zone. Gold is attempting a bounce (GLD near $381 after Monday's selloff) even as real yields stay high, a reminder that geopolitics and rate fears are pulling safe havens in opposite directions.
Simply Macro Explanation
Oil and Hormuz diplomacy still set the tone. As long as the strait stays constrained and crude holds three digits, inflation fears keep yields elevated, the Fed hike path alive, and risk assets on a short leash. Today's modest equity and crypto bounce is a pause, not a regime change. Watch PCE and payrolls this week for the next real swing.
#MorningCoffeeMacro #Markets #Macro #Oil #Hormuz #Fed #Bitcoin
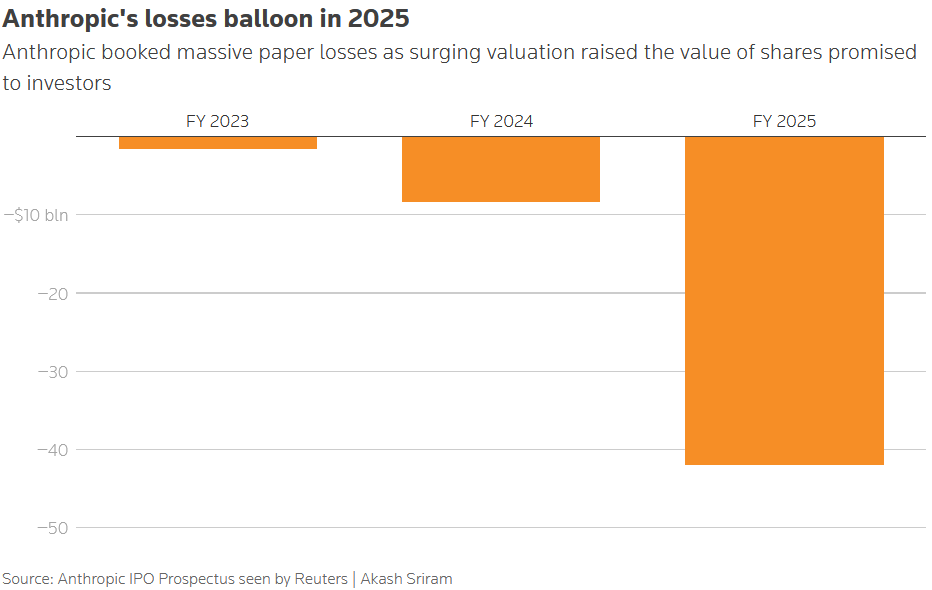
It's official: Anthropic has filed for its IPO.
It's targeting a $2 TRILLION listing, but the details in the financials matter:
In 2025, it had a net loss of $42 Billion and it plans $518B in cloud compute in the coming years.
With losses like that, no wonder they need to keep raising money to meet that spend...
BREAKING: Iran has agreed to halt uranium enrichment in exchange for US sanctions relief, per Al Hadath.
The news comes minutes after reported indicated that President Trump is willing to give Iran sanctions relief and release Iranian frozen funds in return for "concrete steps" regarding their nuclear program.
Oil prices turn negative on the day after the news.
BREAKING: Bond market flips into higher-for-longer mode as October Fed hike odds jump to about 68%
Markets are no longer treating last month’s Fed move as a one-and-done. Futures now imply about a 68% chance of a second straight hike at the late-October meeting, with roughly 90 basis points of tightening priced through late next year.
That front-end pricing is showing up in the tape. The 2-year yield is up about 5 bps near 4.91%, on track for its largest monthly rise since February 2023 (about +56 bps in September). The 10-year sits near 5.22%, and the 30-year has pushed toward levels last seen in 2004.
Duration is taking the hit in real time. TLT is down roughly 1% near $78.50, intermediate Treasuries are softer, and gold is getting crushed as real yields climb, with GLD off more than 3% near $379. Growth equities are feeling the cost-of-capital squeeze too: QQQ is lower near $739 and SPY near $768 as Nasdaq led the overnight slide.
Oil’s Hormuz-driven spike is the inflation accelerant behind this rates repricing, but the midday market story is the bond market itself rewriting the Fed path into a higher terminal rate. Hyperscaler AI spend funded with heavy borrowing is the quiet risk that gets louder every time the front end sells off. PCE on Wednesday and Friday’s jobs report are the next two checkpoints before October.
Simply Macro Explanation
Traders are betting the Fed hikes again in October, not pauses. Higher oil keeps inflation risk alive, so yields stay elevated, bonds and gold sell off, and expensive growth stocks get pressured. Watch PCE and payrolls for whether those 68% hike odds stick.
#Fed #Rates #Bonds #Macro #Markets #TLT #SimplyMacro
🔥UPDATE: Public companies Strategy and Strive just SCOOPED UP another $232 MILLION in Bitcoin.
Michael Saylor’s Strategy bought 1,666 BTC worth $138 MILLION.
Strive also added 1,107 BTC last week at an average price of $85,396, bringing its total holdings to 27,462 BTC.
Together, the two companies added 2,773 BTC.
Morning Coffee Macro | Monday, September 28, 2026
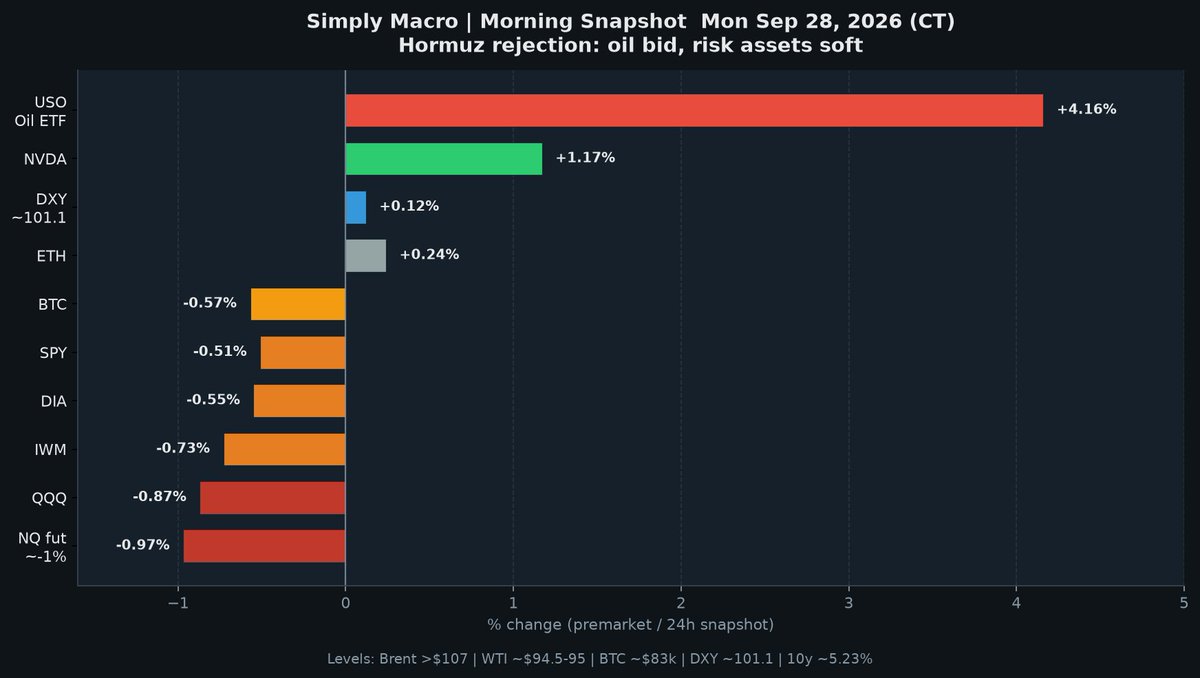
Hormuz diplomacy took another hit over the weekend. President Trump rejected Iran's seven-day plan to reopen the Strait of Hormuz (sanctions relief, frozen funds, and an end to the naval blockade in exchange for a reopening and nuclear talks), and Tehran says it will not soften those terms. Oil is pricing the snub: Brent pushed above $107 and briefly toward $108, WTI is firmer near $94.50 to $95, and USO is up roughly 4% in premarket near $154.50. Talks could still resume this week, but the energy premium is back in the driver's seat.
That oil shock is the bridge into a soft equity open. Nasdaq is leading the downside, with NQ futures near 30,590 (about -1%) and QQQ down roughly 0.9% premarket near $738. ES sits around 7,770 (about -0.5%), SPY is near $767 (-0.5%), DIA near $515 (-0.55%), and IWM near $280 (-0.7%). One bright spot: Nvidia announced a record $150 billion buyback expansion and is greener in premarket near $228 even as the broader tech complex stays under pressure.
Risk appetite is also cooling in crypto after last week's bounce. Bitcoin is trading near $83,000 this morning (CoinDesk had it briefly under $82,600 overnight), ETH holds around $2,665, SOL is softer near $118.50, and DOGE is near $0.093. ZEC and higher-beta alts are leading the washout as traders reprice sticky oil, a firmer dollar, and higher odds of another Fed hike into Wednesday's PCE and Friday's jobs report.
The dollar and yields are reinforcing that same risk-off loop. DXY holds above 101 near 101.10 to 101.17, EUR/USD is testing support around 1.1325, and USD/JPY is firmer in the mid-157s. The 10-year is still near 5.23%, keeping duration and growth assets on a short leash into the U.S. cash open.
Simply Macro Explanation: Trump's Hormuz rejection lit oil back up above $107, and that inflation scare is dragging Nasdaq futures, crypto, and the euro lower while the dollar and 10-year stay elevated. Until diplomacy softens or PCE/payrolls cool the hike scare, Monday opens defensive.
#MorningCoffee #Macro #Markets #Geopolitics #Hormuz #Oil #Crypto #Forex #Fed
It's official.
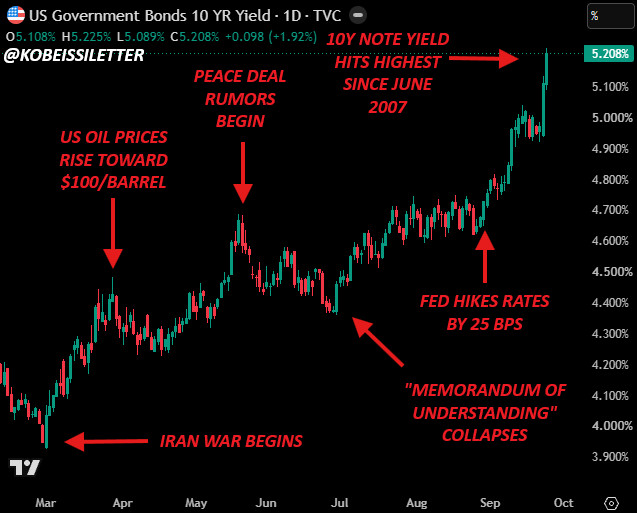
As the bond market "meltdown" accelerates, the average interest rate on a 30Y mortgage in the US is up to 7.45%.
That's up +150 basis points in 6 months and the highest since 2023, when inflation was at 6.4%+.
What is happening? Let us explain.
(a thread)
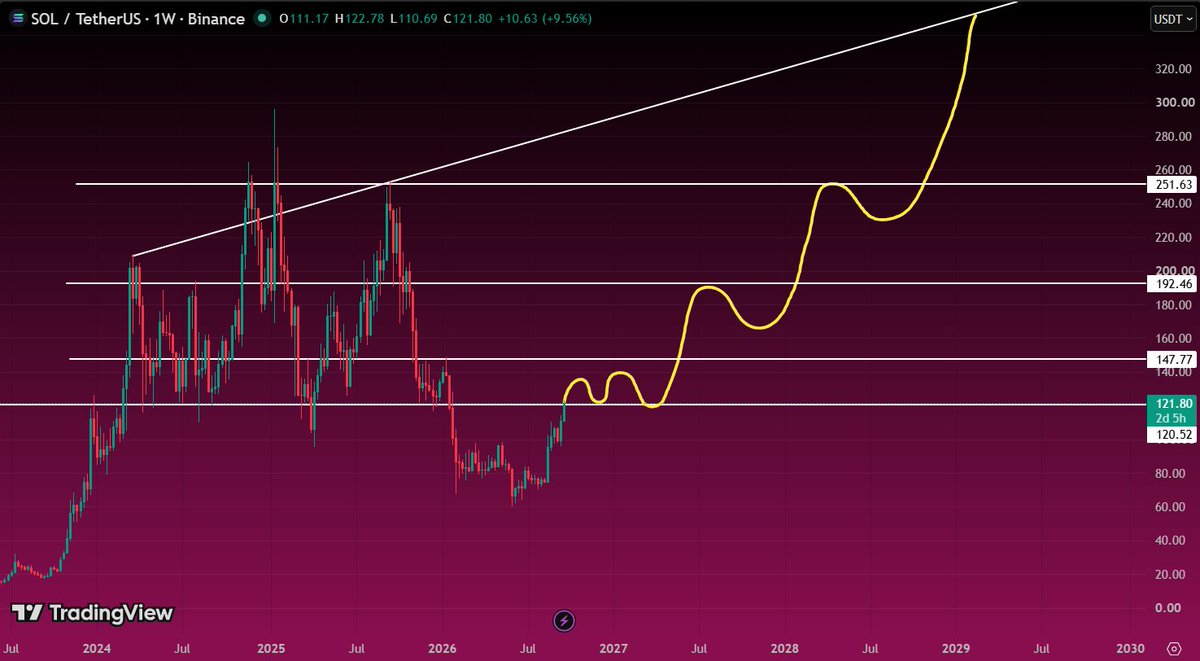
🟣 $SOL IS FIGHTING FOR A MAJOR BREAKOUT
$SOL is now trying to break above the $120-$121 resistance area.
If price can close above it and hold, the next levels I’m watching are:
$148 → $192 → $252
Above $252, the chart starts opening up much more aggressively toward the long-term upper trendline.
For now, everything starts with this breakout.
Break $120. Hold it. Then the bigger move can begin.
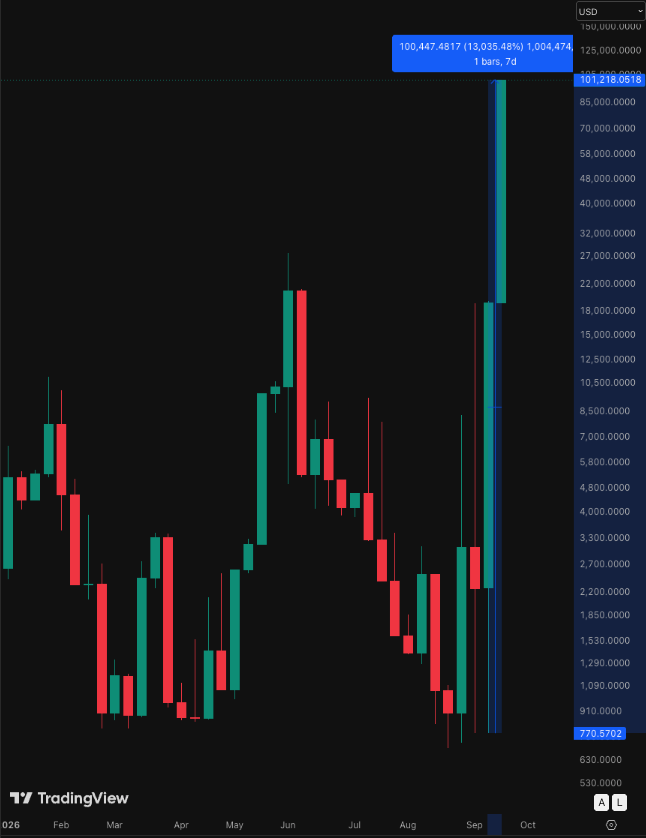
🚨ALERT: ETH bears are going ALL IN on Bitfinex.
ETH short positions have EXPLODED by roughly 13,000% in just TWO WEEKS, surging from around 771 ETH to over 101,000 ETH.
That is an EXTREME buildup in bearish positioning, and it could become POWERFUL short-squeeze fuel if $ETH moves higher.
Treasury Secretary Scott Bessent said Federal Reserve policymakers should keep an “open mind” on interest rates, arguing that productivity gains from artificial intelligence and deregulation will help keep US inflation in check. https://t.co/isIAO2nY2P
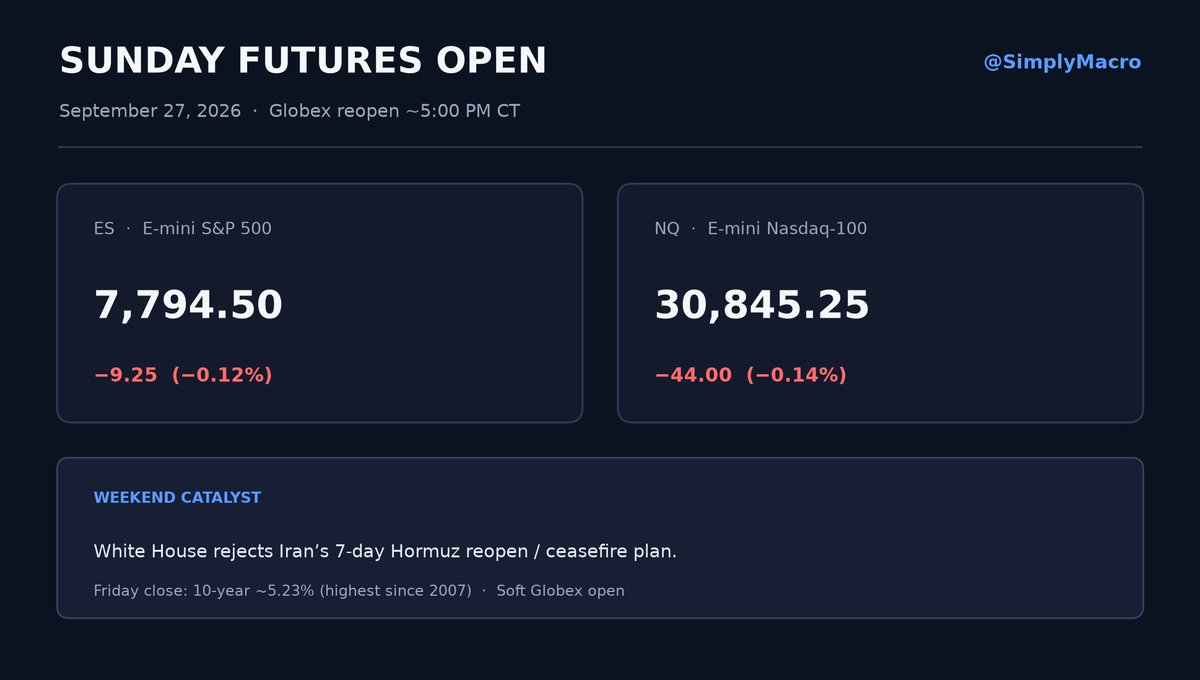
Sunday Futures Open
September 27, 2026
Weekend catalyst: The White House rejected Iran's seven-day plan to reopen the Strait of Hormuz and enter a ceasefire. Hormuz stays a policy valve, not a timed reopen. That keeps the energy-risk premium in play into the new week, even after Friday's oil slip on earlier truce talk.
Open prints (Globex, around 5:00 PM CT):
ES 7,794.50 (−9.25 / −0.12%)
NQ 30,845.25 (−44.00 / −0.14%)
Slightly soft start after the rejection headline. Friday's 10-year print near 5.23% (highest since 2007) remains the other overhang for Monday's cash open.
For Monday: Expect a headline-sensitive open. Index futures are not pricing panic, but Hormuz policy risk plus sticky yields can cap early strength until cash volume confirms.
Simply Macro Explanation
Washington said no to Iran's timed Hormuz reopen. Futures opened a touch lower, not in freefall. Monday's cash session will decide whether this is a quiet reopen or another yield-and-oil tug of war.
#SundayFutures #SimplyMacro #futures #ES #NQ #Hormuz #Iran #TreasuryYields
When you think about it, it’s a good time to lock in some gains. Maybe throw some trailing stops, but this market has surprised before and retail gets punished sometimes for lacking conviction.
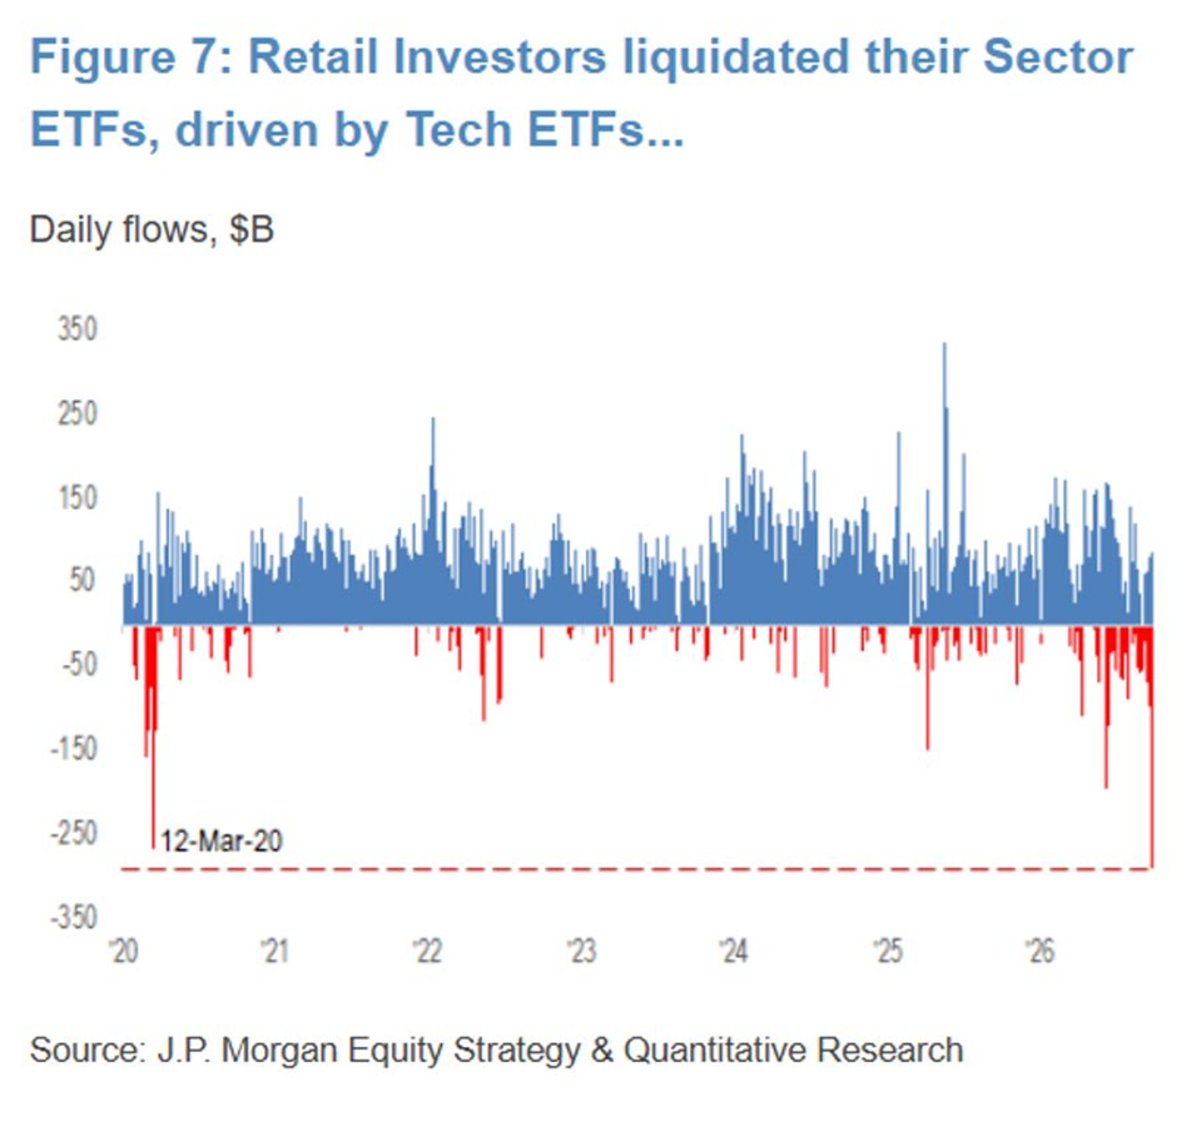
BREAKING: Retail investors sold -$300 million in ETFs on Wednesday, their largest daily sale on record.
This also surpasses the previous daily record of -$260 million set during the 2020 pandemic.
This comes as the semiconductor ETF, $SOXX, alone recorded -$270 million in retail outflows, its largest daily retail withdrawal in at least 12 months.
As a result, $SOXX posted -$695 million in total outflows last week, the largest weekly outflow since mid-August.
At the same time, investors withdrew -$1.2 billion from the 3x leveraged long semiconductor ETF, $SOXL, their largest weekly withdrawal since June.
Furthermore, the Momentum ETF, $MTUM, saw -$12 million in retail outflows on Wednesday, following -$30 million on Tuesday.
Retail investors are locking in gains in tech.
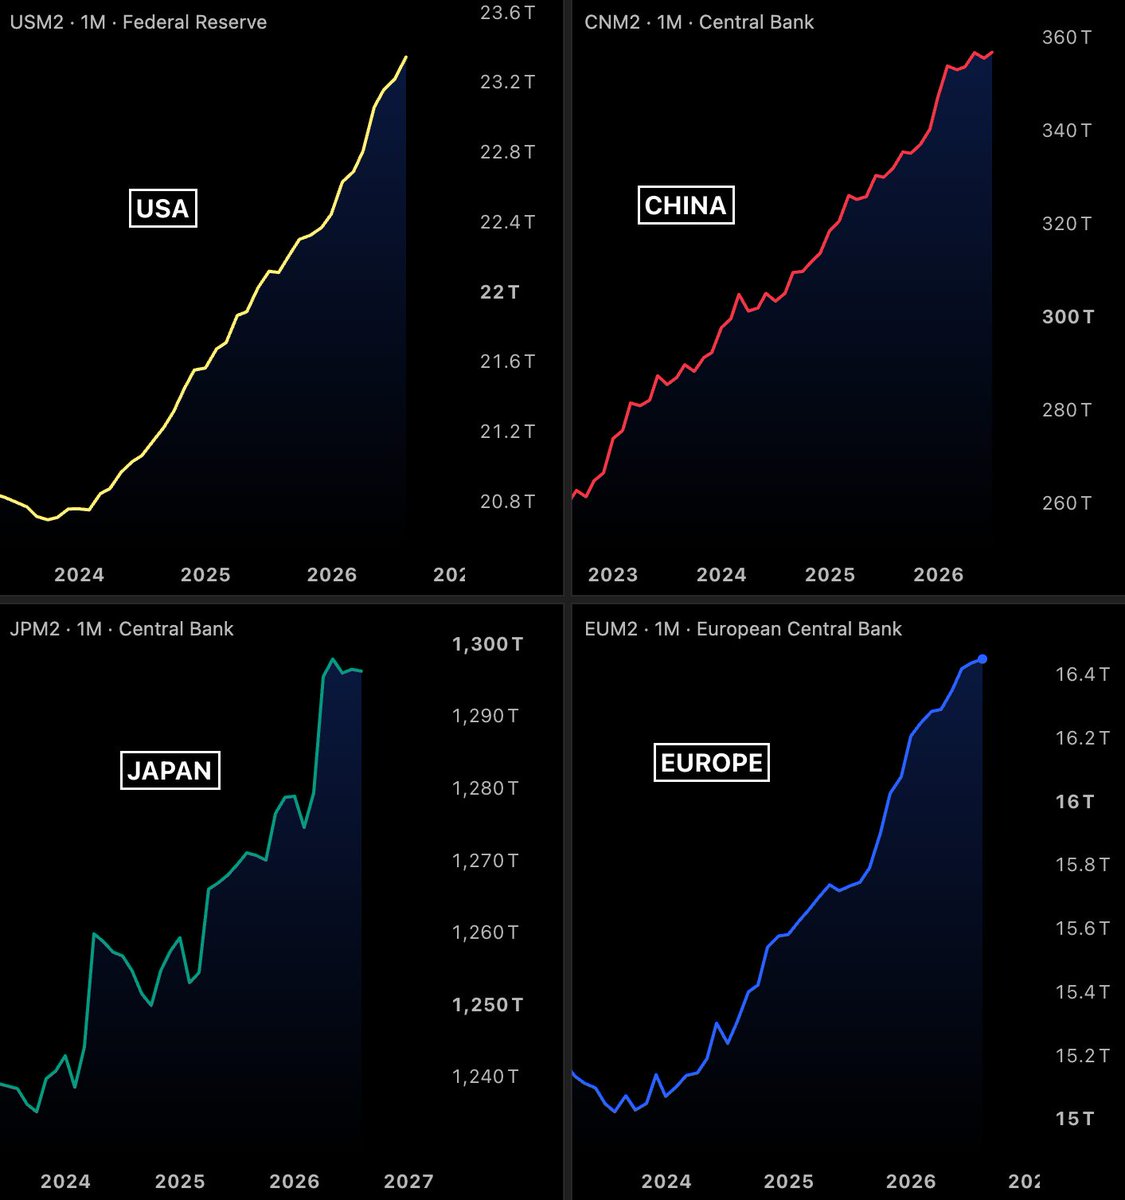
BREAKING: Global money supply just hit a new all time high of $103.66 TRILLION.
Fed, ECB, Bank of Japan, and PBOC alone added $1 trillion in August, the 10th straight monthly increase.
More money printed means more money flowing into assets like stocks, gold, and Bitcoin.
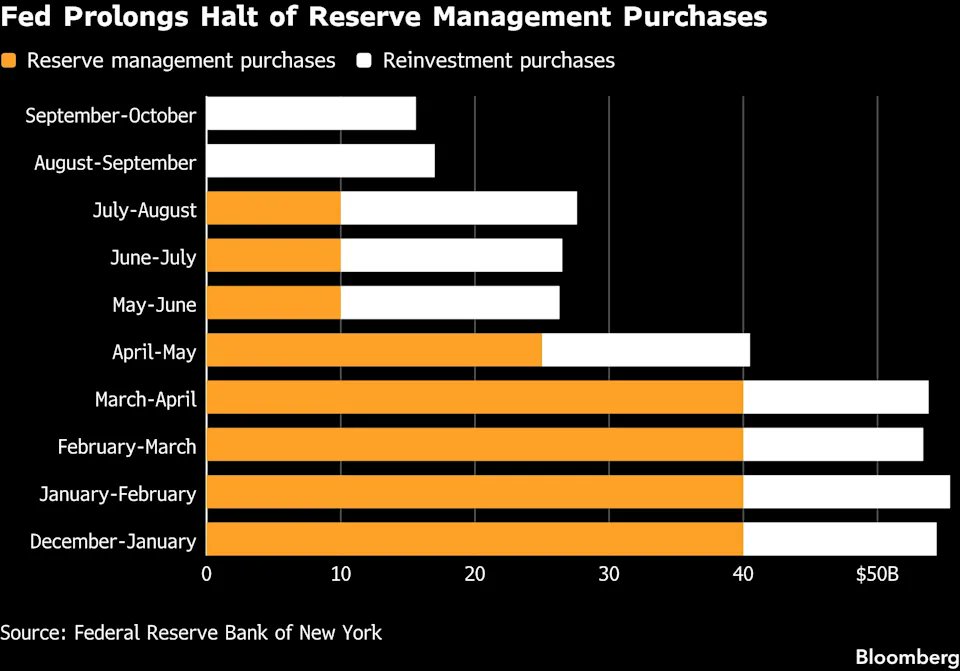
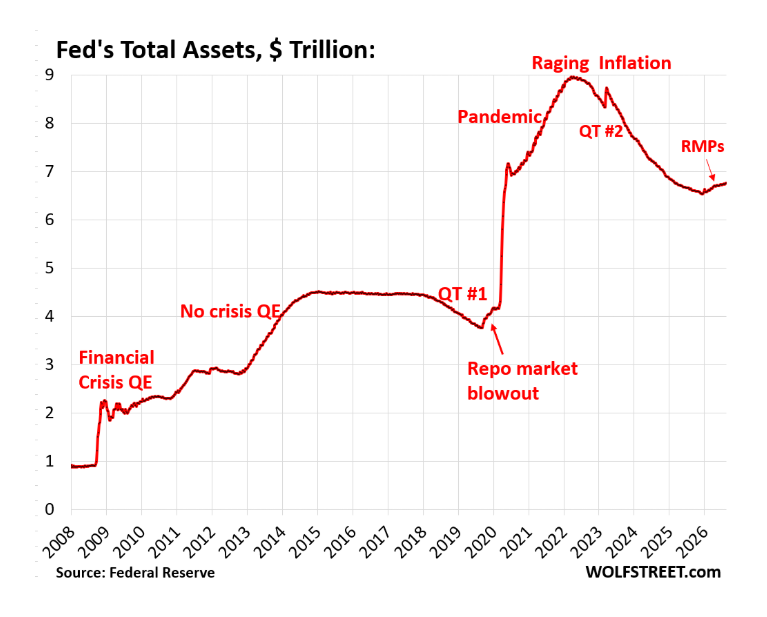
🚨 THE FED JUST CUT FRESH T-BILL BUYING TO ZERO.
For the second straight month, the Fed is doing $0 in fresh reserve-management purchases.
Earlier this year, it was buying around $40B a month.
Then $25B.
Then $10B.
Now zero.
The Fed says bank reserves are still high enough, so it does not need to add more liquidity right now.
But Treasury borrowing is still huge, and more short-term debt is expected to keep coming to the market.
The Fed is still buying about $15.6B through reinvestments, so it has not stopped all Treasury purchases.
The key point is that one source of fresh demand is gone for now.
If the Treasury keeps issuing more bills while fresh Fed buying stays at zero, private investors will have to absorb more of the supply.
If demand is not strong enough, yields will continue to rise, putting pressure on the US economy.
🇺🇸DATA: The Fed has paused its reserve-boosting Treasury bill purchases after buying about $215 BILLION since December.
It has scheduled about $15.6 BILLION in other bill purchases through October 14 to replace mortgage bonds rolling off its books.
Its balance sheet has grown $209 BILLION since December, compared with $4.8 TRILLION during Covid.
Some banks expect the paused purchases to restart in October, though the Fed has not announced a restart.
‼️THIS IS MIND-BLOWING:
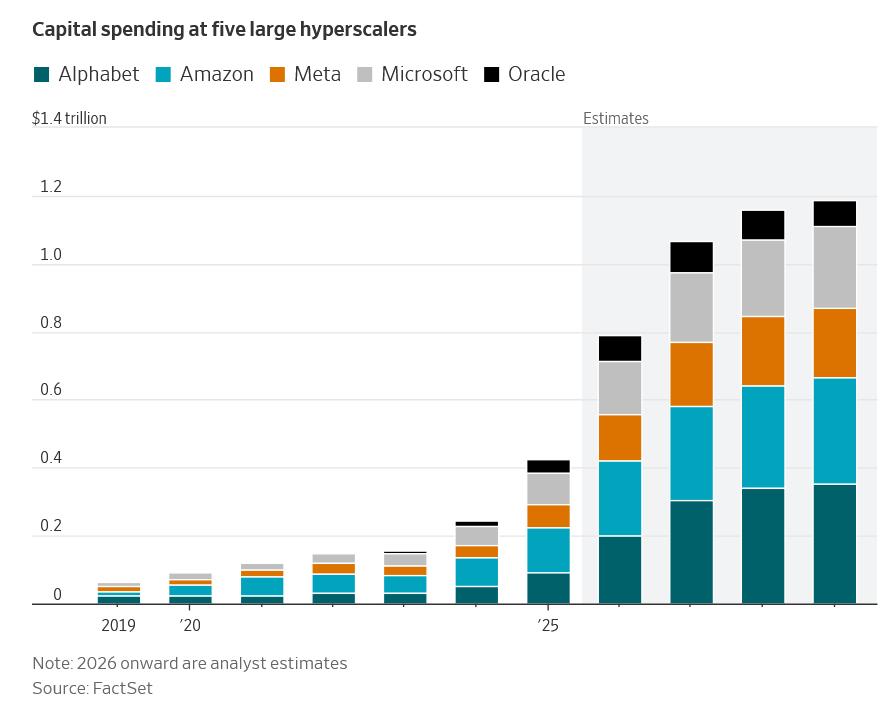
Wall Street analysts estimate that Alphabet, Amazon, Meta, Microsoft and Oracle will spend a combined $4.2 trillion on capital expenditures through 2029.
AI CapEx is expected to surpass $1 trillion for the first time in 2027.
At the same time, an increasingly large portion of that investment is being funded through debt.
What happens if the AI 'boom' suddenly reverses?