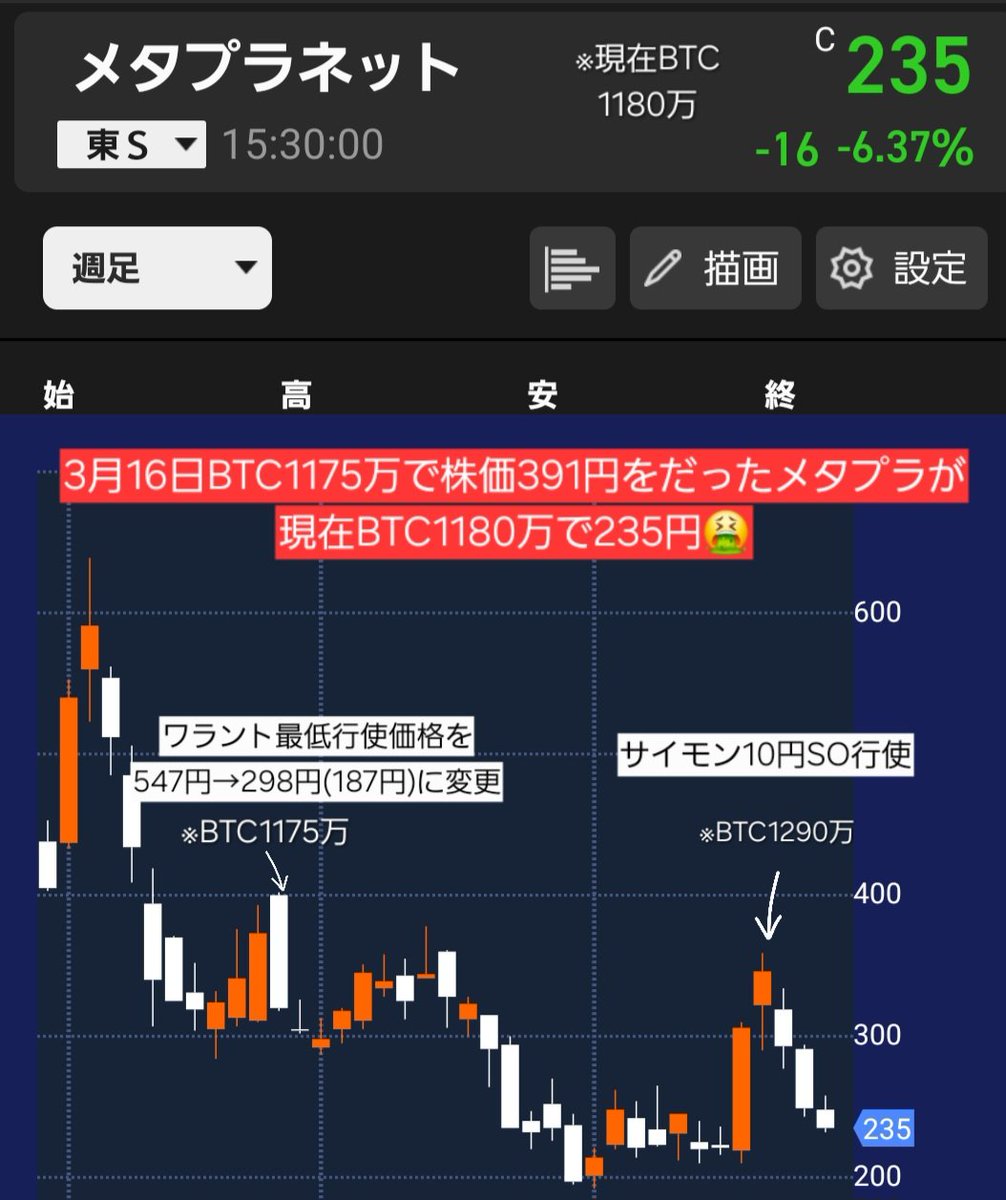
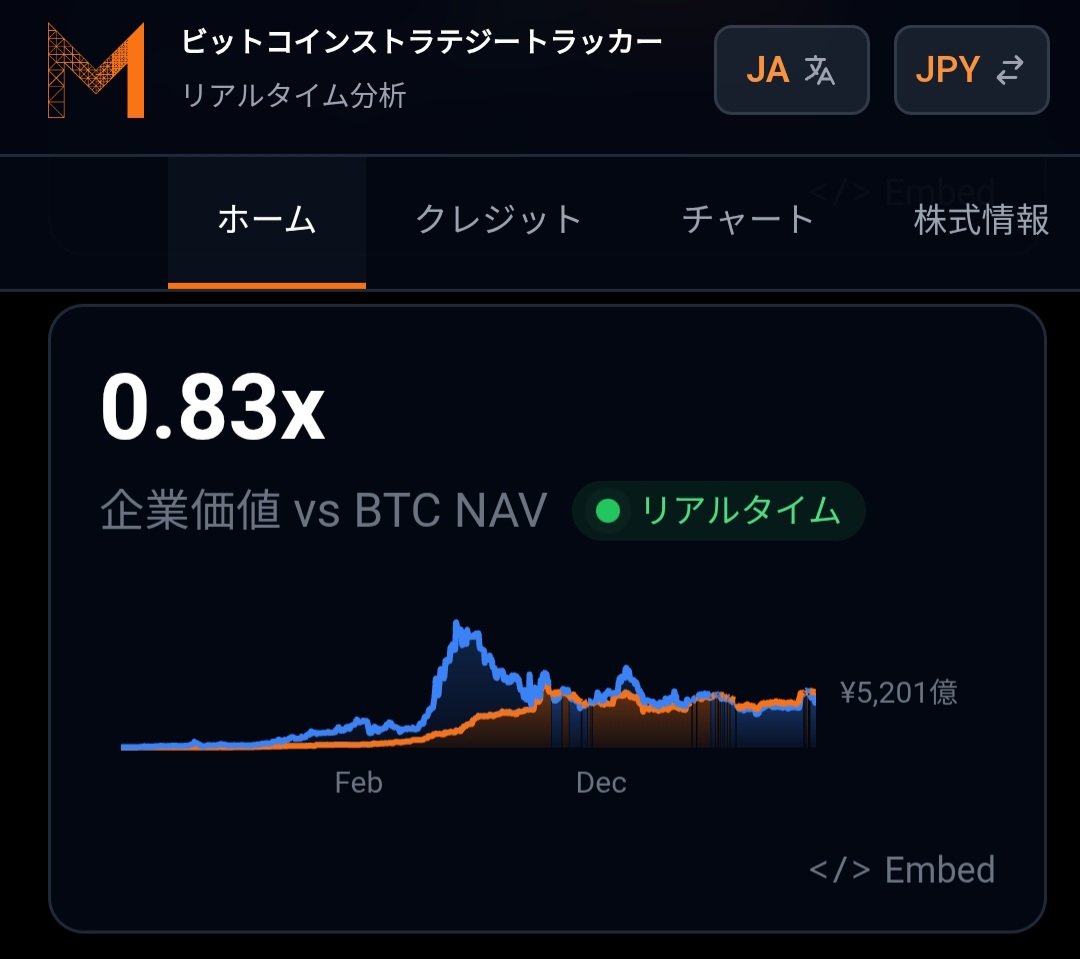
I know I said I was done posting about MetaPlanet, but if there is a useful point that I don't see being made, I will still share it. It is just no longer a crusade.
One of the less obvious things that retail investors have missed at @Metaplanet during this whole fiasco is that management was actually very bad at managing their treasury.
Like, there was no alpha generation. They generated negative alpha and then charged you 20% for it.
That's part of what makes David Bailey's 2 and 20 "hedge fund-like pay" ridiculous.
Their "Bitcoin income generation strategy" was essentially just put selling. And they were doing this heavily at all-time highs last year. This cost investors.
They raised billions in capital at the top, bought Bitcoin, and sold puts.
And now that bitcoin is about 50% off its highs, they have raised much less capital and bought much less bitcoin. And in Q2, they shouldn't even have bought bitcoin; they should have bought their own shares at a discount. That would have increased BTC per share more, but obviously would not have benefited management as much.
Anyways, at any pod shop, hedge fund, or any serious financial institution, the "Head of Bitcoin Strategy" would be shown the door after that performance.
@EspritAlberta@orangeyield@LawrenceLepard@JoshMandell6
Metaplanet update.
This is a post I would rather not make but as someone who has covered the stock extensively, I feel it is my duty to.
It gets into the weeds of the 10th Series Stock Acquisition Rights, which saw 46 million shares become 319.4 million, because the pool was defined as a permanent 20% of fully diluted shares rather than a fixed count.
A brief timeline of events:
28 Dec 2022. Board resolves the package that creates the 10th Series, alongside a third-party allotment, the 9th Series, and the rename to Metaplanet. The company is distressed, going concern flagged, stock around ¥30.
8 Feb 2023. 460,000 units issued: 336,000 to directors, 124,000 to employees. Strike ¥10. Underlying shares defined not as a fixed number but as fully diluted shares × 0.2.
Apr 2024. Bitcoin treasury strategy announced. Roughly 154m shares outstanding. Every share issued from here expands the pool to keep it at 20%.
18 Aug 2026. Pool frozen at 319,464,000 shares, or 696 per unit, roughly 20% of the company. Lock-up added to 2031. The company concedes the clause went beyond ordinary technical adjustment and made dilution hard for shareholders to grasp.
28 Aug 2026. Gerovich exercises 92,000 units into 64,032,000 shares for about ¥640m ($4m). Stock closes ¥346, valuing them at roughly $138m.
You can see the problem here.
The misalignment was there from the very beginning, sitting in legacy warrants that existed long before the Bitcoin treasury model was adopted.
Dilution events like the controversial international offering benefited the 10th Series holders 7.5x more than they benefited ordinary shareholders. I will link the post explaining this below (not to be confused with the quoted post, which I will come to).
While these shares were accounted for in BTC/share and other metrics, the clause itself was never made widely available in English. It was published years ago, in Japanese.
Could we have done better due diligence? Perhaps. But you hardly expect something like this to exist years before the treasury model began. It is an obscure and unusual thing to attach to warrants, and it is not what anyone was looking for. As soon as something looked off with the international offering, I raised it.
The company has said that, without shareholder feedback, it saw no need to fix the clause until a few weeks ago.
That is not the full picture. In the quoted post you can see I asked the question directly and tagged both Simon and Dylan. Ragnar raised the same issue two weeks earlier, as did several others. We were all ignored.
And the company now agrees the clause was not appropriate. If there were no problem with it, why fix it at all?
In my view $600 million of value is not a defensible outcome. That is 17.75% of the $3.38 billion Bitcoin NAV on the balance sheet, and 25% of the entire $2.4 billion market cap.
A quarter of the company.
At last year's highs the same holding was worth more than $1.5 billion, and on the current share count it would be closer to $3 billion.
For scale, Nvidia's CEO earned $49m in 2025 and is set to be paid $37m in 2026, at the largest company in the world. These figures include equity.
The right thing to do would be to cancel the expanded portion entirely, let management keep the original 46 million shares, worth roughly $90m at today's price, and then apply an employee incentive scheme that is fairer to shareholders from here.
I wanted to keep this strictly to the 10th Series, but there is also MMXX Ventures Limited, a BVI-incorporated investment vehicle tied to Simon with a history of buying and selling Metaplanet stock that deserves scrutiny. It would be nice to get some clarity on this.
I have spoken with the team directly alongside Ragnar to discuss this issue but unfortunately we do not see eye to eye on this.
I didn't want to take part in shareholder activism but this is important. We all bought Bitcoin to escape the Cantillon effect after all.
I hope this can be resolved.
I wrote an article about what really happened at Metaplanet, in plain English, and why so many of the influencers are quiet about it. https://t.co/whOJQuhQqF
I wrote an article about what really happened at Metaplanet, in plain English, and why so many of the influencers are quiet about it. https://t.co/whOJQuhQqF