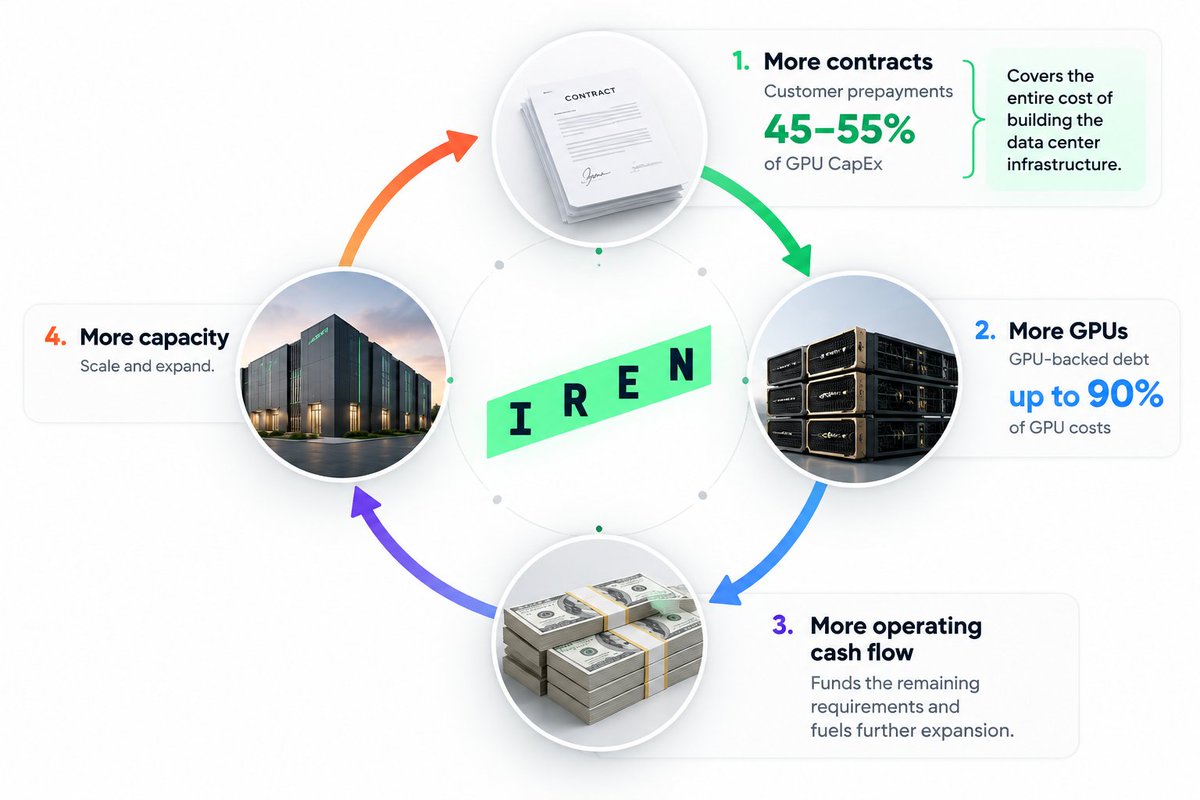
$IREN financing flywheel is taking shape, and it’s validating the entire investment thesis.
CEO Daniel Roberts recently made it clear: demand for AI compute is so enormous that $IREN has enough customer interest to sell its available capacity multiple times over.
Contract prices are rising month after month, and customer prepayments are increasing alongside them.
And the economics were already extremely attractive before these latest pricing increases.
Back in Q2 2026, $IREN’s financing structure looked like this:
• Customer prepayments: Cover 45–55% of GPU CapEx, roughly equivalent to the entire cost of constructing the physical data centers.
• GPU-backed debt: Finances up to 90% of GPU acquisition costs.
• Operating cash flow: Combined with additional infrastructure financing, provides the capital to accelerate further expansion.
Now look at the flywheel:
More contracts → More prepayments → More GPUs deployed → More operating cash flow → More capacity → More contracts.
Growth fuels more growth.
Higher contract prices increase revenue per MW. Larger customer prepayments reduce upfront capital requirements. Growing operating cash flow helps finance the next wave of expansion.
Every new contract strengthens $IREN’s ability to finance the next one.
Today’s $363M financing, backed by already deployed and revenue-generating GPU infrastructure, is another concrete validation of this strategy.
As this flywheel accelerates, $IREN expands its compute capacity, reinvests its cash flows, and progressively reduces its dependence on shareholder dilution.
The larger $IREN becomes, the more growth it can finance without issuing new shares.
$IREN is transforming a capital-intensive AI infrastructure business into a self-funding growth machine.
And the flywheel is only getting started.