Humanities and social science depts at universities are breeding grounds for ideological indoctrination and the recruitment of leftists, wokists and jihadists, with some being mobilized by foreign-funded NGOs to foment sociopolitical unrest in the pursuit of regime change.
Shut them down.
Learn from China. Put resources in STEM education for innovation and development
Without proving Intention to Evade, the Tax Department cannot levy a Penalty merely based on a mistake in entering the vehicle number!!
Please save/bookmark this post for future use.
I am sharing a few High Court judgments that could help you in case of human error.
1. Uttam Electric Store - Allahabad High Court
(2024) 21 CENTAX 189
Assessee supplied goods to a purchaser of Chandpur, UP which was consigned to ‘Udit Engineers, Aligarh’ - In e-way bill, place of delivery was mentioned as ‘Chandpur (UP)’
There being human error while filling up e-way bill and no finding being recorded by any authority below that there was mens rea essential for levying penalty under Section 129(3) of CGST Act, impugned penalty orders were to be set aside.
2. Luminous Power Technologies Pvt. Ltd. - Allahabad High Court
(2024) 18 CENTAX 209
Truck No. UP-11T/2175 was mistakenly mentioned as UP-14BT/3276.
Where petitioner-assessee had no intention to evade any tax, therefore, minor discrepancy as to registration of vehicle in State on e-way bill would not attract proceedings for penalty under Section 129; Detention order and appellate order were to be set aside.
3. BMR Enterprises - Allahabad High Court
(2024) 19 CENTAX 57
Vehicle No. UP 83 CT 2724 was entered as UP 80 CT 7024.
Where goods were detained and penalty was levied for minor discrepancies in vehicle registration details in e-way bill, High Court set aside penalty order, holding it to be case of unintentional mistake not attracting penalty.
4. Deco Plywood Industries - Allahabad High Court
(2024) 19 CENTAX 297
Vehicle No. HR 58B 9542 was entered as DL1 AA 5332.
Where assessee/petitioner-dealer argued that penalty was wrongly imposed for minor e-way bill error without tax evasion intent, High Court quashed orders, ruling that Section 129 penalties cannot apply to minor, non-evasive errors.
5. Hindustan Herbal Cosmetics - Allahabad High Court
(2024) 82 GSTL 409
Vehicle No. DL1 AA 5332 was entered as DL1 AA 3552.
For minor typographical error of vehicle number in e-way bill, penalty is not impossible
6. Varun Beverages Ltd. - Allahabad High Court
(2023) 71 GSTL 4
Vehicle No. HR-73/6755 was entered as UP-13T/6755.
A minor discrepancy in the description of the vehicle in the e-way bill could not attract proceedings for detention of goods and levy of penalty where the dealer had no intention of evading tax.
I hope you will find this post useful.
.
Thanks
Abhishek Raja Ram
9810638155
It seems there is no unity among CA on X.
Hardly anyone has tweeted with the tag #ExtendTaxAuditdate
Unless we unite, we won't see change.
Post why you want an extension and use the tag #ExtendTaxAuditdate
I can help raise your voice, but you also need to put in some effort by tweeting if you want an extension.
Tax Audit Extension — एक और पहलू
एक सवाल बार-बार आता है—क्या Tax Audit की due date बढ़ाने की मांग व्यापारियों की समस्या है या Tax Professionals की?
हर व्यापारी का सामान्यतः एक ही Tax Audit होता है। यदि वे अपना data कुछ दिन देर से भी देते हैं तो उनके एक ऑडिट को पूरा करने का समय उनके अनुसार फिर भी उपलब्ध हो सकता है।कोई भी कह सकता है कि क्या एक ऑडिट के लिए 10 दिन का समय काफ़ी नहीं है !!!
लेकिन Tax Auditors के सामने समस्या अलग है। हमें एक साथ एक से ज़्यादा संख्या में Audits पूरे करने होते हैं और हमारा मुद्दा यही है कि जिस काम के लिए पहले लगभग 60 दिन का practical window मिलता था, वह अब प्रभावी रूप से करीब 30 दिन रह गया है।
इसलिए एक महीने के extension की मांग मुख्यतः Tax Professionals के लिए पर्याप्त working time की मांग है।
हम अतिरिक्त सुविधा नहीं, पर्याप्त समय मांग रहे हैं।
- सुधीर हालाखंडी
#extendtardate
The same Congress that back in March and August flagged the zero-MDR UPI model as financially unsustainable and demanded a calibrated and tiered MDR on high-value transactions, is today opposing it.
Here, I expose these hypocrites and separate fact from fiction on the UPI issue:
MOODY'S ENDORSES INDIA'S GROWTH STORY. RAISES GDP FORECAST BY A FULL 1%!
Moody’s has raised its forecast for India’s real GDP growth to 7% for the current fiscal year, up from its earlier estimate of 6%, citing the economy’s resilience amid the ongoing West Asia conflict. Although we continue to expect India to grow faster than all other G-20 economies, as well as similarly rated emerging market sovereigns, risks remain."
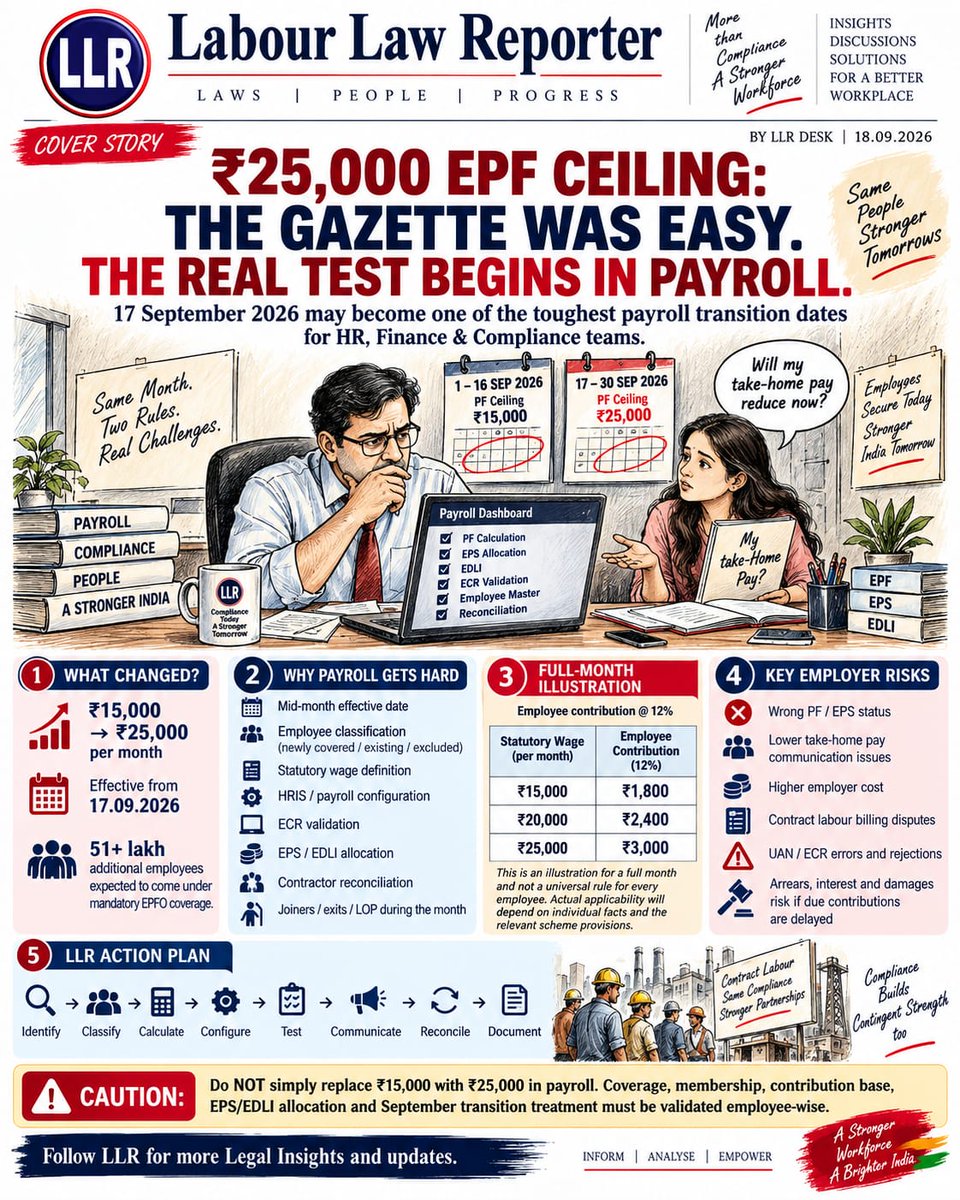
🚨 𝐓𝐇𝐄 𝐆𝐀𝐙𝐄𝐓𝐓𝐄 𝐂𝐇𝐀𝐍𝐆𝐄𝐃 𝐎𝐍𝐄 𝐍𝐔𝐌𝐁𝐄𝐑. 𝐏𝐀𝐘𝐑𝐎𝐋𝐋 𝐍𝐎𝐖 𝐇𝐀𝐒 𝐓𝐎 𝐂𝐇𝐀𝐍𝐆𝐄 𝐄𝐕𝐄𝐑𝐘𝐓𝐇𝐈𝐍𝐆 𝐀𝐑𝐎𝐔𝐍𝐃 𝐈𝐓.
₹15,000 ➝ ₹25,000.
Looks simple? It isn’t.
From 17 September 2026, ₹25,000 per month is the notified EPF wage ceiling. Around 51 lakh additional employees are expected to come within mandatory EPF coverage.
But between the Gazette and the payslip lies the real compliance test:
𝐖𝐚𝐠𝐞𝐬 ➝ 𝐌𝐞𝐦𝐛𝐞𝐫𝐬𝐡𝐢𝐩 ➝ 𝐄𝐏𝐅 ➝ 𝐄𝐏𝐒 ➝ 𝐄𝐃𝐋𝐈 ➝ 𝐄𝐂𝐑 ➝ 𝐏𝐚𝐲𝐫𝐨𝐥𝐥 ➝ 𝐀𝐮𝐝𝐢𝐭.
➤ ❶ 𝐌𝐈𝐃-𝐌𝐎𝐍𝐓𝐇 𝐌𝐀𝐙𝐄
The notification is effective from 17.09.2026, but it does not itself prescribe a day-wise September formula saying “₹15,000 up to 16th and ₹25,000 from 17th”.
So employers should not invent a proration method and treat it as settled law.
➤ ❷ ₹𝟐𝟓,𝟎𝟎𝟎 𝐈𝐒 𝐀 𝐖𝐀𝐆𝐄 𝐂𝐄𝐈𝐋𝐈𝐍𝐆 — 𝐍𝐎𝐓 𝐀 𝐁𝐋𝐀𝐍𝐊𝐄𝐓 ₹𝟑,𝟎𝟎𝟎 𝐃𝐄𝐃𝐔𝐂𝐓𝐈𝐎𝐍
Membership, statutory “wages” and contribution base must be tested employee-wise.
Full-month illustration:
₹15,000 × 12% = ₹1,800
₹20,000 × 12% = ₹2,400
₹25,000 × 12% = ₹3,000
Maximum incremental impact over the old ceiling: ₹1,200 per month on each 12% contribution side, where applicable.
➤ ❸ 𝐏𝐑𝐄𝐕𝐈𝐎𝐔𝐒𝐋𝐘 𝐄𝐗𝐂𝐋𝐔𝐃𝐄𝐃 𝐄𝐌𝐏𝐋𝐎𝐘𝐄𝐄𝐒 𝐍𝐄𝐄𝐃 𝐑𝐄𝐕𝐈𝐄𝐖
Employees earlier outside mandatory membership solely because wages exceeded ₹15,000 may now require fresh classification.
Do not create UANs blindly. Check prior membership, wage status and EPS history first.
➤ ❹ 𝐒𝐀𝐋𝐀𝐑𝐘 > ₹𝟐𝟓,𝟎𝟎𝟎 ≠ 𝐍𝐎 𝐏𝐅
An existing member does not automatically stop being a member merely because wages later cross ₹25,000.
➤ ❺ 𝐃𝐎𝐍’𝐓 𝐂𝐇𝐄𝐂𝐊 𝐎𝐍𝐋𝐘 𝐁𝐀𝐒𝐈𝐂 + 𝐃𝐀
The Code’s statutory definition of “wages”, including the 50% framework, can change the number that must be tested against the ceiling.
➤ ❻ 𝐄𝐏𝐒 & 𝐄𝐃𝐋𝐈 𝐍𝐄𝐄𝐃 𝐒𝐄𝐏𝐀𝐑𝐀𝐓𝐄 𝐀𝐓𝐓𝐄𝐍𝐓𝐈𝐎𝐍
Even where PF was already being paid on actual wages, employer-side EPF/EPS allocation can still matter.
And employers should not communicate that EDLI maximum benefit has automatically become ₹10.5 lakh unless the statutory cap itself is amended.
➤ ❼ 𝐄𝐂𝐑 𝐌𝐀𝐘 𝐁𝐄 𝐓𝐇𝐄 𝐑𝐄𝐀𝐋 𝐁𝐎𝐓𝐓𝐋𝐄𝐍𝐄𝐂𝐊
Wrong EPS flags, UAN mismatches and incorrect wage logic can trigger system validations. EPFO’s revamped ECR specifically includes checks for wages, UAN and pension eligibility.
➤ ❽ 𝐂𝐎𝐍𝐓𝐑𝐀𝐂𝐓 𝐋𝐀𝐁𝐎𝐔𝐑 𝐂𝐀𝐍 𝐃𝐎𝐔𝐁𝐋𝐄 𝐓𝐇𝐄 𝐂𝐎𝐌𝐏𝐋𝐈𝐀𝐍𝐂𝐄 𝐑𝐈𝐒𝐊
Principal employers should reconcile contractor wages, UANs, ECRs, challans and revised commercial costs employee-wise.
The safest playbook:
𝐈𝐝𝐞𝐧𝐭𝐢𝐟𝐲 ➝ 𝐂𝐥𝐚𝐬𝐬𝐢𝐟𝐲 ➝ 𝐂𝐚𝐥𝐜𝐮𝐥𝐚𝐭𝐞 ➝ 𝐂𝐨𝐧𝐟𝐢𝐠𝐮𝐫𝐞 ➝ 𝐓𝐞𝐬𝐭 ➝ 𝐂𝐨𝐦𝐦𝐮𝐧𝐢𝐜𝐚𝐭𝐞 ➝ 𝐑𝐞𝐜𝐨𝐧𝐜𝐢𝐥𝐞 ➝ 𝐃𝐨𝐜𝐮𝐦𝐞𝐧𝐭.
The dangerous shortcut?
₹15,000 ➝ ₹25,000 in the payroll master — and nothing else.
Idiots from Congress cabal who are howling about that 0.4% MDR..well, switch to Rupay Debit Cards..Rupay rides on #UPI &comes under Zero-MDR network
Modi Govt is promoting homegrown #Rupay &not giving in to any kind of pressure from US as is being falsely alleged by Rahul Gandhi
The Indian Semiconductor Matrix is evolving!
As we step into the era of Semicon 2.0 - backed by the Cabinet’s ₹1.27 Lakh Crore outlay - India’s transition from potential to pure execution is real.
From active OSATs to massive Fabs under construction, here is the chip map today.
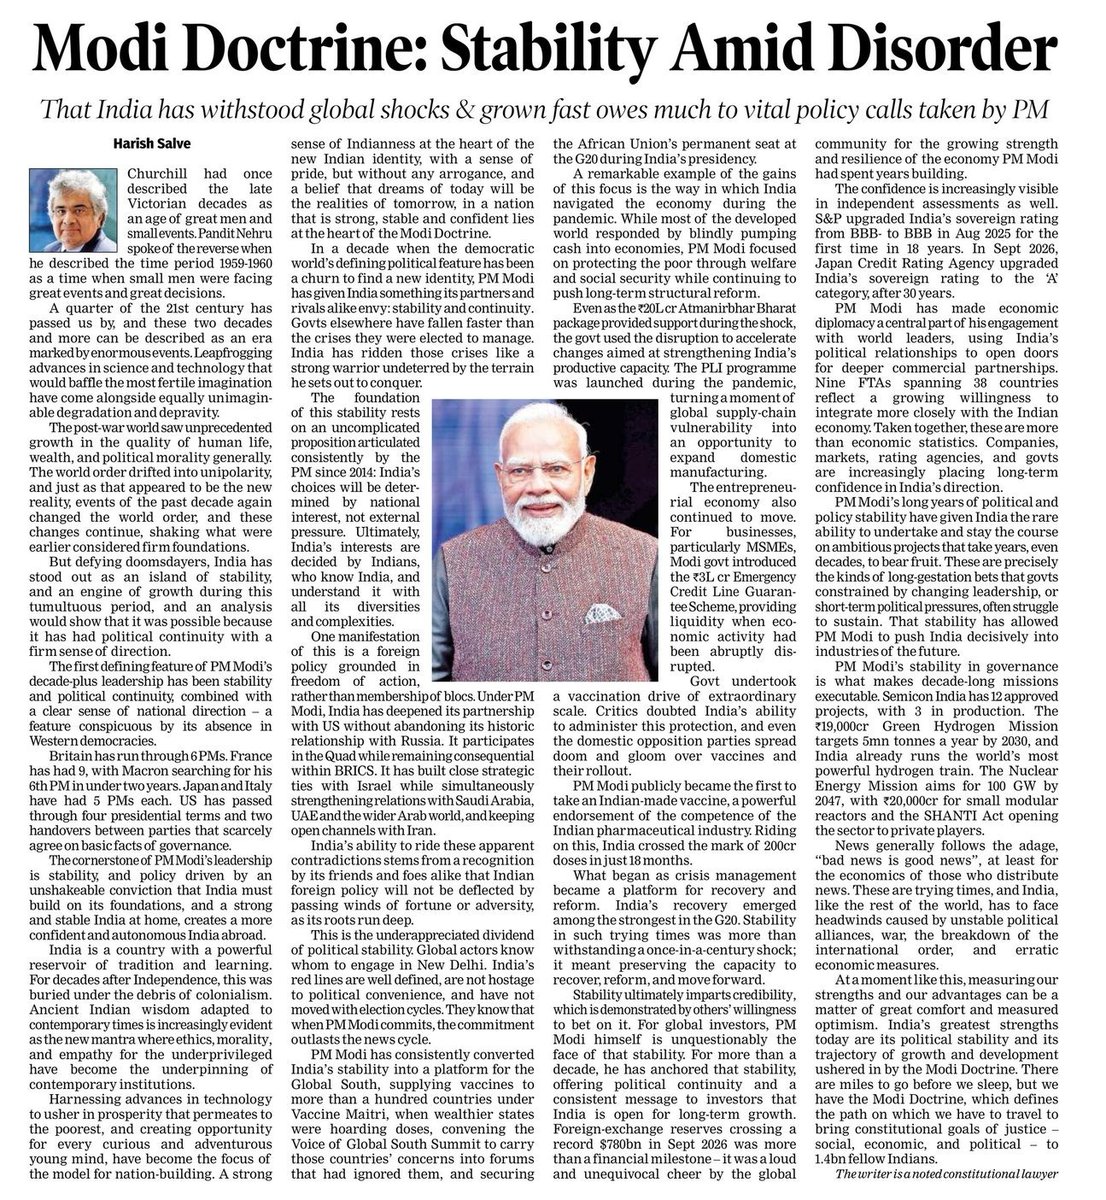
India has stood out as an island of stability and an engine of growth during a tumultuous period, Shri Harish Salve writes.
He attributes this to PM @narendramodi's stable leadership and political continuity, saying a clear sense of national direction has strengthened India's economy, foreign policy and long-term nation-building.
https://t.co/oFxmwG345h
Retweet For Support and Reach
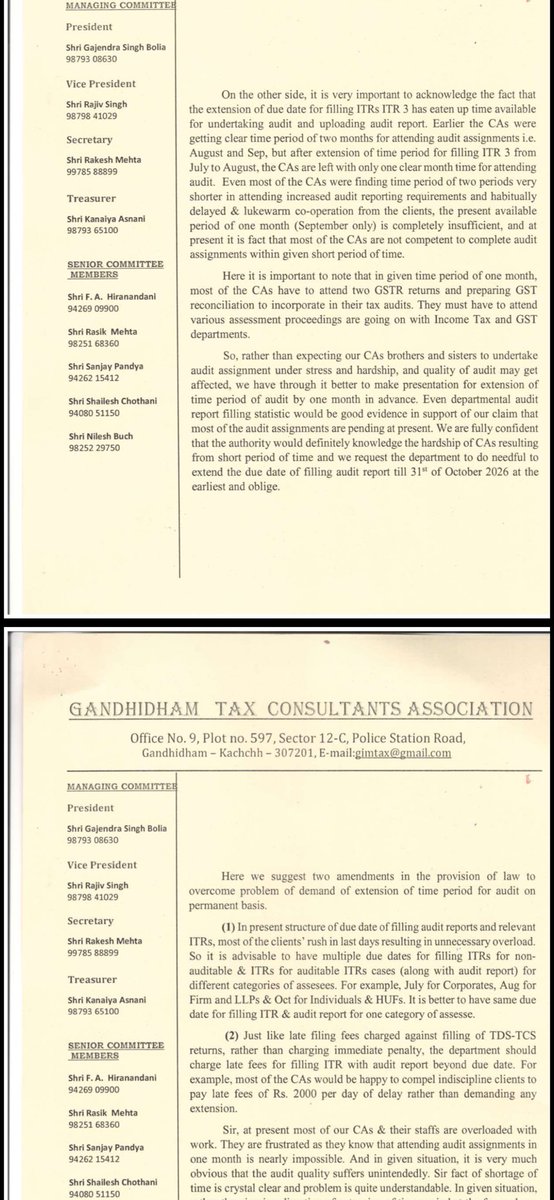
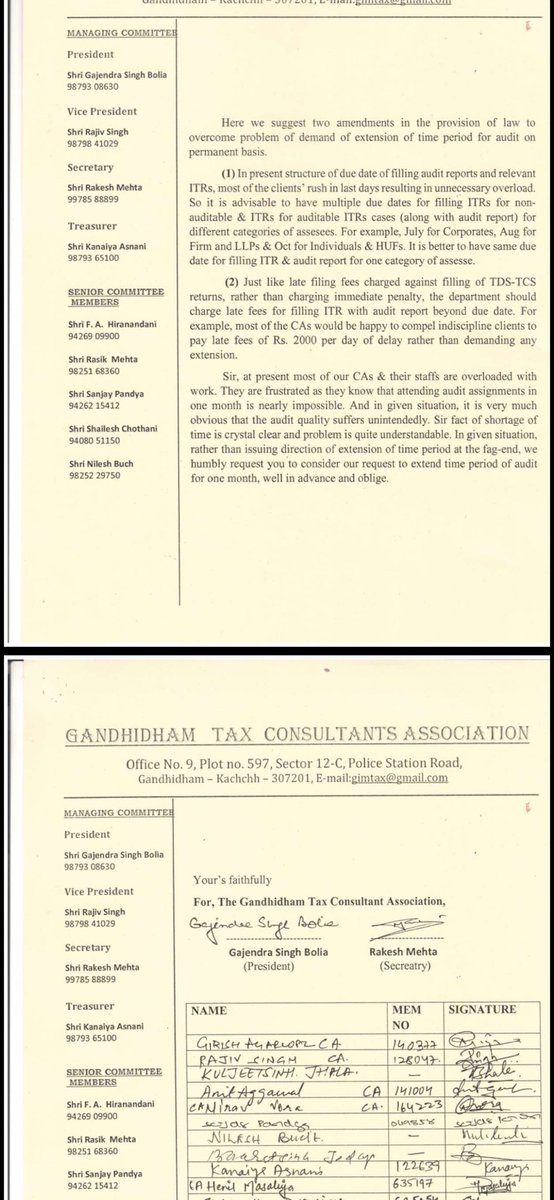
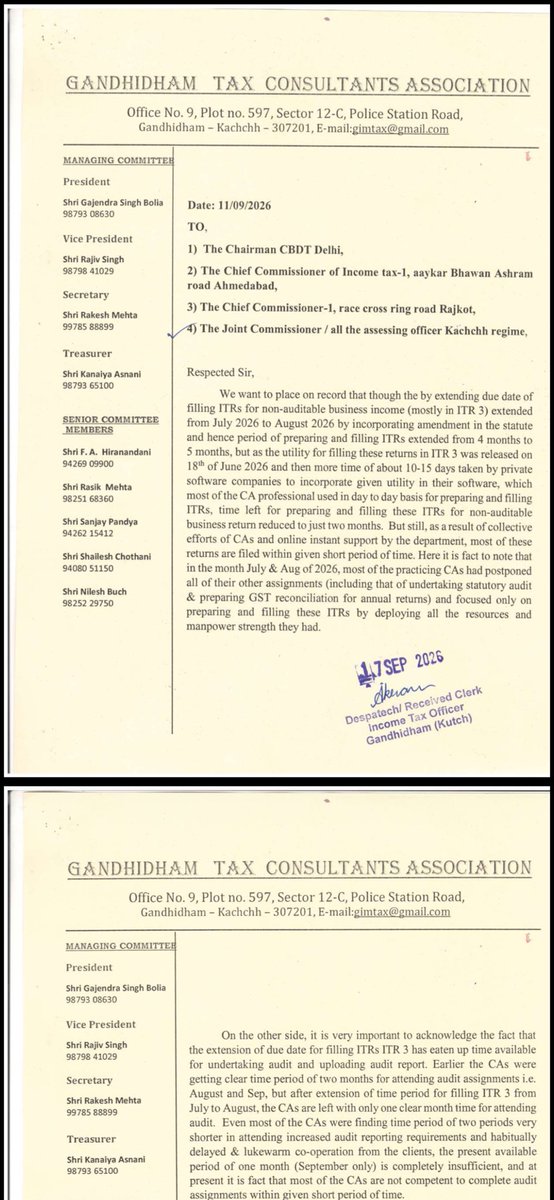
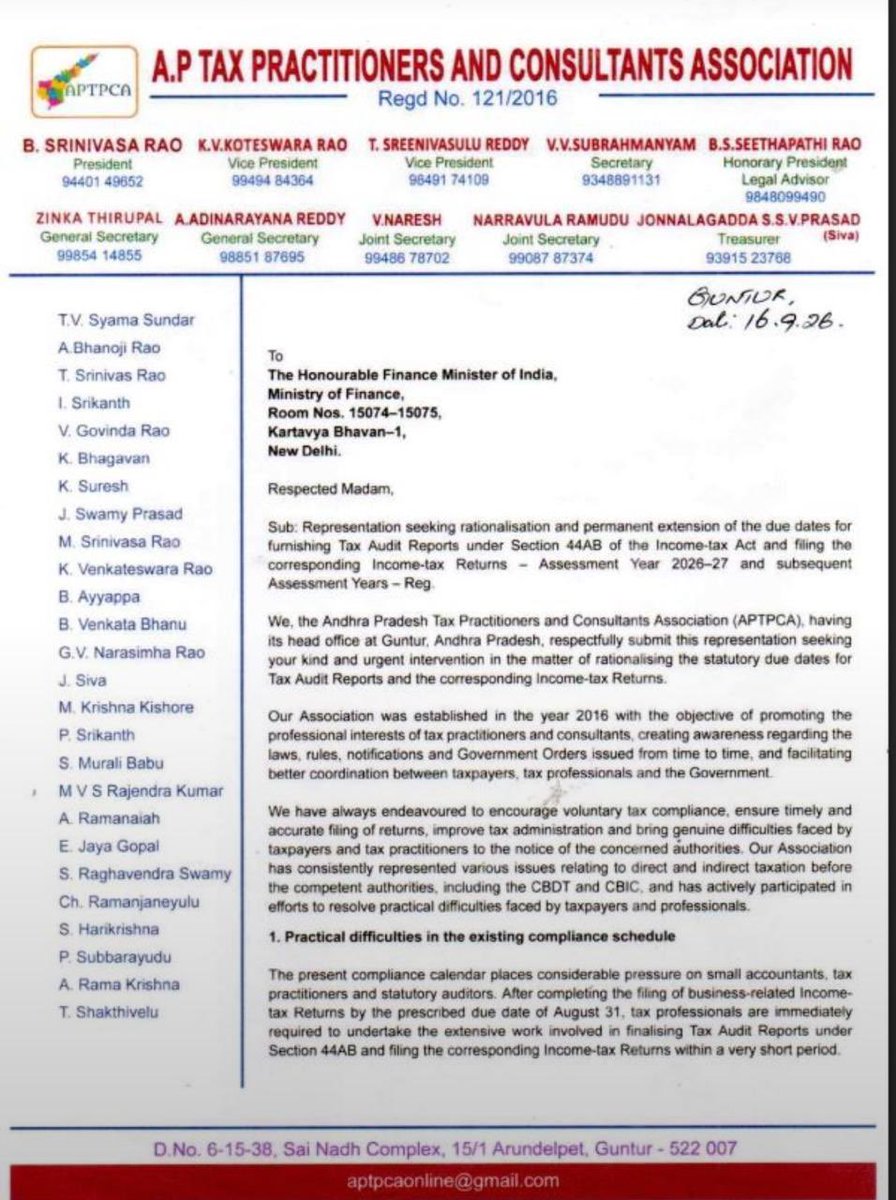
Gandhirham Tax Consultants Association Represent @IncomeTaxIndia For Tax Audit Due Date Extension upto 31st Oct, 2026
Ram Bajaj
8696424223
For Regular GST Updates, Join this Group
https://t.co/SmMxCrTcJG
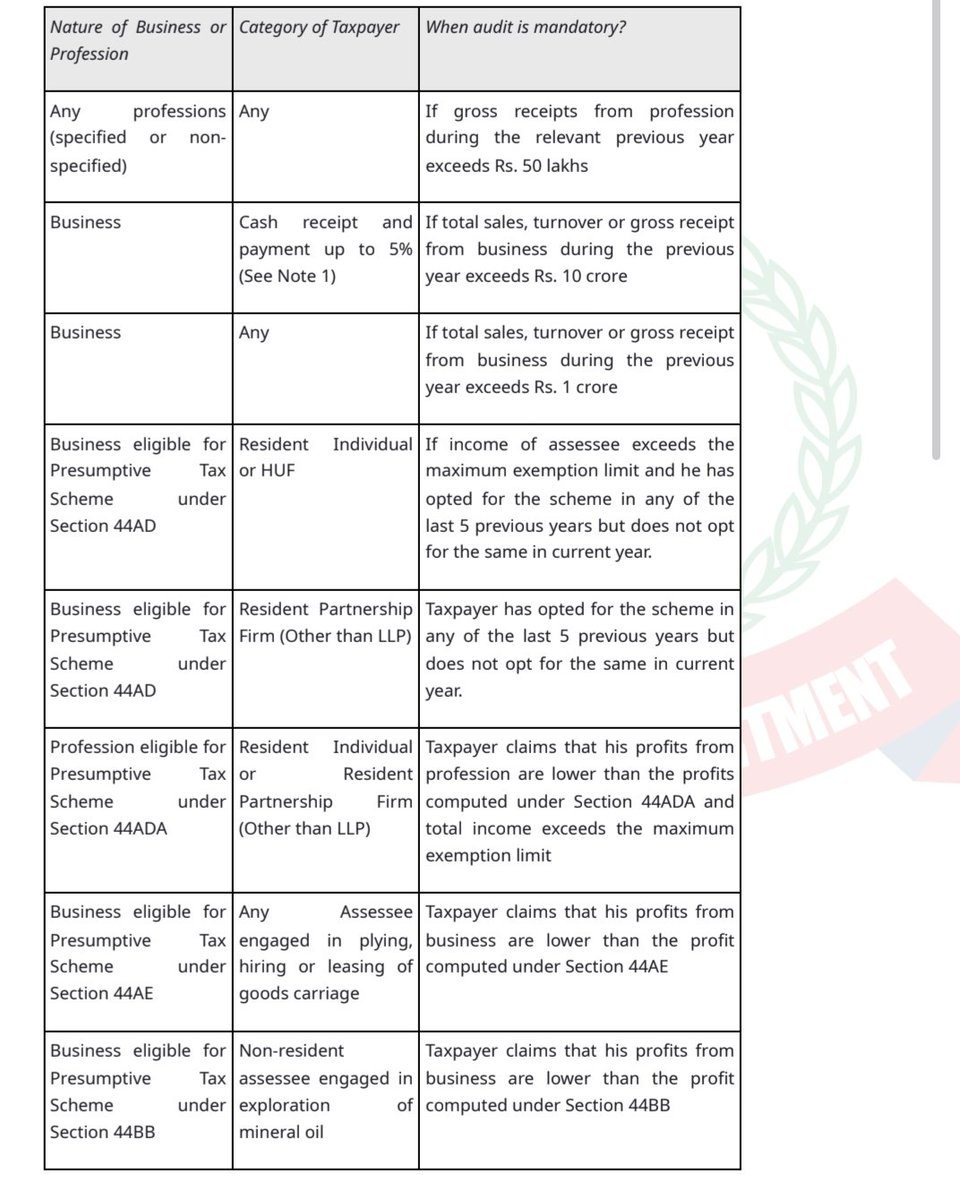
📢 Tax Audit Due Date Extension Request
The Haryana State Tax Bar Association has represented before the Hon’ble Finance Minister, CBDT Chairman and Members, seeking a reasonable extension of the Tax Audit Report due date for AY 2026-27 beyond 30 September 2026.
A timely decision would provide much-needed relief to tax professionals and taxpayers while ensuring quality compliance.
Follow the Tax Talk with CA Nitin Chawla A.C.C.A channel on WhatsApp: 👇 https://t.co/7KtKmuv6rW
#TaxAudit #TaxAuditDueDate #IncomeTax #CA #TaxProfessionals
Retweet For Support and Reach
Tax Audit due date should be PERMANENTLY extended to 31st October.
Every year, tax professionals face the same challenge -
🤯 Heavy compliance workload, unrealistic timelines and
⏰ repeated demands for due date extensions.
The issue is not extensions; the issue is compliance overload and inadequate time for quality work.
@IncomeTaxIndia
#TaxProfessionals #TaxReform #ComplianceBurden #IncomeTax #GST #SME
#Extend_Due_Date
Ram Bajaj
8696424223
For Regular GST Updates, Join this Group
https://t.co/TomhZ4lnQH
Your UPI Payments Stay Free!
UPI continues to stay free for person-to-person transfers and everyday users, while small merchants remain protected.
Under the updated MDR framework, 96% of merchant UPI transactions remain unaffected, with MDR limited to certain larger merchant payments not charged to customers.
So, the next time you hear “UPI isn’t free anymore,” remember the facts that everyday UPI payments remain simple, seamless and free for users.
#UPI
The new UPI framework introduced has no impact on any person to person transactions.
UPI will continue to remain completely free for all person-to-person transactions, irrespective of the amount transferred.
Payments to merchants up to ₹2,000, along with transactions covered under the zero-MDR framework for small merchants, will also remain free. Consequently, approximately 96% of all P2M (person-to-merchant) transactions will remain unaffected. MDR will apply only to specified merchant transactions above ₹2,000.
Read More - https://t.co/w1m0HCY00C
Tax Bar Association, Bhilwara seeks extension of Tax Audit Reports (3CA/3CB & 3CD) and Forms 10B/10BB for AY 2026-27 from 30 Sept to 31 Oct 2026, citing late ITR utilities, revised ICAI requirements and compressed audit timelines. https://t.co/7NHw4sVGVu
📢 #ICAI Member Benefit Alert
Free Class 3 Individual Signing DSC – 2-Year Validity
The Beneficiary Schemes Directorate of ICAI is offering a Class 3 Individual Signing Digital Signature Certificate (DSC) with 2-year validity, completely FREE of cost, through IDSign for eligible ICAI Registered Practicing Professional Members.
🔹 Prerequisites & Key Details 💼
• Eligibility: Practicing CA
• Certificate: Class 3 Individual Signing DSC
• Validity: 2 Years
Apply Online at https://t.co/9b4zy81n92
Enter your ICAI Membership/Registration Number in the Remarks Field to facilitate ICAI approval.
Video Verification: Review your details, complete the video verification process, upload the required video and note the Reference Number.
🔹 Support & Assistance ☎️
IDSign Support: 1800-572-1734
Email: [email protected]
For further details:
📞 8031290969
🌐 https://t.co/lZ4c4wUpRS
Beneficiary Schemes Directorate, ICAI:
📞 0120-3045994
📧 [email protected]
Regards,
CA Akhil Pachori