Resolving the Fannie Mae & Freddie Mac ($FNMA / $FMCC) conservatorship isn't just about housing finance - it's a test of contract integrity and government credibility in U.S. capital markets.
As Treasury Secretary Scott Bessent and FHFA Director Bill Pulte focus on housing market stability, the roadmap to exit conservatorship must avoid destructive, unnecessary shareholder dilution.
1. The Accounting Reality: The Principal is Paid
Taxpayers were made whole long ago. Fannie and Freddie drew ~$191B in crisis funding but have paid back over $300B in cash dividends - the original principal plus $100B+ extra. The current ~$300B+ Senior Preferred liquidation preference largely reflects unpaid dividends added to the balance and the Net Worth Sweep preventing paydown, not additional new taxpayer cash since 2012.
2. Why "Converting the Senior Preferred" is a Mistake
Converting hundreds of billions in paper liquidation preferences into common stock would severely punish existing shareholders who stayed invested through 18 years of conservatorship. A healthy U.S. market relies on property rights and contract law, not punitive dilution.
3. The Rational, Fair-Market Solution
- Deem/Cancel Senior Preferred: Recognize that the government's initial principal has been fully satisfied by past dividend sweeps.
- Address Warrants Cleanly: Settle or exercise the 79.9% Treasury warrants in a controlled, non-disruptive way.
- Adjust ERCF Capital Rules: Modernize the FHFA Enterprise Regulatory Capital Framework so the GSEs can safely exit without needing unrealistic amounts of new cash.
- Uplisting: Relist $FNMA and $FMCC on NYSE, unlocking true market valuation.
If the U.S. wants to invite private capital back into government-adjacent enterprises, it must show that contracts are honored and that success is rewarded - not penalized. 🇺🇸📈
Disclosure: Long $FNMA $FMCC since 2013. Not financial advice. Opinions are my own. Do your own due diligence.
@Pulte $FNMA $FMCC
FULL BREAKDOWN - How Each Step Lowers Rates & Why Investors/Taxpayers Still Win (For BOTH Fannie & Freddie):
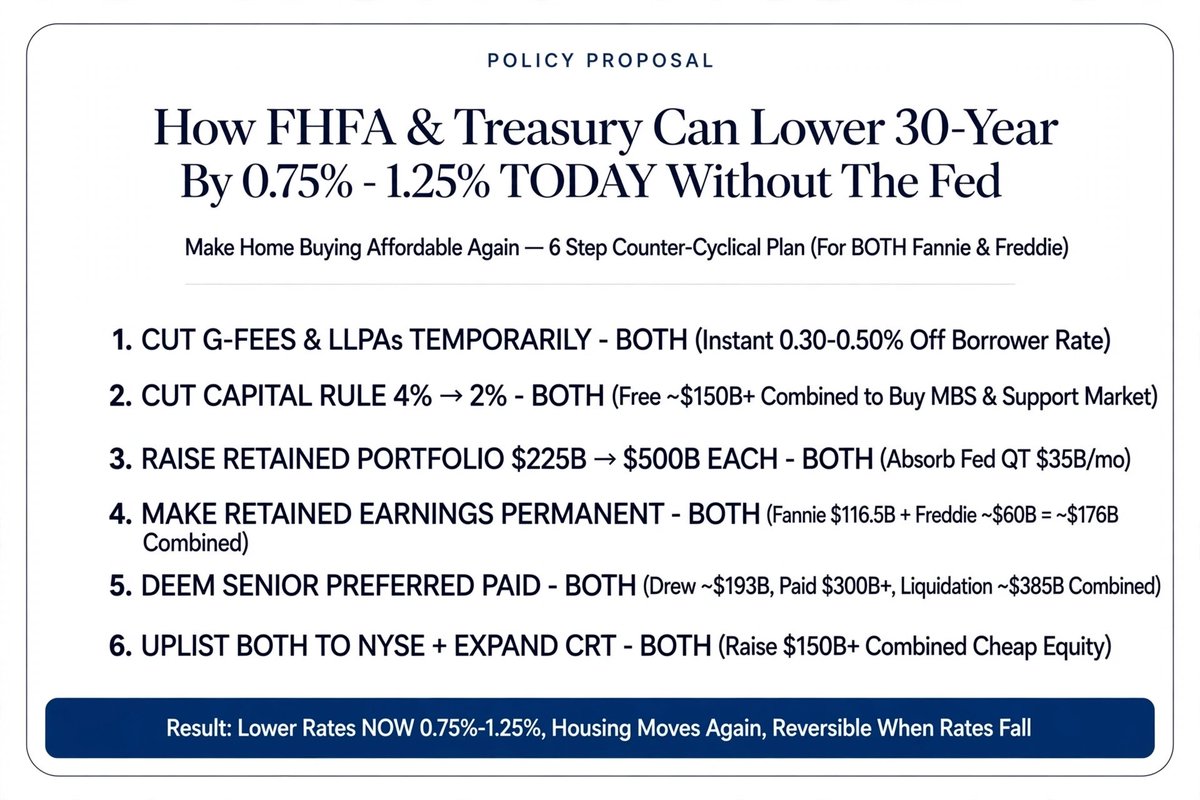
1. CUT G-FEES & LLPAs TEMPORARILY - BOTH (Instant 0.30-0.50% off borrower rate)
G-fee = annual insurance (~50-65bps) both charge lenders, passed to borrower. LLPA = upfront fee by FICO/LTV. 2022 FHFA added ~50bps extra on BOTH. Cutting = instant payment relief for homebuyers. How they still profit: VOLUME > MARGIN. Lower fee on $2T volume > higher fee on $1T frozen market.
2. CUT CAPITAL RULE 4% → 2% - BOTH (Free ~$150B+ combined to buy MBS)
ERCF 4% is worst-case buffer. Banks hold 4-5% on riskier assets. 2% is safe for agency MBS. Frees capital for BOTH to support market and buy MBS. Reversible to 2.25-2.5% when rates fall.
3. RAISE RETAINED PORTFOLIO $225B → $500B EACH - BOTH (Tighten spreads 25-40bps)
Current $225B cap is per company. Fed QT selling $35B MBS/month keeps spreads wide = high rates. Let BOTH absorb supply (up to $1T combined), spreads tighten = lower 30yr directly for homebuyers.
4. MAKE RETAINED EARNINGS PERMANENT - BOTH (Fannie $116.5B + Freddie ~$60B = ~$176B Combined = Core Capital)
Right now if EITHER retains earnings, liquidation grows $1 for $1 per Letter Agreement. Should count as core capital for BOTH, not grow Treasury claim. Instant recap for BOTH, no taxpayer cost. This capital is what lets them cut fees for homebuyers.
5. DEEM SENIOR PREFERRED PAID - BOTH (Drew ~$193B Combined, Paid $300B+ Combined, Liquidation ~$385B Combined)
Technical fix for BOTH. Drew ~$191B total, Paid $300B+ dividends, Liquidation now ~$385B combined with add-ons. Treasury already made ~$100B profit. Deem face paid for BOTH, credit overage to capital. Ends overhang. Taxpayer still holds 79.9% warrants in BOTH = upside.
6. UPLIST BOTH TO NYSE + EXPAND CRT - BOTH (Raise $75B+ each, $150B+ combined)
OTC can't raise efficiently. NYSE lets BOTH raise equity/preferred at 5% not 8%. CRT sells credit risk to private (Blackstone/PIMCO) lowering capital need for BOTH.
RESULT - MAIN STREET & HOMEBUYERS:
This is about homebuyers first. Lower 30yr 0.75%-1.25% = ~$300-$600/month lower payment on a $400k-$500k loan. That's the difference between renting forever and owning. For first-time buyers, move-up buyers, and families stuck on sidelines - this brings them back.
Housing moves again = builders $DHI $LEN $PHM build, construction jobs back, $HD $LOW furniture movers title companies busy.
Counter-cyclical & reversible: Trade margin for volume while rates high. When rates fall, FHFA can raise fees/capital 10-20bps on 2x volume. Homebuyers win NOW, workers win NOW, $FNMA $FMCC investors & taxpayers win bigger LATER via volume + warrant value.
---
Illustrative estimates only, based on my own calc from 10-Qs, FHFA ERCF, Fed H.4.1. Actuals may vary. Policy proposal for discussion only. Not financial advice, IMO. Not affiliated with FHFA, Treasury, Fannie Mae or Freddie Mac.
How FHFA & Treasury Can Lower 30-Year Mortgage Rates By 0.75% - 1.25% TODAY Without The Fed
Make Home Buying Affordable Again - 6 Step Counter-Cyclical Plan (For BOTH Fannie & Freddie)
[Details in comment below]
@Pulte@SecScottBessent@WhiteHouse $FNMA $FMCC
Policy proposal for discussion only. Not financial advice, IMO.
@bblakey121 Exactly right.
I'm long since 2013. Still believe in the system. Still believe in America.
3-0, 8-0 unanimous wins prove it. At some point DOJ defending the old conservatorship structure works against the admin's own goal to release and rebuild.
You nailed the political part - they are gambling with midterms. Release = votes + donations. $75 gets it done. Lose midterms, everything goes to waste!
Time to align policy with court wins. $FNMA $FMCC, NFA, IMO
Eddy makes a fair point. Shareholders have won unanimously - 3-0, 8-0. At some point DOJ continuing to defend the old conservatorship structure works against the admin's own goal to release and rebuild. Time to align policy with court wins. $FNMA $FMCC
@IMFpubs@realDonaldTrump@pulte Why r u DEFENDING prev admin who FRAUDED American shareholders? Why keep fighting after 3-0, 8-0 UNANIMOUS WON at Shrholders ! Y'all just talk No Commie while being HYPOCRITE TO THE MAX ! So many of us so upset, we will be NO RUSH TO THE POLL. NOT #MAGA
@PrincessSneech Sara, $FNMA $FMCC NWS harm was proven by a jury of 8 in Lamberth 2023: $612.4M for breach. That's not politics, that's contract law. Wall Street didn't write the NWS, Treasury did. IMO, NFA
To avoid dilution we need 2 things:
1) UPLIST first so price goes from $5 to $15+ IMO
2) Capital rule at 2.5% (or lower) not 4%
Then we raise little capital at high price = we don't get diluted. If we raise at $5 with 4% rule, we get wiped.
$FNMA $FMCC NFA, IMO, Please do your DD.
989 followers. 11 from 1K.
Pulte's tenure at DNI is done since early August. He's 100% back at FHFA now.
No more distractions. He should be 100% focused on what shareholders want:
UPLIST + RELEASE for $FNMA $FMCC
Follow along - we've held since 2013.
@bblakey121@bblakey121 Understand the frustration - -60% since May Truth Social pumps will do that. But UPLIST is 100% FHFA authority, no vote needed. RELEASE needs Treasury on warrants. Need timeline, not silence. $FNMA $FMCC
@63andConcerned@63an... He does for step 1 - FHFA can uplist to NYSE alone. Step 2 release needs Bessent/Trump on 79.9% warrants. That's why I split it: UPLIST + RELEASE. First part is fully on Pulte. $FNMA $FMCC, IMO
@2025Updated@2025Updated Agree he should. That's why we're holding him accountable daily. DNI done since August, no more distractions. He promised UPLIST + RELEASE - we track execution now. Held since 2013. $FNMA $FMCC
Respectfully Sara, there WAS harm - proven in court.
1. Paulson 2008: Took $FNMA $FMCC with 79.9% warrant at $0.00001, told Wall St friends weeks early commons would be wiped out, then wiped them.
2. 2012 NWS: Treasury took 100% of profits ~ $300B+, F2 made $28B+ last year and shareholders got $0. SCOTUS ruled that FHFA was unconstitutionally structured.
3. Ongoing harm: May 2025 Trump Truth Social pump to $14, then total silence. FNMA now $5 = -62% in 1 year, -55% since uplist talk. Retail bought the promise and is now down 60%. That's HARM too.
If no harm, why did gov lose 3-0, 8-0 unanimous?
Protect existing shareholders. End conservatorship. IMO, NFA
Exactly. Paulson took them down to save his Wall Street friends.
The President said it himself in 2021 to @RandPaul:
"My Administration would have sold the government's common stock at a huge profit and fully privatized $FNMA $FMCC. The idea that the government can steal money from its citizens is SOCIALISM and is a travesty brought to you by Obama/Biden."
Mr President @realDonaldTrump - When do you act on YOUR words?
End conservatorship. NFA.
@nicosintichakis Nico is 100% right. 18 YEARS waiting, Nov 2025 came and went, nothing but TV ads and silence.
We need ACTION not headlines. Protect existing shareholders, end conservatorship, return $FNMA $FMCC to NYSE where they belong.
No more moving goalposts. NFA.
@JonOksenholt@DoNotLose IMO both work - different risk/reward.
Commons = upside optionality on UPLIST + RELEASE
JPS = discount to par chase
I track commons mainly, but weakness here is interesting on both if thesis holds. NFA.
$FNMA $FMCC
@HorsemanCountry That means a lot coming from you Brother. Been watching your work in this space a long time.
We keep pushing - for the whole $FNMA $FMCC fam. Appreciate you! 🙏
We’ve all felt it R. Down 26% / 50% but nothing fundamental changed - that’s the conservatorship discount. IPO talk was a year ago, market wants a timeline, not talk. I’ve held since 2013 - this chop is normal before release. 10x needs warrants exercised + recap done. Timeline matters more than hype right now. $FNMA $FMCC, IMO NFA
@StockChaser_ Holding $ONDS here too. Analyst setup is unusual - 9 covers, Strong Buy, not one below current price. $19.42 avg = +162% from tonight's $7.40 close. Risk/reward skewed if they execute. NFA