The KV Cache bottleneck is quietly limiting every enterprise AI deployment running today.
Every AI conversation stores context in a memory bank called the KV cache. The more users. The longer the conversation. The bigger it grows. A single 70B model serving 500 concurrent users needs 1 to 2TB of live working memory. Standard servers top out at 1TB total.
Companies had three options. Cut users. Shorten conversations. Accept 10x slower responses by spilling to NVMe storage.
$PENG (~$2.6B) built a fourth. A dedicated CXL memory server that sits alongside the GPU cluster and handles KV cache overflow. Up to 22TB per node. 10x faster than NVMe. Native NVIDIA Dynamo integration out of the box.
One Tier-1 financial institution is running it in production. That is one confirmed customer.
CXL memory grows from $0.5B in 2024 to $22B by 2030. 88.8% CAGR
$PENG entered first with a validated shipping product.
The results of my research on $NBIS Founder CEO Arkady Volozh's history of meeting or exceeding revenue guidance. In summary this is not a man I would be willing to bet against as he leads Nebius into 2026.
Looking back at his days at Yandex, Arkady met or exceeded revenue guidance for every single year of the 12 years from public listing in 2011 to 2022 as CEO. This even accounts for instances where guidance was withdrawn (e.g., 2020 due to COVID-19 and 2022 due to geopolitical events) but actual results still aligned with or surpassed the initial targets.
Here's a breakdown of the results (in summary form courtesy of Grok):
2011
Initial Guidance: 55–60% YoY growth
Updated Guidance: Reaffirmed throughout
Actual YoY Growth: 60%
Met/Exceeded: Yes (top end)
Notes: Strong post-IPO performance; consistent quarterly momentum with no downward revisions.
2012
Initial Guidance: 40–45% YoY growth
Updated Guidance: Narrowed to upper end in Q3
Actual YoY Growth: 44%
Met/Exceeded: Yes (met)
Notes: Revenue RUB 28.8B, aligned with forecasts; positive updates reflected steady growth.
2013
Initial Guidance: 28–32% YoY growth
Updated Guidance: Raised to 30–35% in Q1, 34–38% in Q2, high end in Q3
Actual YoY Growth: 36%
Met/Exceeded: Yes (exceeded initial)
Notes: Multiple upward revisions driven by strong ad revenue; growth at top of final range.
2014
Initial Guidance: 25–30% YoY growth
Updated Guidance: Revised for economy (e.g., Q3: 27–30%)
Actual YoY Growth: 28.5%
Met/Exceeded: Yes (within revised)
Notes: Economic crisis (ruble devaluation) led to adjustments; met final range despite challenges.
2015
Initial Guidance: 15–18% YoY growth
Updated Guidance: Revised down in some quarters (e.g., Q3: 27–30% but overall aligned)
Actual YoY Growth: 17.8%
Met/Exceeded: Yes (within initial/revised)
Notes: Continued crisis impacted growth; one quarterly below initial but full year met with upward revisions later.
2016
Initial Guidance: 12–16% YoY growth (conservative)
Updated Guidance: Raised to 17–20% in Q1, 18–21% in Q2, 22–24% in Q3
Actual YoY Growth: 27%
Met/Exceeded: Yes (exceeded)
Notes: Strong outperformance across quarters; diversification into non-search segments.
2017
Initial Guidance: 22–23% YoY growth (from prior updates)
Updated Guidance: Incremental upward adjustments
Actual YoY Growth: 24%
Met/Exceeded: Yes (exceeded)
Notes: Consistent above-guidance performance; boosted by Google settlement and mobile gains.
2018
Initial Guidance: 25–30% YoY growth
Updated Guidance: Raised to 27–32% after Q1, then to 35–38% in Q3
Actual YoY Growth: 36%
Met/Exceeded: Yes (exceeded)
Notes: Robust growth in new segments like taxi and e-commerce; fastest growth in six years.
2019
Initial Guidance: 28–32% YoY growth
Updated Guidance: Raised to 30–34% in Q1, 32–36% in Q2, 36–38% in Q3
Actual YoY Growth: 37–39% (ex-Market deconsolidation)
Met/Exceeded: Yes (exceeded)
Notes: Multiple raises due to e-commerce and taxi momentum; excluded https://t.co/ZSyf3ugkNJ JV.
2020
Initial Guidance: 22–26% YoY growth
Updated Guidance: Withdrawn in Q1 due to COVID
Actual YoY Growth: 24%
Met/Exceeded: Yes (within initial, pre-withdrawal)
Notes: Resilient performance despite pandemic; revenue RUB 218.3B.
2021
Initial Guidance: 315–330B RUB absolute (~45% implied)
Updated Guidance: Raised to 330–340B in Q2, 340–350B in Q3
Actual YoY Growth: 63% (356B RUB)
Met/Exceeded: Yes (exceeded)
Notes: Explosive growth in services; exceeded all updates.
2022
Initial Guidance: 490–500B RUB (~38% implied)
Updated Guidance: Withdrawn in Q1 due to geopolitical events
Actual YoY Growth: 46% (522B RUB)
Met/Exceeded: N/A (guidance withdrawn, but exceeded initial)
Notes: Volozh stepped down mid-year; performance contributed during tenure exceeded pre-withdrawal target.
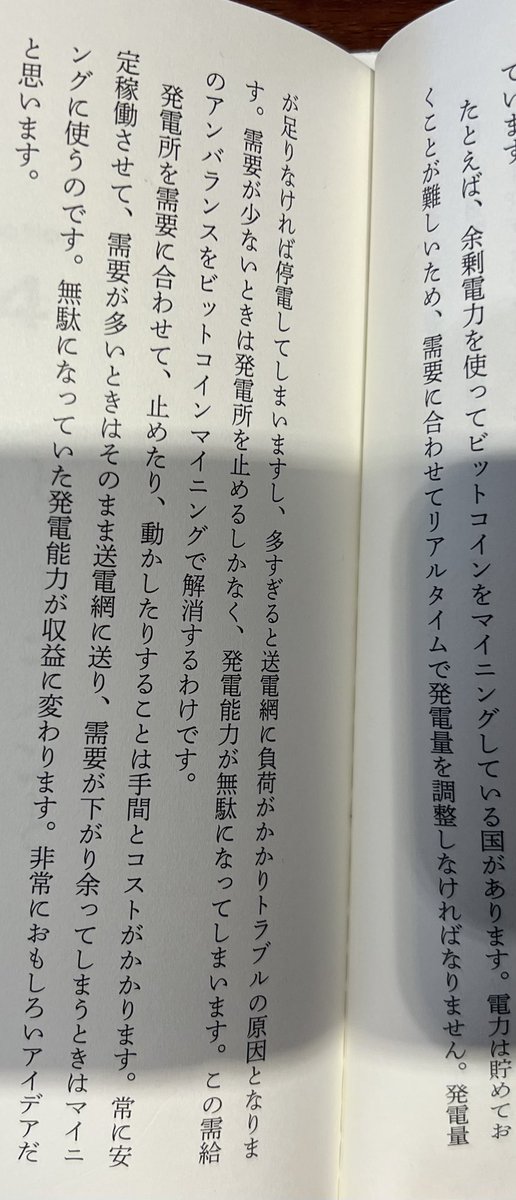
What’s the name of the book? It must be an interesting read! It talks about the waste (power scarcity) of power demand/supply. I don’t know if it has talked about the volatility of power demand/supply.
Now allow me to elaborate a little why we think what $can develops to date is of very high importance.
⸻
It’s All About Balancing The Grids
•Electricity grids must balance supply and demand in real time; most generation assets cannot rapidly adjust output.
•As renewable penetration increases, grid volatility—not energy scarcity—becomes the primary system constraint.
•Excess renewable generation creates grid frequency risk, not just energy waste.
•Bitcoin mining provides programmable, interruptible, price-responsive demand that can rapidly absorb surplus power.
•Mining loads can respond in seconds, making them well-suited for frequency and demand-response services.
•Used correctly, Bitcoin mining strengthens grid stability rather than competing with priority consumers.
⸻
Why Home Bitcoin Mining Matters
•Distributed home miners behave as small, independent loads rather than a single synchronized demand block.
•Decentralized load behavior reduces abrupt demand changes and smooths aggregate grid impact.
•Home miners are geographically dispersed, reducing concentration and single-point-of-failure risks.
•Aggregate stability improves when thousands of households respond independently to local grid conditions.
⸻
Grid Stability & Frequency Control
•Grid frequency must be maintained at 50Hz or 60Hz to avoid infrastructure damage or service interruptions.
•Supply-demand mismatches translate directly into frequency deviation.
•Flexible demand is one of the most effective tools for real-time frequency management.
•Bitcoin mining acts as a controllable demand layer, complementing existing grid control mechanisms.
⸻
Renewable Energy Integration
•Solar and wind generation frequently peak when demand is lowest.
•Curtailment destroys economic value and discourages renewable investment.
•Home mining improves the economics of rooftop solar by monetizing excess generation.
•Distributed mining reduces reliance on costly grid-scale storage for short-duration balancing.
⸻
Home Mining vs. Industrial Mining (Balanced Framing)
•Large-scale mining offers significant flexibility but can introduce synchronized load risks.
•Home miners provide granular, statistically smoothing demand response.
•A mixed ecosystem—industrial plus home mining—creates better overall grid resilience.
•Distribution matters as much as total load when managing frequency stability.
⸻
Energy Efficiency & Heat Reuse
•Home miners generate usable heat as a byproduct of computation.
•That heat can displace traditional electric or gas heating loads.
•In cold or temperate climates, mining improves total energy efficiency at the household level.
⸻
Decentralization & Resilience
•Home mining aligns economic incentives with grid needs without central coordination.
•No mandates, subsidies, or behavioral monitoring are required.
•Expansion happens organically where excess or low-cost energy exists.
•The same decentralization that secures Bitcoin also increases energy system resilience.
⸻
Policy-Facing Messaging
•Bitcoin mining is best understood as demand-side infrastructure, not generation.
•Flexible load is essential for achieving renewable-heavy grid targets.
•Home mining supports grid stability while empowering households to participate directly.
•Policymakers should differentiate between distributed mining and concentrated industrial loads.
@BLUE_chinese@GwynLauber@yifan75222410@CahillBit
@herder1981
Thanks for bringing up my post and expanding on it — really appreciate it!
The book is titled
“Web3・暗号資産:11人の未来予測
― ブロックチェーン・ビットコイン・投資動向まで、時代を乗り切る価値と金融の指針”
(As far as I know, it’s only available in Japanese.)
It dives deep into blockchain technology and where it could be headed in the future.
I had never realized how big of a challenge grid stability was — and was even more surprised to learn that Canaan’s technology is already being positioned as part of the solution.
Looking ahead, the energy transition feels inevitable and increasingly critical.
I’m hopeful that Canaan can ride this wave and play a meaningful role going forward✊
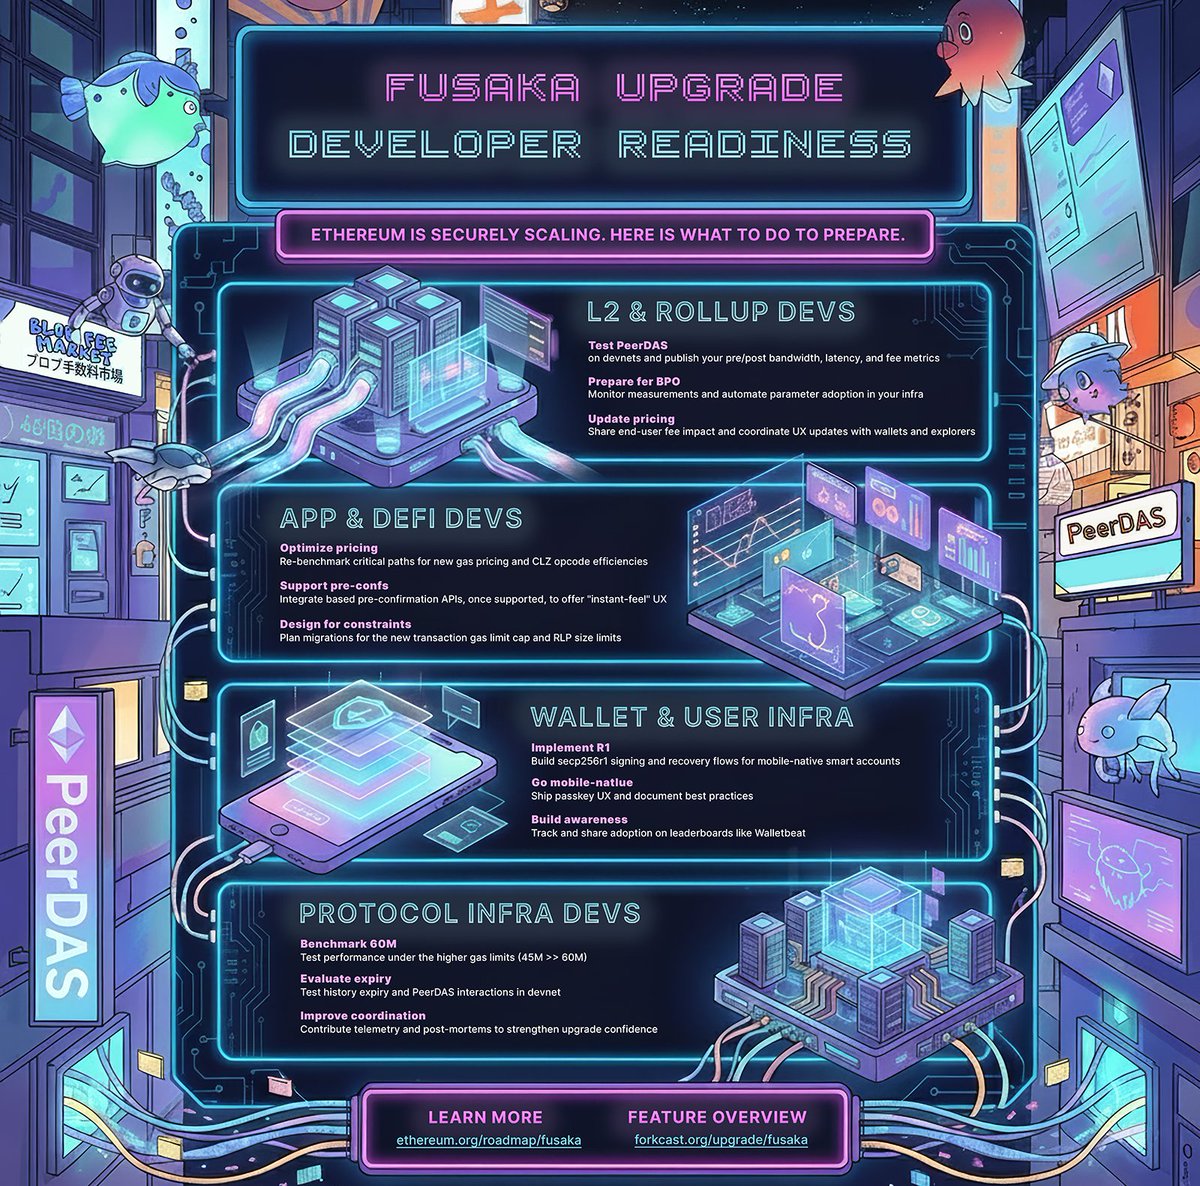
1/ The Fusaka upgrade is coming December 3rd.
Ethereum is securely scaling.
Are you ready to support the changes?
Here’s what developers across the ecosystem need to do to prepare 🧵
$CAN ホルダーは必読。
中国のマイニングが、静かに「戻ってきている」可能性について。
市場では、
中国のマイニング再拡大が「ここ数年で最重要シグナルの一つ」と報じられています。
“The resurgence of mining activity in China is one of the most important signals the market has seen in years.”
報道ベースの事実
・中国のハッシュレート:約14%(世界第3位級)
・新疆・四川など電力の安い地域で地下稼働
・余剰電力 × 低コストで実質再起動
さらに──
“The resurgence in bitcoin mining, which has also been corroborated by rig maker Canaan Inc.’s fast-rebounding sales in China, could act as a demand and price support for the world’s largest cryptocurrency.”
とあり、Canaanの中国向け販売回復が、
マイニング再開を裏付ける「実需データ」として挙げられています。
機器が売れる=掘る意思決定が発生。
噂ではなく「設備投資」という事実が動いている、ということ。
※中国政府は公式には今も禁止のままですが、一部地域では事実上の黙認状態が広がっているとも報じられています。
背景には、水力・石炭由来の構造的な電力余剰があり、規制よりも経済合理性が勝ち始めている面も。
2021年に採掘を禁じた中国が、もし実質的に緩和へ向かうなら──
Bitcoin × $CAN にとって「構造的な追い風」になる可能性。
興味ある方は是非記事を読んでみてください。
https://t.co/3BZs4hIZ6N
#カナン#ビットコイン