🚨 THE PAYDAY LOAN DEBT TRAP: A HIDDEN CRISIS FOR INDIA’S MIDDLE CLASS.
10% upfront deductions. Interest reportedly as high as 1% per day. That’s 365% annually on a simple-interest basis, before accounting for upfront fees and other charges—making the effective APR potentially higher.
Borrowers take new loans to repay old ones. Debt piles up, and in extreme cases, repayments can reportedly reach 1,000–3,000% of monthly income.
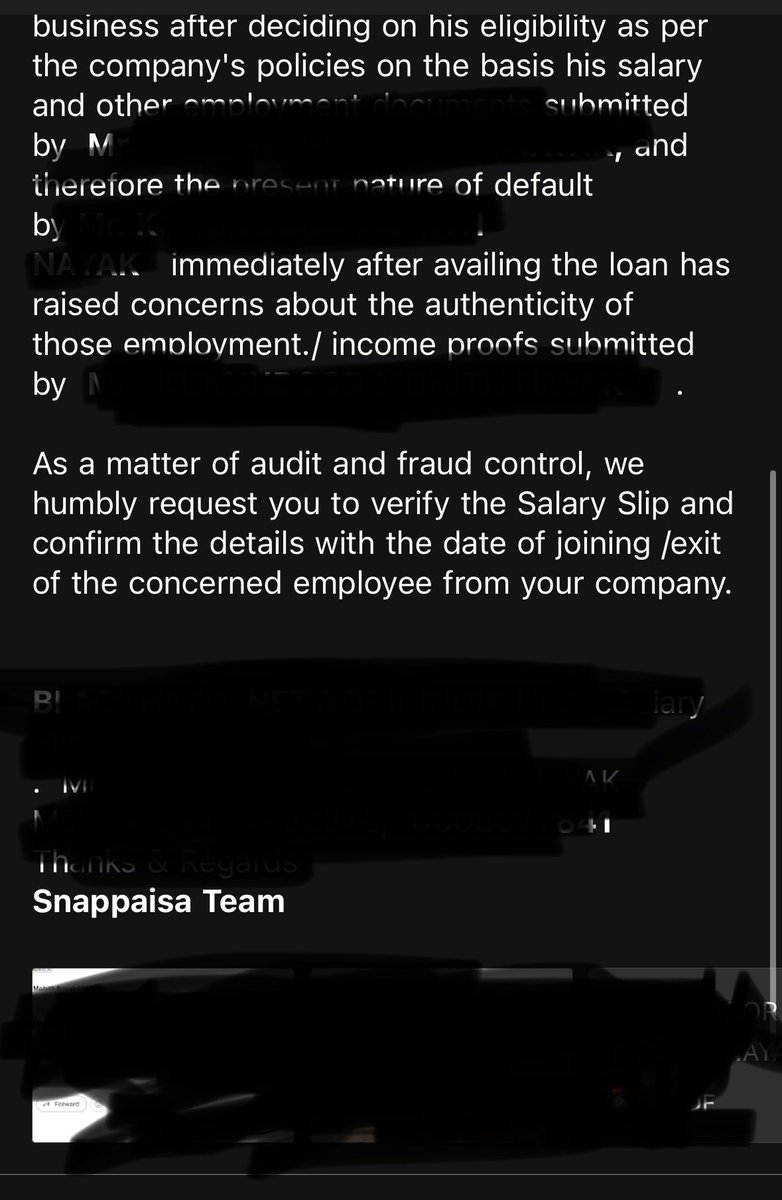
When borrowers can no longer pay, they report relentless calls, contact with people never listed as references, social-media skip-tracing, and threatening emails to employers and senior management.
Salary disappears. Debt multiplies. Families suffer. The harassment continues.
@suchetadalal@dhruv_rathee@poonamjourno@saynotoloans
#PaydayLoans #DebtTrap #India #banpaydayloans
@savehumanityt it is designed to be a trap, you take loan for emergency as your score is not good from these companies by the month end you wont be able to pay and you take another one and cycle continues. am raising complaints from one year till now no action from @RBI@FinMinIndia
@saynotoloans just because my loan payment was delayed by 1 day they sent a mail to my company HR not only that, they looked up into linkedin and forwarded this mail to directors of my company also.. @RBI@FinMinIndia@nsitharaman@AmitShah@HomeMinistr2024.. This is also debt trap.
5/6
This cannot continue. Are these entities protected due to high-level political connections? The common man is suffering. Time for strict regulation, licence review, and crackdown on illegal recovery practices.
3/6
Worse — digital harassment has become their standard operating model. They shamelessly call friends & relatives, email HR departments, and use every dirty tactic to humiliate borrowers. All these apps follow the exact same pattern.
2/6
Shockingly, many of these are RBI-registered NBFCs. How did RBI grant licences without proper due diligence on their business model, recovery practices & real interest rates? What is @FinMinIndia and Hon’ble FM @nsitharaman doing about this? @RBI@GovSMalhotra
1/6
Payday loan apps & NBFCs are trapping millions in deadly debt cycles. Charging 1% interest PER DAY (that’s ~365% per year), they push desperate people into a never-ending trap. People take these loans only for emergencies, yet these companies ruthlessly exploit the situation.