Most tech giants in the 2000s built their infrastructure and product as one entangled unit. Amazon had the foresight to separate out AWS as an API layer, of which Amazon retail was the first of many users. Today, AWS generates more profit than all of Amazon's other business lines combined.
Hyperliquid is built with the same philosophy. Housing all of finance requires thoughtfully designed, open financial primitives. Each primitive should obey the Unix principle of "Do one thing and do it well." Talented builders then have the foundation to chain these together to create magical applications.
HyperCore borrowing is an example to highlight this philosophy in action.
Most other platforms implement portfolio margin by marking an account's collateral to market value with an LTV haircut, creating borrowed assets without an explicit lender. This system is simpler to implement, but misses a golden opportunity for composability.
Hyperliquid instead begins with a borrow/lend protocol on HyperCore. Every borrowed asset is sourced from a supplier, so risk is isolated within the borrow/lend primitive instead of platform-wide. HyperCore's portfolio margin system is implemented as an orchestration layer that composes borrow/lend, with other primitives such as perps, spot, and outcome trading.
This decomposition has several nice corollaries:
1. Today's announcement of manual borrowing is not a new feature, but simply an extension of the underlying primitive. Borrowers on day one have access to 400M and growing of supplied liquidity.
2. Portfolio margin users earn interest on their idle stablecoin collateral. This is not a new feature, but a natural byproduct of composing trading with lending.
3. System safety is easier to reason about when perp and borrow/lend margining are independent.
In the same way that math theorems almost prove themselves when the right abstractions are defined, composable designs just feel right.
Manual borrows are live on Hyperliquid
Portfolio margin and manual borrows use the same underlying HyperCore infrastructure, with $269M in assets borrowed today.
Users can supply HYPE and BTC as collateral to borrow quote assets (USDC and USDT). Borrowed quote assets pay interest, and supplied quote assets earn interest, with rates set by utilization.
Someone recently shared this paper with me, which rigorously studies the execution improvement of visible TWAPs on Hyperliquid: "Trading in the Sunshine or in the Shade: Market Impact and Adverse Selection on Hyperliquid," by Davide Barone and Fabrizio Lillo.
In physics, theorists can say all they want, but the case isn't closed until an experimentalist comes with the cold hard data. So thank you to the authors of this paper for their hard work! The paper demonstrates that liquidity net tightens as onchain TWAPs surface, improving the average execution of the TWAP order.
This has been a deeply personal question for me. Even before building Hyperliquid, I've defended from first principles that transparent trading ought to improve execution for non-toxic flow. This is a corrollary of the efficient market hypothesis, but the amount of pushback always surprised me. I've quote tweeted a previous post where I make the argument in detail.
Transparency and equal access bring improved execution over traditional private venues. It's an honor to build with everyone to upgrade the financial system with onchain technology.
Thank you to everyone who took the time to thoughtfully respond to my post on transparent markets. I understand that the thesis is controversial and that Hyperliquid is at a new frontier as the first fully transparent order book venue of its scale.
I could well be mistaken, and welcome the continuous dialogue on market structure innovation. However, many criticisms I saw stemmed from misunderstandings, with some points actually supporting transparent systems like Hyperliquid. Market structure is notoriously counterintuitive, and novel approaches often challenge established paradigms, leading to understandable skepticism.
For example, Hyperliquid pioneered protocol-level cancel prioritization, which has since been implemented by new DEXs and even inspired novel transaction ordering ideas on other blockchains. But at the time, it was considered controversial because it went against traditional market design. I hope that transparent trading will follow a similar path to adoption.
I may have been too ambitious trying to cover a complex argument in a single post. Given the specific patterns in criticisms, I'd like to take this opportunity to zoom in on nuances that were missed in the high level summary. What follows is an argument for the final state of efficient markets, with the understanding that Hyperliquid is far from fully efficient today. However, inefficiency is opportunity for those hungry to act. Hopefully this post can also be a call to action for traders, market makers, and builders to translate transparent markets into the highest quality execution venue for all.
--
Before delving into specific concerns, let’s crystallize some counterintuitive principles that can form a helpful mental model for market structure:
1. Counterparty principle: Benefits of counterparty curation are misattributed to privacy.
Users ultimately care about execution. As studies have shown though, privacy sells. Alternative trading venues often market privacy as the causal feature for improving execution. In reality, the primary source of benefit for users is the screening of counterparties allowed to participate on the venue. Hyperliquid’s market design provides these same benefits more directly and effectively than patchwork solutions. Hyperliquid’s solution also democratizes access, improving execution for all traders large and small.
Note that transparency does not mean doxxing. Of course, the exact identity of some traders will fundamentally change the value of the asset. But those traders need not dox themselves, e.g. Warren Buffet can buy BTC and benefit from transparent markets, without tying his identity to his address.
2. Competition principle: Maximizing competition is key to improving execution.
Many traders who want to execute in size have some form of alpha. However, the group of informed medium/long term traders in aggregate is difficult to distinguish even over yearly timeframes, as their realized sharpe is too low for statistical significance. It is challenging to distinguish between a trader with solid medium term alpha and a degenerate gambler who got lucky. Therefore, while the desire to minimize market impact and alpha leakage is natural, it’s usually outweighed by the improved liquidity from transparent markets.
Traders therefore see improved execution despite revealing their strategy, as market makers are bound to provide liquidity to the entire range of flows in the market. Competition is the bedrock of capital markets and economics. As an example, the Hyperliquid order books support an onchain TWAP. Such a broadcasted intent to trade is in fact a reasonable proxy for optimal execution. Market makers will immediately fill some size so that the earlier TWAP orders receive worse execution, but will also compete to fill the remaining flow. The competition between market makers ensures near optimal overall execution over the course of the TWAP. Any inefficiency in execution is an opportunity for another market maker to undercut the others.
3. Repeated games principle: Execution improves when one-time games become repeated games.
Market makers evaluate each decision from a game-theoretical framework, as they are in the business of making positive expectancy bets. On Hyperliquid, every account placing more than one order is playing a repeated game. Repeated games have dramatically different optimal strategies from the one-time games of private venues, and the resulting equilibrium is better execution for everyone other than toxic extractors. Competition is essential for the optimal market marker strategy to benefit the end user, which is amplified by the next principle.
4. Full transparency principle: Benefits from transparency are non-linear and only manifest when transparency is at the system level.
When optimizing for execution, “the system knows” > “no one knows” > “some people know.” The worst of the three states is where some insiders have privileged information. Those insiders can act exploitatively to extract profit from end users. Because L3 books are not transparent in tradfi, the “darker” venues often implement systems to unilaterally apply counterparty-specific filtering to trades. Hyperliquid achieves the same effect on a lit venue and therefore maintains the benefits of efficient order book execution.
--
Common criticisms to the initial post, and my responses [I’ve bracketed references to the different principles]:
1. Many large desks in tradfi trade OTC, which is evidence that public venues cannot support large size.
Response: This point actually supports Hyperliquid. In tradfi's L3 books, there is no reliable way to broadcast your identity trustlessly to all counterparties. Using an OTC desk is a compromise, telling a small set of professional counterparties that you are non-toxic. Like trading on an L4 order book, trading OTC is a repeated game where the OTC desk is quick to ban any counterparties that adversely select a small fraction of quotes, or engage in otherwise toxic behavior [repeated games principle]. The OTC desks offer quotes where their own algorithmic execution/hedging costs are below the markup, which is only possible when their fills’ immediate markouts are positive.
A Hyperliquid whale who places an onchain TWAP order is effectively routing their flow to every "OTC desk" plugged into Hyperliquid. When OTC counterparties expand from a select few to all market makers, the competition improves execution for the user compared to the bespoke OTC quote [competition principle]. In summary, execution on Hyperliquid incorporates the efficiency of lit venues with the counterparty signaling of OTC. This high quality execution is available to all users equally.
2. A large percentage of tradfi volume happens on dark pools, retail internalizer systems, etc.
Response: This argument also supports Hyperliquid. The basic idea behind dark pools is that two large whales with a "coincidence of wants" can match immediately and bypass the spread that lit markets charge. Until such a match exists, orders are attempted to be kept private to reduce market impact. While a neat idea at first glance, the privacy of dark pools is unlikely to meaningfully protect intentions or improve execution. For example, sophisticated actors participate in dark pools themselves. At a minimum, their fills are a strong signal on the supposedly private flow. This shares many parallels with the insider information discussed in the following section. Information that will be deduced anyway is better made public [full transparency principle].
As another argument against the effectiveness of privacy properties, dark pools rely heavily on participants having identities known to the pool operator [repeated games principle]. This is necessary because the private information is easily leaked. There are strict requirements for participation, e.g. high fill rate, minimum order size, and negative short term markouts. Offenders with toxic behavior are banned or deprioritized [counterparty principle]. Like OTC desks discussed above, transparent L4 books on Hyperliquid incorporate and improve upon many of these positive properties of dark pools within an open, systematic framework.
3. Public data allows hunting of liquidations/stops.
Response: Most would agree that unlike size information, preserving margin privacy is beneficial for the end user. Perhaps a ZK privacy implementation can accomplish this in the future. However, until then, users are less likely to be successfully hunted if everyone knows liquidation and stop prices than when only the exchange operator knows [full transparency principle]. Two reasons:
a. On CEXs, your position information is far from private. Based on empirical data of insider trading leading up to listings, one should assume that liquidations and stops are also vulnerable to misuse. This can be despite best efforts from management: it is extremely difficult to completely control large organizations from leaking information. When insiders hunt stops and liquidations, there is no public data for other market makers to understand the source of the temporary dislocation. This decreases the required capital to successfully push the price.
b. In the game theoretical equilibrium of transparent data, stop and liquidation hunting are likely unprofitable endeavors on average. Whales are protected by the entire system of market participants acting rationally. People trying to hunt liquidations and stops will be counteracted by people trying to trick them into the hunting. For example, someone who wants to open a large long position can execute half of their position on high leverage, bait the hunters to short, then increase collateral and enter the remaining desired position at a more favorable price. As long as some profit seeking “anti-hunters” exist, all whales benefit from the cover.
While point (b) will take time to play out, markets are ultimately efficient. Even before this equilibrium is reached, the full transparency principle in point (a) suggests Hyperliquid's model offers more robust protection for whales. Liquidity is generally deeper when lit venues are more transparent [competition principle], which further increases the cost of liquidation and stop hunting.
4. Some users have alpha and will not benefit from transparency.
Response: The users that are disadvantaged by Hyperliquid’s system are a very small set of “toxic” participants. These are the same adversarial traders that dark pools, OTC desks, and other solutions try to avoid. A small number of professional HFT firms have alpha on this timescale, and it’s a failing of traditional market structure that these toxic takers have the ability to tax all other users of the system.
As an aside, short term alpha and toxicity is a continuous spectrum, so I’m oversimplifying for sake of argument. For example, there are intraday quantitative strategies that can realize significant sharpe ratios, whose flow could be a reliable momentum signal for market makers. The technical reason this is not a problem is that cost to rotate accounts is proportional to fee sensitivity of the strategy, which is inversely proportional to the time it takes for others to detect the strategy with statistical significance. In other words, the more execution matters to a quant strategy, the less the burden of obfuscation.
Regardless, the vast majority of users on Hyperliquid do not fall remotely close to this category of quantitative, toxic alpha. Note that “toxic” does not mean “informed,” but rather traders who profit non-constructively from slight infrastructural or other structural advantages such as latency. Hyperliquid's cancel prioritization and L4 order book essentially boost the short term liquidity available to non-toxic small and large orders, respectively. As a conservative lower bound, as long as market maker counterparties on Hyperliquid can hedge in time on other venues, the trader benefits from Hyperliquid’s system.
--
I know I’ve missed other points, but will stop here to keep this post digestible. Thanks again to everyone for their thoughtful feedback, especially those who took time to review an earlier version of this post. I look forward to continuing this discussion!
This is a cool dashboard: historical and realtime liquidity comparisons across venues. Hyperliquid is not only the most liquid venue for major crypto and RWA perps, it's more liquid by an *order of magnitude* for some of them like the S&P500.
Thanks to the ASXN team for building this!
We shipped a new Liquidity Comparison dashboard: cross-venue liquidity analytics for @HyperliquidX vs Binance, Coinbase, Lighter, OKX, and Bybit.
Compare depth, spreads, and slippage across venues in real time.
Thanks for having me on the podcast! It was a great conversation about a new category of integration: the first centralized exchange directly tapping into Hyperliquid's onchain infrastructure.
Following the recent launch of Perps on VALR, and our integration of @HyperliquidX, VALR's Co-Founder and CEO @farzamehsani sat down with Hyperliquid's Co-Founder and CEO Jeff Yan (@chameleon_jeff) to discuss the integration, the future of CeFi and DeFi, and their aspirations to move finance forward.
Africa's largest crypto exchange will power their core perps offering directly using Hyperliquid's onchain liquidity. This is a major milestone that will redefine how the next generation of financial applications are built.
The breakthrough of cloud computing was that any startup could quickly test their idea, with the comfort that the infrastructure would scale with their business. As the most liquid global venue for assets such as BTC, Hyperliquid will play the same role in the global economy. By tapping into the deepest onchain liquidity, builders can instead focus on their product and users.
Huge congratulations to the VALR team. We are honored that they chose to build on Hyperliquid. Excited to scale together!
We are pleased to announce the imminent launch of 'Perps' on VALR, a new cross-asset class perpetuals product that introduces more than 200 markets to the platform.
The new product is delivered through an integration of @HyperliquidX. Using Hyperliquid’s permissionless infrastructure, VALR users can open and manage positions directly on VALR, ensuring a seamless user experience.
The newly available contracts span multiple global asset classes, including equities, indices, commodities, precious metals, forex, and crypto assets, enabling traders to capitalise on volatility.
Perps on VALR are set to go live on the web on Monday, 6 July, with mobile app availability to follow shortly after.
I spent the past few days in Washington with @hyperliquidpc meeting with policymakers during the historic advancement of the Clarity Act. We discussed Hyperliquid, the benefits that it offers to American consumers, and the regulatory path to bring onchain derivatives markets into the United States.
Some conversations were technical with an impressive baseline understanding of Hyperliquid. Discussions included how onchain trading is a financial innovation that has clear global user demand. Other conversations focused more on a first principles introduction to defi and the promise of onchain markets. It was encouraging to see bipartisan support for thoughtful regulation of crypto. I look forward to continuing discussions in DC and working hard to make American access to Hyperliquid a reality.
Excited to see everyone come together for this historic moment. AQAv2 brings the protocol-aligned stablecoin model that @Nativemarkets trail-blazed to USDC with @Coinbase and @Circle's commitment to Hyperliquid. The community no longer has to choose between liquidity and alignment.
Our industry will face adversity as we continue to grow. It gives me hope seeing titans of the industry come together to build for users and bring all of finance onchain.
Coinbase has announced its plan to activate AQAv2 on USDC as the treasury deployer, with Circle serving as the technical deployer responsible for CCTP and native cross-chain infrastructure. Both Coinbase and Circle have committed to stake HYPE to activate AQAv2. As part of this transition, Native Markets has agreed to terms granting Coinbase the right to purchase the USDH brand assets. With Coinbase, in its role as treasury deployer, sharing the vast majority of reserve yield revenue with the protocol, USDC will become the most aligned stablecoin on Hyperliquid. As a result, canonical outcome (HIP-4) markets will use USDC as the quote asset in a future network upgrade.
User and builder feedback has been consistent that fragmentation leads to degraded experience; now, the community no longer needs to choose between liquidity and protocol alignment.
The pioneering work of Native Markets in launching USDH as the first production-scale stablecoin sharing yield directly with a protocol in a purely onchain implementation made AQAv2 possible. The learnings and mechanics pioneered by USDH will live on in AQAv2.
The Hyper Foundation will give grants to eligible HIP-3 deployers, HIP-1 deployers, and builders who integrated USDH, supporting teams through migration over the next months. These grants reflect an ongoing commitment to teams who choose to build on Hyperliquid and align with the protocol. USDH markets are fully functional but will sunset over time. USDH remains fully backed, with feeless conversions to USDC and fiat available to users during this transition.
Thanks @domcooke for spending months on researching and writing this piece. Einstein once said, "If you can't explain it simply, you don't understand it well enough." By that measure, Dom has blown me away with how deeply he came to understand Hyperliquid and what we're all building together.
When someone asks what "housing all of finance" means, I'm proud to point them to this piece. I hope readers appreciate just how much Dom and his team put into their work. It reflects the thoughtful craft that is in Hyperliquid's DNA. Special thanks to @patrick_oshag for taking a bet on Hyperliquid's story.
This is the story of Hyperliquid, the most profitable startup per employee on earth, told from a guarded office in Singapore.
Last year, its team of 11 generated $900 million in profit. It's 3 years old, has never taken a dollar of venture capital, and is beginning to change how century-old markets work.
Its founder, Jeffrey Yan (@chameleon_jeff), had never taken a physics class when he picked up a textbook at 16. Two years later, he won gold at the International Physics Olympiad. In 2019, he started trading with $10,000 from a living room in Puerto Rico—working off a television because he didn't own a monitor.
Within 3 years, he was running one of the largest anonymous crypto trading firms.
Then he shut it down. Yan was rich and free, but he had spent years inside crypto, watching it betray itself. Bitcoin's central premise was decentralization. Yet the biggest exchanges were centralized. Crypto kept reintroducing the dependence on trust it was built to eliminate. He set out to create what should have existed.
Hyperliquid is a blockchain with a trading exchange on top, and anyone can build on it. Yan's vision is to house all of finance. In 3 years, it has done over $4 trillion in volume. And in the past few months, it has begun to outgrow crypto.
Markets for oil, silver, and the S&P 500 now trade on Hyperliquid around the clock, weekends included, and are growing roughly 40% week on week. When the US and Israel bombed Iran on a Saturday in February, Hyperliquid was the venue traders turned to.
Hyperliquid's success has cost Yan his freedom. He works out of a secret office in Singapore and cannot travel without two bodyguards. Even the team's housekeeper doesn't know what they do.
In January, @domcooke spent a week at their office. Read his profile on Yan and @HyperliquidX below.
Huge congratulations to TradeXYZ and S&P for this historic partnership. I'm honored that these teams choose to build on Hyperliquid.
Seeing official S&P500 perpetual futures launch exclusively on Hyperliquid is a validation of everyone's past years of hard work: global access to decentralized finance, perpetual futures as 24/7 price discovery, and Hyperliquid upgrading the existing financial stack to house all of finance.
The S&P500 is synonymous with "the market," a single number that captures the essence of the largest economy in the world. Looking forward to tracking the world's most important financial gauge 24/7 on the most liquid permissionless markets.
S&P Dow Jones Indices and trade[XYZ] have joined forces to launch the first official S&P 500 perpetual contract, available exclusively on Hyperliquid.
For 69 years, the S&P 500 has been a defining reference point for global finance. Until now, access to that benchmark has been shaped by market hours, intermediaries, and geography. Today, that changes.
The S&P 500 perp is now available 24/7/365, anchored by the official index data required for deep liquidity and institutional confidence at scale.
SPDJI helped define modern indexing. They are stewards of an iconic benchmark, the standard against which portfolios across the globe are measured. We are honored to bring that legacy on-chain.
Trade[XYZ] is bringing the world's most iconic assets towards a future of global, continuous markets — a future powered by Hyperliquid.
It was great to have a second conversation with @KevinWSHPod more than a year after the first. While the first conversation was a general introduction to Hyperliquid's mission and philosophy, the second goes deeper into technical points. We also discuss how the ecosystem and vision have expanded since then. Thanks for having me on!
E159: @Hyperliquidx: Housing all of Finance
@chameleon_jeff came back on the When Shift Happens Podcast to talk about the Hyperliquid journey since the TGE and what the future holds for one of the most loved and prolific protocols in the space
Hyperliquid
Timestamps
0:00 Intro
2:01 Singapore
2:27 Reminiscing on the Token Launch
5:00 Was This Scale Of Wealth Expected?
6:28 Doing The Right Thing In Crypto
9:07 The Responsibility that comes with Billions of $
11:10 @JupiterExchange@KASTxyz
11:51 Bringing Hyperliquid to the masses
15:21 Pre TGE and Post TGE: Operational difference
20:13 Choices on what to build Internally vs Externally
22:05 How to build a reliable team
24:51 Did the Team celebrate the HYPE wealth Generation event?
26:45 How to test talents for High Integrity
28:31 How much does the Hyperliquid team sleep?
30:05 Employee Vesting Fears
31:41 Dealing with FUD
32:28 How Does Jeff Personally Handle FUD
35:02 Token "Buybacks" critics
37:20 Why Hyperliquid can't have Discretionary "Buybacks"
39:04 HyperEVM, explained Simply
40:00 @paradex@zodl_app
40:41 HyperEVM: Success so Far?
44:05 HIP-3, explained Simply
47:44 What makes Hyperliquid's approach different
48:19 Why Should People Care?
51:33 Bring All Finance On Chain
52:08 Why Is The Hyperliquid Approach Better?
53:47 Key Numbers showing that Hyperliquid Is Doing it right
59:01 What Has the @unitxyz team demonstrated with spot trading on Hyperliquid in 2025
1:03:29 HIP-4: Outcome Markets
1:08:01 @Trezor@bitwise@SuiNetwork
1:08:58 What does "Housing All Of Finance" mean?
1:10:51 Why Hyperliquid is not a crypto company
1:12:23 Why Does Hyperliquid have A Stablecoin USDH (@nativemarkets)
1:14:39 What Is @Kinetiq_xyz & Why Does It Matter?
1:16:15 Why Is What @Hyperlendx Is Building Important For HyperLiquid
1:23:39 Where did Fairness cost the most?
1:24:47 What should Hyperliquid be Remembered for?
1:25:24 Why should people stay in Crypto when there's an AI brain drain?
1:28:10 Closing Thoughts
I’m excited to support the @HyperliquidPC launch. The Hyperliquid ecosystem needs a policy voice that represents our core values in DC. I’ve gotten to know @jchervinsky and seen his principled and unwavering support of defi over the years. There is no better person to advocate for Hyperliquid and defi broadly in this critical time in policy discussions. HPC will champion the message that Hyperliquid and defi align with core American values: transparency, fairness, and financial freedom for all.
Since the chain’s genesis three years ago, Hyperliquid has pushed the limits of decentralized financial infrastructure. It’s been an honor to work with such a passionate and diverse group of builders toward the ambitious goal of housing all of finance in a fair and transparent system. However, this decentralized stewardship and development meant that Hyperliquid lacked a unified voice in important policy discussions until now.
At this point, Hyperliquid has grown to where “housing all of finance” is more than a tagline. There is a tangible and urgent possibility of upgrading the tech stack of the existing financial system, bringing immense value and accessibility to everyone. Democratizing finance requires education and advocacy for laws that protect users and builders alike. Global financial regulation will be shaped in the United States, and we must work to ensure that these new policies thoughtfully embrace the potential of the new financial system enabled by Hyperliquid. I’m confident that the team at HPC will take on this challenge and push for a clear, regulated path for defi to thrive.
We are Hyperliquid Policy Center.
HPC is a research and advocacy nonprofit focused on advancing a clear path for decentralized finance to thrive in the USA.
We will introduce policymakers to @HyperliquidX and bridge the gap between law and next-generation market infrastructure.
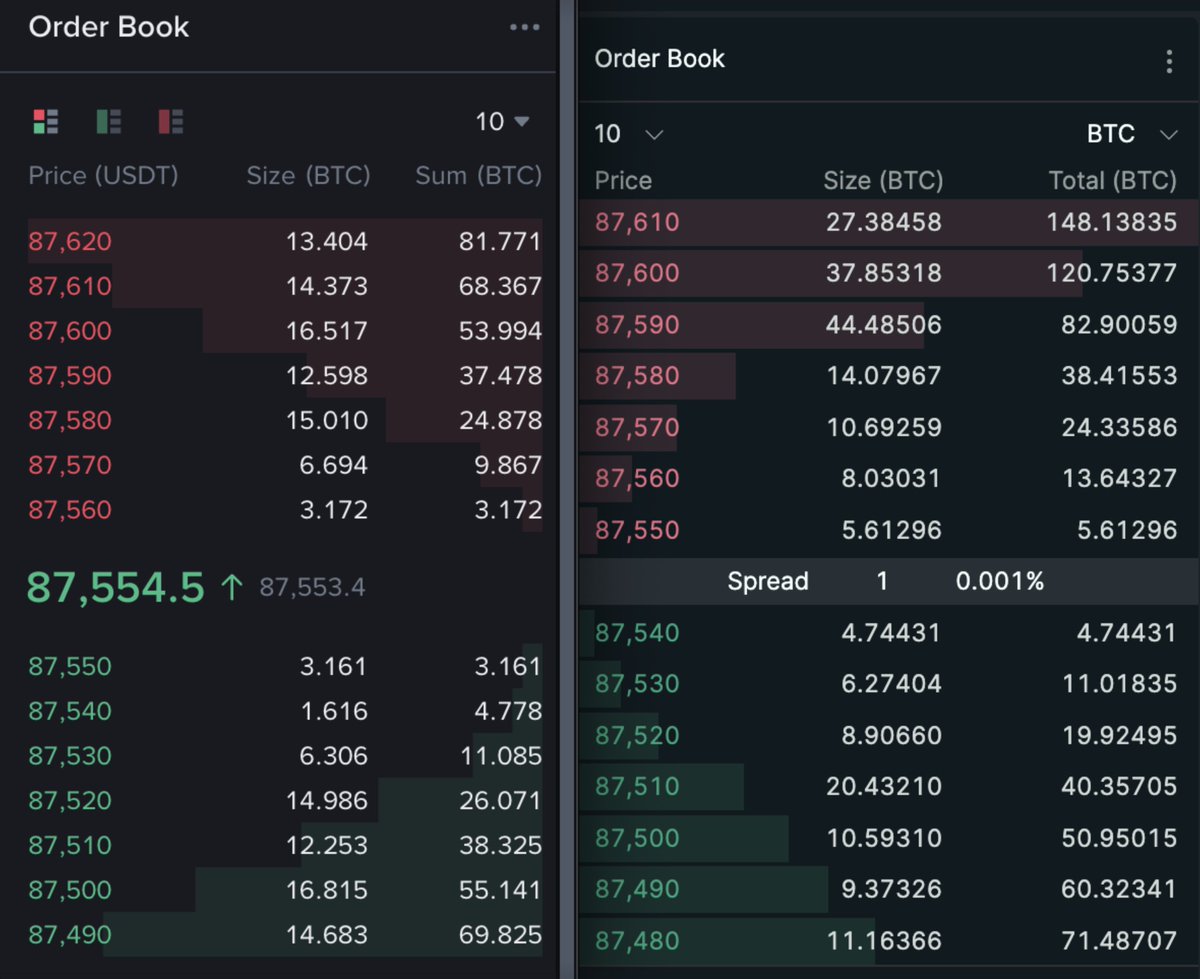
Hyperliquid has quietly achieved an important milestone of becoming the most liquid venue for crypto price discovery in the world. See below for side by side comparison of BTC perps on Binance (left) and Hyperliquid (right).
With HIP-3 teams leading the way, Hyperliquid has also grown to become the most liquid venue for perps on tradfi assets. Thank you to everyone's hard work as we upgrade the financial system and house all of finance.
HIP-3 open interest reached an all-time high of $790M, driven recently by a surge in commodities trading.
HIP-3 OI has been hitting new ATHs each week. A month ago, HIP-3 OI was $260M.
Integrity has always been one of Hyperliquid's core values.
The house of all finance must be credibly neutral. This means no private investors, no market maker deals, and no protocol fees to any company.
The initial state of any blockchain is a crucial part of its story that can never be erased. The original ethos of Bitcoin was a permissionless network accessible to all. Hyperliquid's genesis distribution followed this spirit, going entirely to early users with core contributors excluded. The full distribution is verifiable onchain without obfuscation.
This principle of fairness frustrates a few users and builders who are used to special treatment. It means that Labs has zero tolerance for team members with integrity yellow flags. It means we do things the hard way as a community. But the world deserves a financial system owned by the people, where fairness to all users is in the DNA. Nothing else is worth building.
Those who can, do
Those who can't, fud
Before writing a paper maybe learn the definition of what you are studying? ADL does not "transfer pnl to HLP." It treats HLP entirely symmetrically with users. **ADL has nothing to do with HLP or backstop liquidations**
ADL did not "destroy $653 million of pnl" either. If you don't understand what you're talking about, you are not qualified to spread lies masked by fancy ML terms to sound smart. It's a shame that these are the "academics" that the industry looks up to.
Hyperliquid supports permissionless perps on anything. As all of finance moves onchain, there is a billion dollar opportunity to build a mobile app for non-crypto users.
The two keys are:
1. seamless fiat onboarding
2. a mobile UX that non-crypto users love
Hyperliquid and HIP-3 perps offer the full backend liquidity infrastructure. Solve 1 and 2, and you have a product that markets itself: global, permissionless finance at your fingertips. Builder codes allow monetization proportional to volume flowing through the app, fully configurable per-trade.
Hyperliquid’s ethos is to let talented, hungry teams reinvent the pillars of finance. For those who specialize in UX and building magical user experiences, nothing stands between you and the empires to be built.
Congrats to Native Markets on pioneering the first aligned stablecoin on Hyperliquid! Looking forward to seeing a novel and compliant stablecoin grow with the protocol, bringing value to the entire ecosystem and onboarding the next wave of non-crypto users.
As of 13:10 UTC, Native Markets has upgraded USDH to qualify as an Aligned Quote Asset.
Now, when trading on markets quoted in USDH:
Takers enjoy 20% lower fees
Makers earn +50% rebates
Traders earn +20% volume contribution toward fee tiers
Congratulations to @tradexyz, @ventuals, and @felixprotocol on their HIP-3 launches!
It's exciting to see things come together after months of hard work building on the core protocol and deployer sides. Permissionless perp deployments are a massive step in Hyperliquid's journey to house all of finance.
On Hyperliquid, hungry and ambitious builders step up to reinvent core pillars of finance. Perps will bring unprecedented capital efficiency and price discovery to global markets. HIP-3 empowers any builder to upgrade financial markets by leveraging Hyperliquid's battle-tested onchain infrastructure.
Thank you to the builders working to push the frontiers of onchain finance. Thank you to the users for being there from day one with your support.