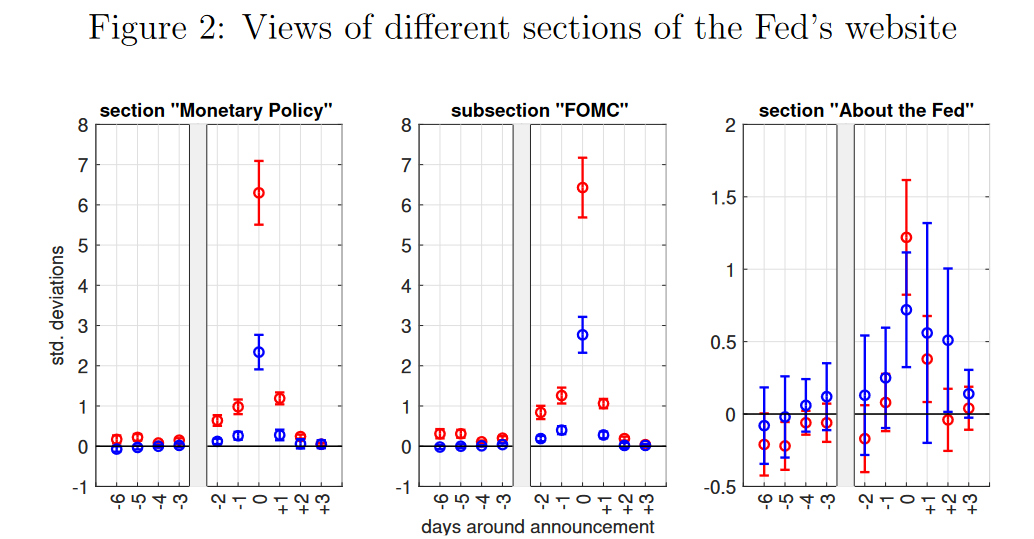
The #Fed just released its post-meeting statement - and markets parse every word of it. In a short note, @DavidFinck7 and I recently looked at the traffic on the Fed's website around FOMC meetings as a measure of market attention https://t.co/oBENnuIsxL
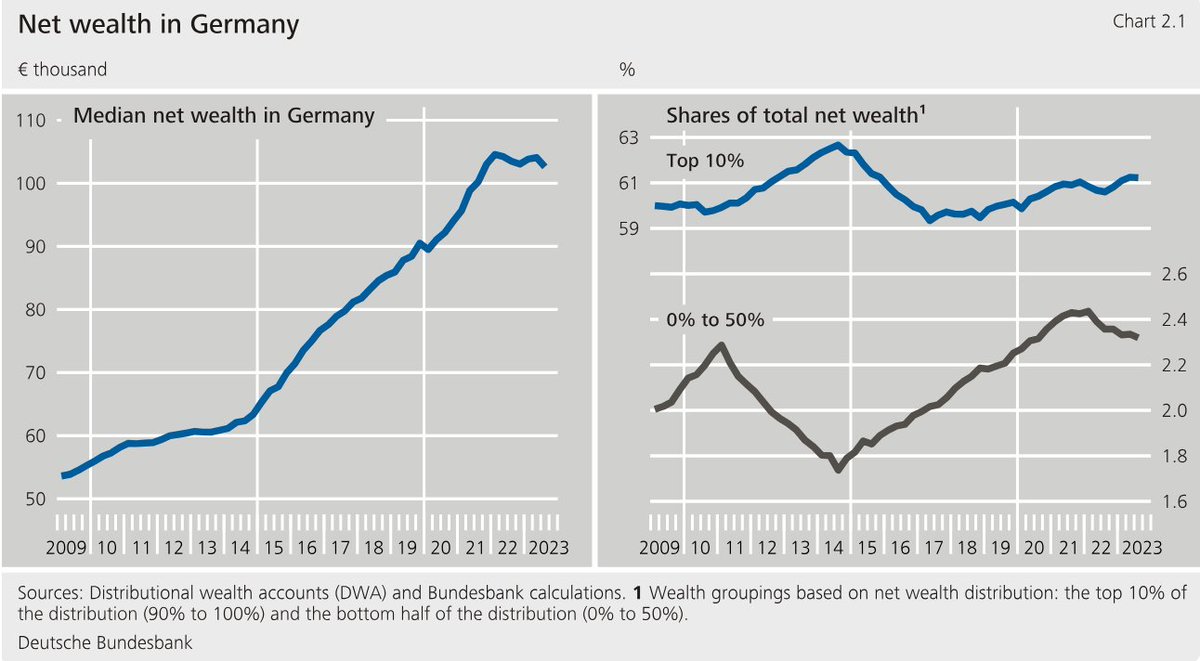
Mit der verteilungsbasierten Vermögensbilanz (Distributional Wealth Accounts, DWA) der privaten Haushalte in DE ist nun ein neuer Datensatz frei verfügbar. Im Monatsbericht stellen wir den Datensatz vor und zeigen einige Anwendungen 1/6 https://t.co/mxa6u9gTWj
Timely data for Distributional Wealth Accounts (DWA) of German households?
➡️here you go with the new QUARTERLY dataset provided by @bundesbank
➡️combines household survey with macro balance sheet data augmented by rich lists
➡️highly valuable for macro analysis
🧵\1👇
New paper with @DavidFinck7 and Mathias Klein: we compile a unique dataset linking micro price data underlying the Swedish PPI with administrative firm level data and provide new evidence on the inflationary effects of global supply chain shocks:
https://t.co/NKkBmOi9OI
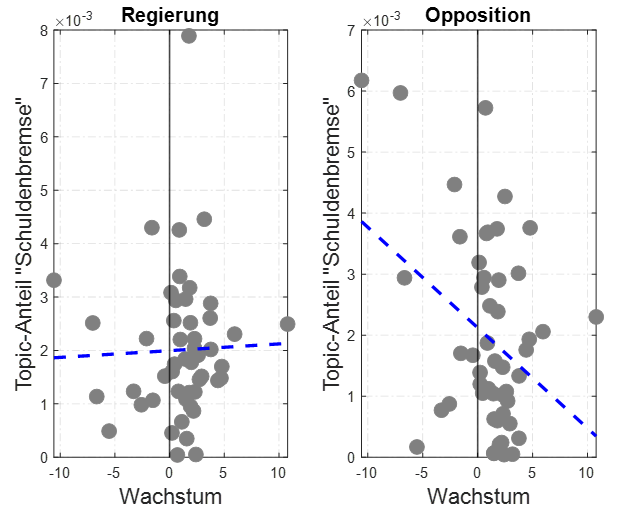
Wie und wann debattiert der Bundestag über die #Schuldenbremse? Hier die Frequenz des Topics "Schuldenbremse" in allen Reden seit 2009: Die Opposition reagiert auf das BIP, die Regierung nicht:
Schlechte Nachrichten für globale Lieferketten, aber sehr nützlich zur empirischen Identifikation von exogenen "supply chain disruptions" @DavidFinck7
https://t.co/OWg7dl7NSS
🚨Call for papers alert🚨
You can submit your paper to the 5th Conference on Behavioral Research in Finance, Governance and Accounting until June 30, 2023. We are very pleased to announce Prof. Theresa Kuchler as our keynote speaker!
Euch allen ein frohes neues Jahr 2023! Und wer den #Vorsatz hat einen Dr. in #VWL machen zu wollen, ich freue mich noch genau eine Woche lang auf #Bewerbungen. Kommt in ein cooles #Team mit anderen ganz frischen #Doktoranden. Alle Infos zur Stelle 👇 #econtwitter
Only 10 days left! We are looking forward to welcome you to our conference with exciting presentations and a keynote by @C_Laudenbach . You are not registered yet?
👇👇
https://t.co/pFmuCmap2z
Our results show that supply chain disruptions originating in China are an important driver for unexpected movements in industrial production, while
disruptions originating outside China are an especially important driver for the dynamics of consumer prices. 5/5
Our new paper (with @peterhtillmann ) estimates the macroeconomic effects of global supply chain shocks for the euro area. We combine business cycle variables with data from international container trade. 1/5
https://t.co/urUOgHQxXw
A shock of one standard deviation causes a fall in industrial production by about one percent and an increase in consumer prices by 0.3 percent.
We also use regional data on supply chain pressure to isolate shocks originating in China. 4/5