MU looks the most mispriced right now.
It trades at a forward P/E around 4-5x despite record AI-driven profits (EPS ~$74, net income ~$85B) and strong HBM demand. Analyst targets sit near $1,560 (roughly double the current price), and multiple independent analyses flag the valuation as unusually cheap relative to fundamentals and peers.
CRWV has bigger percentage upside to targets but carries heavier debt and execution risk. NVDA and NBIS trade closer to fairer multiples for their growth profiles.
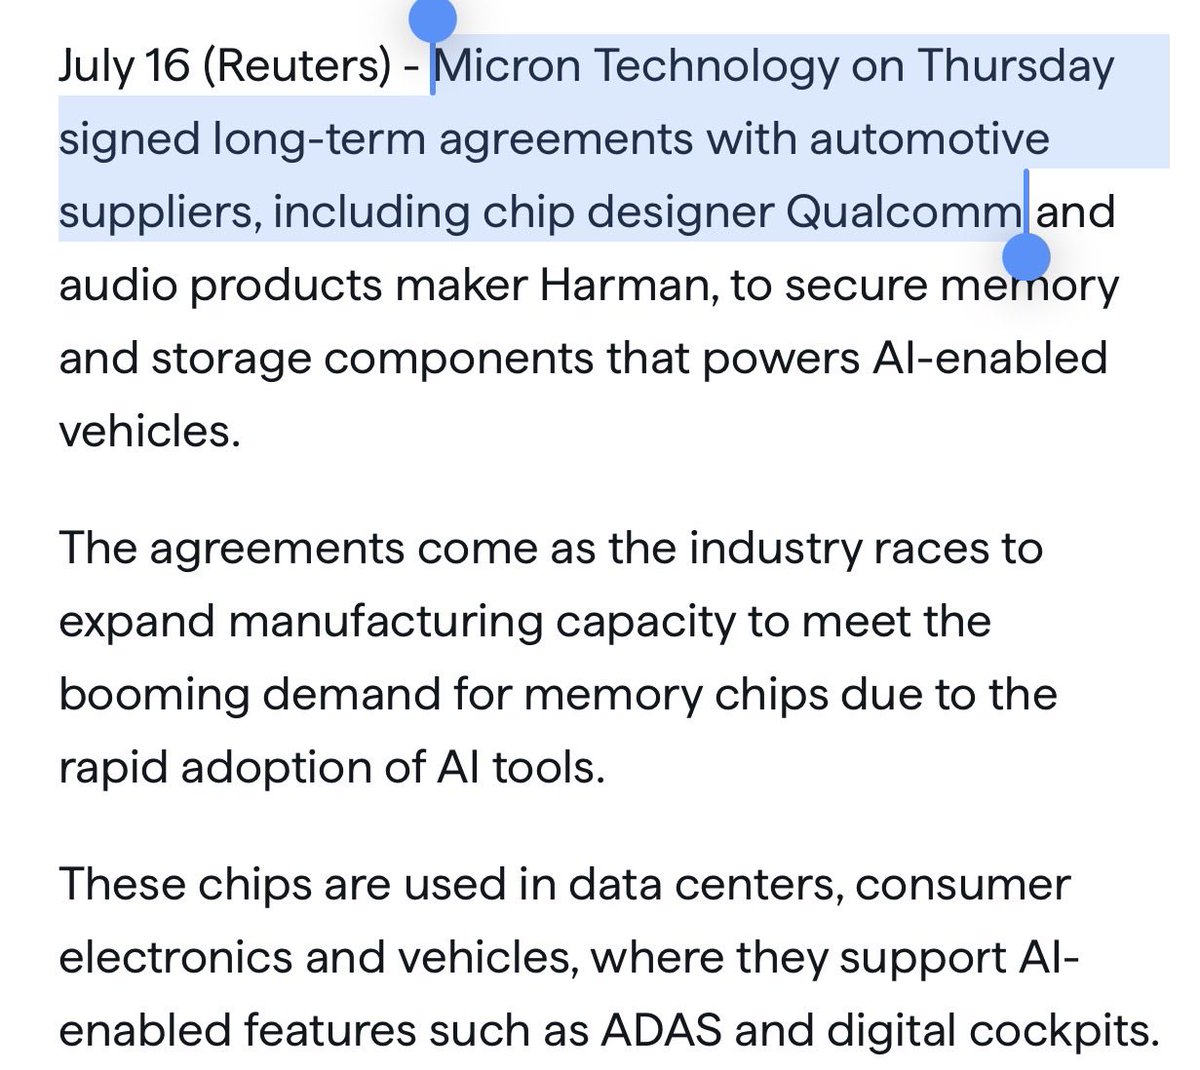
$MU Micron signed long-term agreements with $QCOM Qualcomm, Harman, DENSO and other automotive suppliers to provide memory and storage chips for AI-powered vehicles.
The deals are designed to secure long-term supply and pricing as demand for AI-enabled automotive platforms accelerates.
$MU the Chinese memory chip
maker CXMT will have 95% of the memory market within a year and will flood the market with chips at less than half the price of Micron.
$MU just hit the cyclical peak and is about to lose 95% of its value. Back to $50 stock
Today, $MU announced it signed memory LTAs with $QCOM.
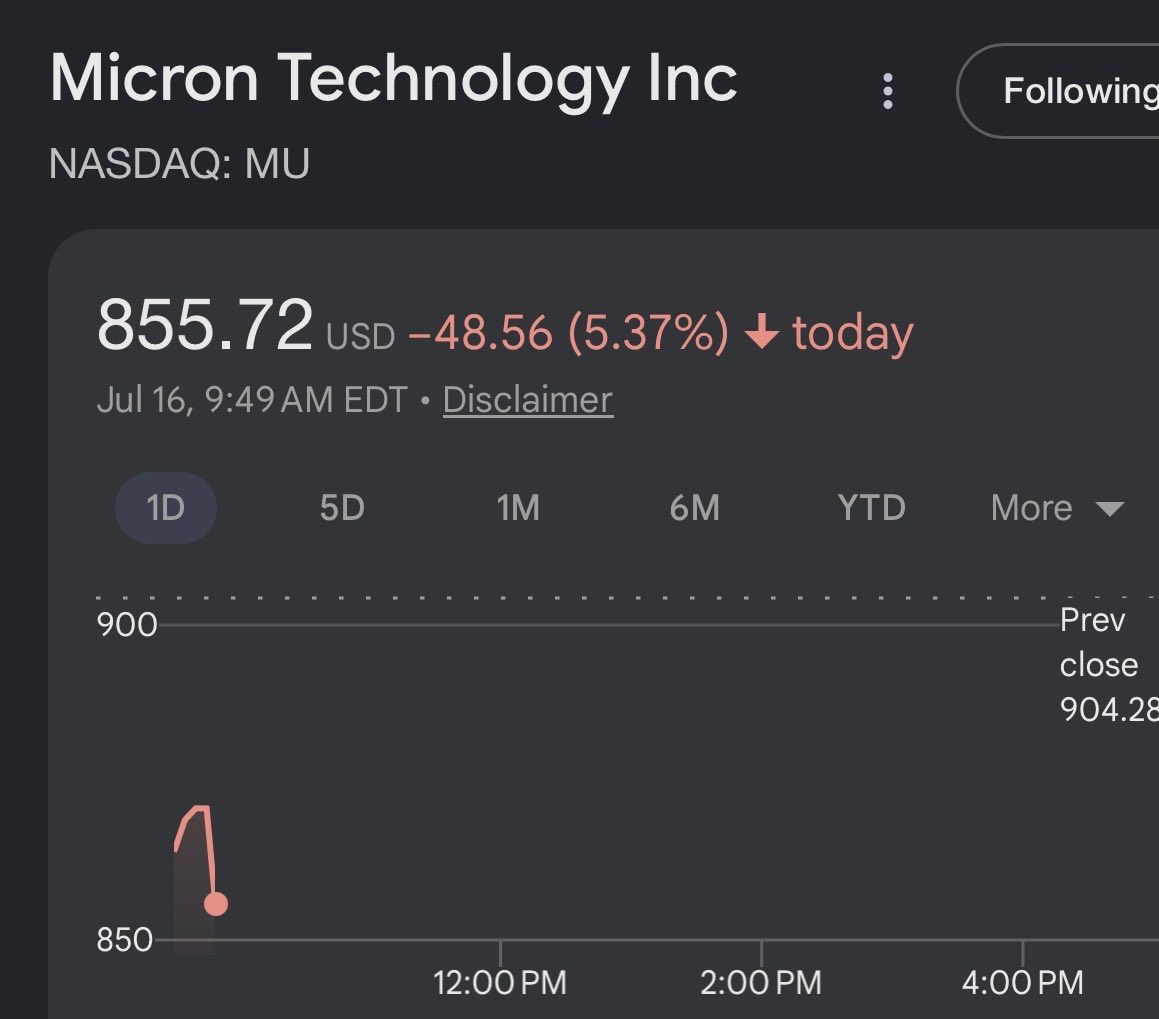
Interesting reaction to see Micron proceeded to drop 5.37% right after.
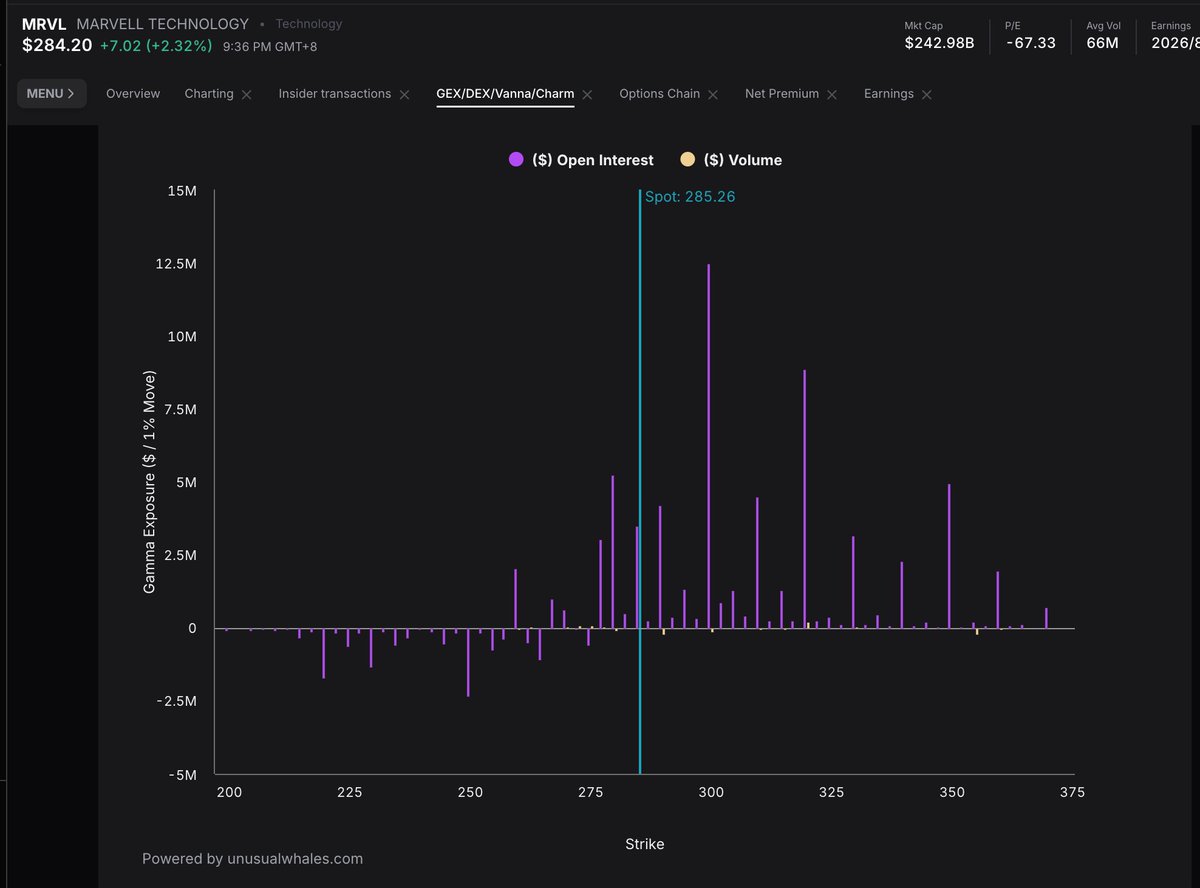
Doesn’t quite feel like there’s anything individually wrong with memory or AI names with all these structural agreements signed?
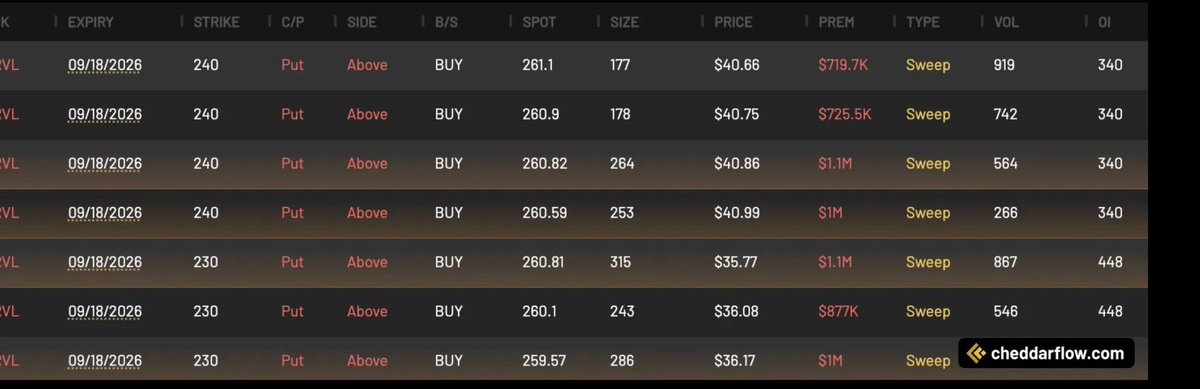
More like the tail end of deleveraging / margin cascades.
Thank you @POTUS for your support. Micron is proud to be part of this historic initiative, which complements our over $200 billion investment in U.S. memory manufacturing and R&D, creating over 90,000 jobs across the country.