Ce monsieur fera 3%
Alors que le constat est excellent
C’est le seul candidat, qui a un minimum de jugeote économique et pour lequel les constats sont vrais
Si les Français ne votent pas pour lui, alors les Français méritent clairement tout ce qui va leur arriver plus tard
Lisnard, à mon sens, peut être le président de l’après faillite
.@ironmantimholme says people who've spent years in the battery industry have earned "a healthy dose of skepticism."
@sciam looks at where the technology stands, and the work behind our Eagle Line and Cobra process. Read the full article from @pasternack: https://t.co/POS6FjYr4y
Ce weekend, covoiturage sur la route, et j'ai notamment un jeune de 20 ans dans la voiture avec moi. (oui je trouve le blablacar hyper intéressant et pas que pour rendre service quand je le peux).
Bref, on papote, et à un moment il me demande ce que je fais dans la vie. Je lui explique vite fait l'investissement, et la conversation dérive naturellement sur l'argent, l'épargne, tout ça ... le mur de la dette en France, le risque quasi certain que la retraite, il n'en aura pas (ou qu'il ne faut surtout pas compter dessus)... d'où le fait de dériver vers : c'est quoi la ou les solutions ?
Du coup, je lui pose une question toute simple. Je lui dis, imagine 2 potes. Le premier commence à mettre 200 euros de côté tous les mois dès ses 20 ans, pendant 10 ans, et après il arrête complètement, il ne touche plus à rien jusqu'à 60 ans. Le deuxième, lui, attend d'avoir 30 ans pour commencer, mais il met 200 euros par mois pendant 30 ans, sans jamais s'arrêter, jusqu'à ses 60 ans.
Je lui demande, à ton avis, lequel des deux a le plus d'argent à 60 ans ?
Il me répond, évidemment le deuxième, il a mis de l'argent 3 fois plus longtemps.
Et là je lui montre les chiffres. Le premier a investi 24 000 euros au total. Le deuxième en a mis 72 000, 3 fois plus. Et pourtant, avec un rendement moyen de 7% par an, celui qui a arrêté après 10 ans se retrouve à 60 ans avec environ 280 000 euros. L'autre, qui a cotisé pendant 30 ans sans interruption, termine autour de 244 000 euros. Moins d'argent au total, alors qu'il a versé 3 fois plus...
Il m'a regardé et il m'a dit un truc qui m'est resté, "ouais c'est pas con ça, on ne m'a jamais appris ça".
Et c'est exactement ça le truc. Ce n'est pas compliqué, ce n'est pas une formule d'investisseur chevronné, c'est juste que le temps travaille pour toi de manière presque injuste. Chaque année en plus au début pèse plus lourd que n'importe quelle année en plus à la fin. Personne ne nous le dit jeune, et c'est bien dommage, parce que ça change tout dans les décisions qu'on prend à 20 ou 25 ans.
C'est un peu ce que j'essaie de faire ici, Youtube, Podcast, IVT, Twitch ... prendre des trucs qu'on nous présente toujours de la même façon scolaire et ennuyeuse, et les raconter autrement pour que ça parle vraiment aux gens. J'y arrive pas toujours, mais quand ça marche, comme avec ce jeune dans ma voiture ce weekend, ça me rappelle pourquoi je continue à le faire. Et perso j'aurais bien aimé qu'on me dise ça à 20 ans, que ce soit concret, applicable, sans termes compliqués.
Je lui explique aussi que le mieux est de commencer même avec 50 ou 100 euros ... j'ai eu l'impression qu'il se disait : "oui mais si c'est pour les perdre..." ... sauf que au lieu de juste "s'intéresser" à tout ça, le meilleur moyen de le faire VRAIMENT, c'est de mettre un pied dedans...
J'en reparle plus en détail de tout ça dans le Morning Mood que j'ai fait ce matin : https://t.co/qIGt30rQRK
$QS: 🚨Fantastic new interview by Joel Franke, "The Data Center Engineer" with Shahar Noy, VP & GM Data Center, @QuantumScapeCo
Joel: So how far away from seeing this deployed in production? Are you running any pilot projects right now?
Shahar: Unfortunately, due to NDAs with customers and partners, I cannot share too much around this. We did announce availability of our cells, we did announce Eagle Line our pilot production line. So as you can imagine, the components are out there. We're [in the] process of finalizing system design around it. So, you know, hopefully you will see it in the market in the very near future. [chuckles]
https://t.co/o0O3ee9BjF
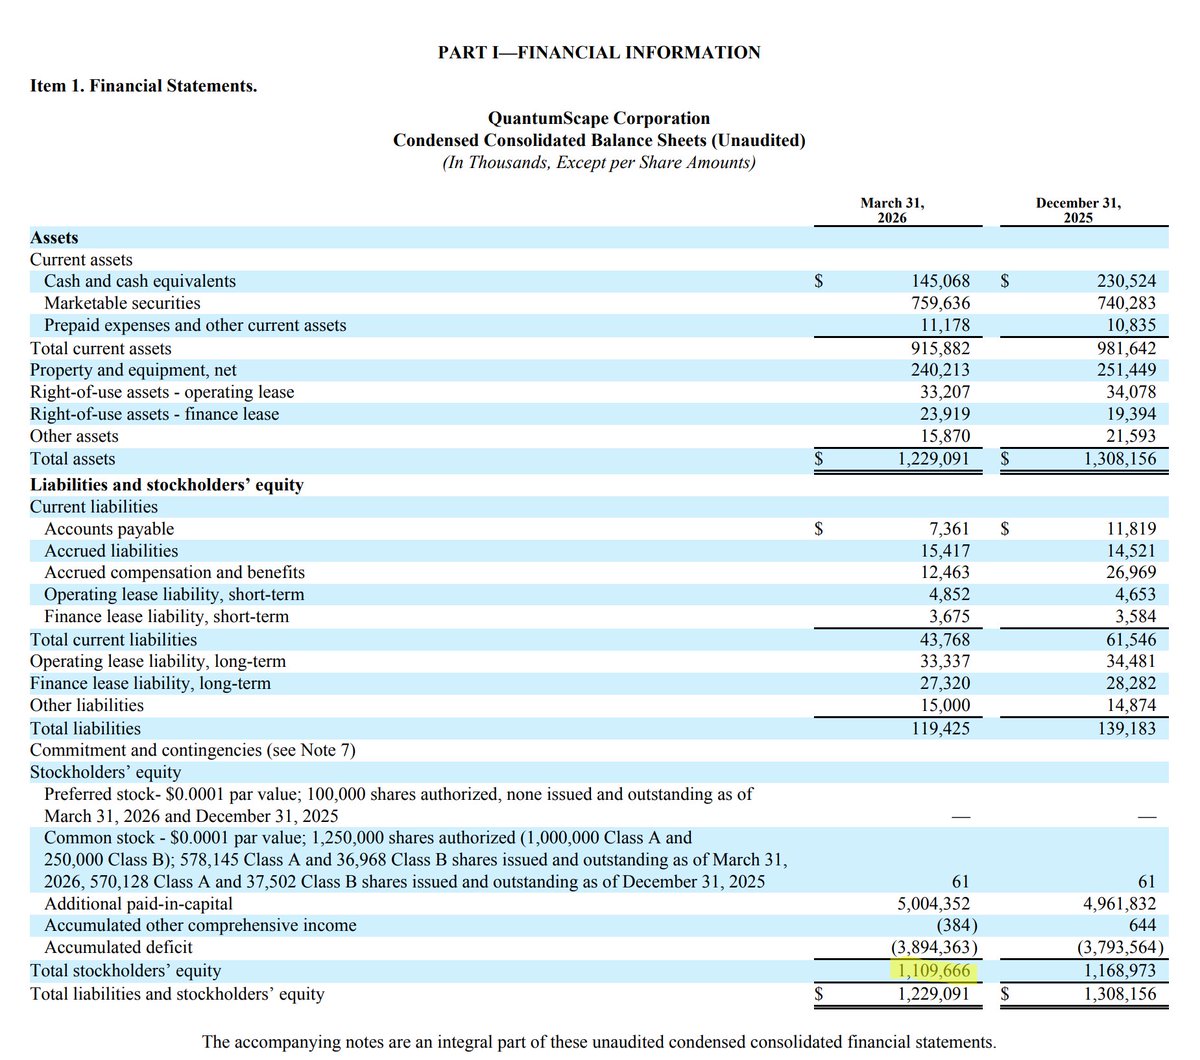
$QS: Closing at $5.90 per share today on July 16, 2026, @QuantumScapeCo is valued at 3.63B.
As mentioned in the April 24, 2026 10Q, the Company had 1.2B of assets including ~915M of cash/liquidity, and 119M of liabilities, resulting in a floor value of ~1.1B of total stockholders' equity.
This leaves 2.53B of valuation for everything else:
+ proven technology over 10 years and over 2 million tests
+ over 200 patents
+ partnerships with 4 of the Top 10 automotive OEMs
+ partnerships with various non-automotive companies
+ cash runway plus expected customer billings are anticipated to be sufficient to the end of 2029
It doesn't take much to see that $QS is on sale.
https://t.co/mdpqYL3U6u
$QS I think it’s time for @QuantumScapeCo management and @ironmantimholme to start providing more material disclosure. The technology story is strong and the execution has been real, but the market cannot properly value what it cannot see.
We have been waiting forever for details on the pure-play EV OEM partner. Too much teasing and coy playing. Is it real or not? It’s not unreasonable for the market to disbelieve. Why do shareholders never get this information? The newer talk about U.S. military and data center applications falls on deaf ears without concrete plans behind it. I believe it is real but I’m also losing my patience.
Same with the partners who remain unnamed and the @VW PowerCo commercialization timeline that stays vague. Naming names, putting specifics behind the timeline, and adding color on the OEMs at the JDA stage would go a long way.
Shareholders have been overly patient, and the fundamentals justify far better communication than we are getting. Give us the disclosures the story has earned.
Thanks for your understanding.
🚨Je construis une position sur Roblox 🇺🇸 $RBLX (monde immersif natif), Unity Software 🇺🇸 $U ( infrastructure des mondes 3D temps réel) et Snap Inc. 🇺🇸 $SNAP ( AR social/Communication visuelle).
Ils intègreront le segment "Usage convexity" de mon Portefeuille 6G.
Horizon 6/8 ans.
$QS Reverse-Engineering QuantumScape's OEM List, and Why the Data Keeps Pointing at $TSLA Tesla, Nissan, and $F Ford
Yesterday, QuantumScape ($QS) confirmed a multi-year joint agreement with $HMC Honda R&D covering both solid-state research and manufacturing, following Honda's completion of a technology evaluation that QS's CEO called one of the most rigorous assessments of its technology to date. That's the second major OEM after Volkswagen.
Here's the part worth sitting with: the geolocation data called Honda well before the press release. A while back, a redditor pulled mobile ad ID (MAID) data to map foot-traffic between QuantumScape's facility and OEM R&D sites, basically legal espionage, believe it or not! Honda R&D Palo Alto lit up as one of the strongest bi-directional signals in the set (4.71). Yesterday it became official.
So the method just got validated. VW was always public knowledge; Honda was not, until recently, though many of us found obvious clues (like the fact that Honda needed a ceramic separator process and they were stuck on it). That track record is the reason to take the rest of the list seriously.
Confirmed:
VW Group ($VWAGY) ✅
Honda ($HMC) ✅ (new, as of yesterday)
Here's where the same data plus public breadcrumbs point next.
Nissan ($NSANY). Spotted at the Eagle Line event and featured in shareholder materials, with a strong engagement correlation in the geolocation set (Nissan R&D Palo Alto to QS Factory, score 2.11). High confidence. Remember, Nissan is platform sharing so we are talking about Renault–Nissan (Infiniti)–Mitsubishi brands also.
Tesla ($TSLA). This is the one that lights up. Tesla HQ is the single strongest connection in the entire dataset (8.34), with Tesla Kato Road adding a second bi-directional signal (2.37). Tesla co-founder JB Straubel sits on the board, now on the strategic board. Tesla is very likely the "pure-play" EV OEM working with QS.
Ford ($F). The most likely other OEM. The Ford and Solid Power ($SLDP) JDA has been wound down. Solid Power's 2025 10-K states that, effective Dec 31, 2025, the companies amended the JDA "in connection with the winding up" of their cell-development work and extended it only through March 31, 2026. A freed-up Ford plus a 6.55 bi-directional geolocation score with QS (strong in both directions) is hard to ignore. Ford clearly does not see future value in Solid Power's SSB technology, which is well known to be inferior to QS's.
Wild card: Rivian ($RIVN). Closely aligned with VW Group, which holds a direct equity stake in Rivian and has committed up to $5.8 billion through 2027, including a 50/50 joint venture, Rivian and VW Group Technology. That JV is built around software and zonal electrical architecture rather than batteries, so a QS-to-Rivian battery path would be a separate step, but the depth of VW's involvement is why Rivian stays on the radar at all. The base case is that QS could reach Rivian via the VW vector regardless, though the data leans Tesla as the standalone EV name here, not Rivian.
One more data point, and it comes from Factorial's own lead OEM (thanks to @Defiantclient2 for finding it). Mercedes-Benz's infographic for the 1,205 km Stuttgart-to-Malmö drive lists a pneumatic cell support system holding a constant 28 bar as a feature of the Factorial-cell EQS ($FAC). An active pressurized-air system at a constant 28 bar is not something you fit into a motorcycle or a cost-sensitive mass-market pack. Contrast that with QuantumScape, which ran its anode-free QSE-5 cells in a Ducati V21L at IAA Munich, a bike with no room for a pneumatic rig, precisely because its ceramic separator is built to operate at comparatively low external pressure. All roads keep confirming what the thesis laid out a long time ago.
If I'm wrong, I'll own it. But this looks like the OEM list.
I've NEVER BEEN MORE BULLISH $QS 🚀🚀🚀🚀
$QS QuantumScape - This is getting interesting🔋 - Weekly Chart
QS is the premier solid-state battery company - look it up, they are WAY ahead.
TA: Higher lows and a huge volume shelf, next fib target showing $12.76. Once flipped to support, $18.56 incoming.
$QS presentation to Wells Fargo. I love that they are still confident and feel they have a significant, no compromise lead over the competition. 🔋
https://t.co/E1HtbN1Zwz
$QS
Quick weekend TA 📊
For now, the uptrend line that started from the April lows is still holding, but Friday's candle and last week's overall action look pretty ugly.
After 9 weeks of moving up, a pullback is perfectly normal. Nothing is broken yet, but we failed to break out of this symmetrical triangle (lots of upper wicks showing rejection).
To keep the bullish trend alive, we are going to need a solid bounce next week!
My personal take: we tried to break out of this triangle for almost the entire week and failed, ultimately getting strongly rejected on Friday (due to macro news). It shows strong selling pressure (large red candle + high volume). We'll need to wait for the next candle to confirm, but I believe we should see a bounce. 🚀
C’est incroyablement bien réalisé et cela correspond assez bien à la vision que je me fais de l’évolution des choses. Je ne dis pas que c’est souhaitable ou non, mais je pense que c’est l’objectif poursuivi par certaines personnes.
J’avais d’ailleurs déjà esquissé un schéma similaire : à terme, les robots devront être capables de concevoir, fabriquer, réparer et améliorer d’autres robots.
Cela permettrait de supprimer de nombreuses contraintes humaines, qu’il s’agisse de la fatigue, des maladies, des conditions météorologiques ou encore des limites biologiques.
Dans cette logique, les futures colonies notamment dans des environnements hostiles ne seraient probablement pas constituées de grandes populations humaines. Une grande partie du travail initial pourrait être réalisée par des systèmes autonomes capables de se reproduire industriellement et de préparer l’infrastructure avant l’arrivée de l’homme.
$QS I think QuantumScape is making it very clear that we are going to be hearing big news soon around SSB for data centers and grid storage.
@ironmantimholme and @QuantumScapeCo keep posting about the topic. They are doing interviews, showing up at AI/data center events, and getting everyone ready for the reveal.
QuantumScape’s Shahar Noy, GM and VP of Data Center, is at the Bloomberg Tech Summit in San Francisco today, where Dario Amodei and major AI, semiconductor, and infrastructure executives are in the room. That is exactly where QS should be if the next leg of the thesis is AI infrastructure, power, storage, grid reliability, and next-generation batteries.
Meanwhile, we find out that $TSLA co-founder JB Straubel is also focused on batteries, data centers, and grid energy, not just EVs, and is moving from the QS Board of Directors to the new QS Strategic Advisory Board.
His quote says it all:
“There is a profound need for next-generation batteries across many different applications, from electric vehicles to AI data centers.”
EVs, AI data centers, grid storage, and next-generation battery architecture are all converging here.
$QS feels like it is getting very close to telling the market exactly where this is going.
Chart shows we are still in a new uptrend which is getting better. Past $10 soon!
$QS 🚨
$FLNC (Siemens + AES, a grid-storage heavyweight) has a multi-year deal to put QuantumScape solid-state cells into stationary storage.
Now they're building out global battery test labs across US 🇺🇸 Germany 🇩🇪 India 🇮🇳.
Test infra doesn't get built for tech that's going nowhere. The runway is being paved.
Next domino: large-scale supply agreement. 👀🔋🅾️
Update: thesis confirmed within hours.
Shahar Noy just posted on LinkedIn. His actual resume is even bigger - three decades building data center silicon at MediaTek, Intel, Marvell, Micron, SanDisk, and Broadcom.
His title: VP & General Manager of the Data Center Business Unit. Not a side initiative. A dedicated BU.
He names the hyperscalers he's worked with directly - Microsoft, Google, Meta, AWS - and says every single one is hitting the same wall: more AI compute requires greater energy safety, more power density, and more predictable power.
His words: "QuantumScape's solid-state cell technology is, in my view, the most credible answer to that problem."
He calls building the Data Center BU a "once in a career" opportunity.
You don't leave three decades of semiconductor leadership to join a pre-revenue battery company unless you've seen the pipeline behind the curtain.
The more I dive deep into the solid-state battery space and the opportunity, the stronger the $QS @QuantumScapeCo thesis gets.
I keep pulling threads and every single one leads back to the same place. Let me show you what I found.
🧵
First - the macro setup.
Data centers now eat 5% of all US electricity. McKinsey says that doubles by 2030. Goldman says data center power demand grows 175% this decade - that's like adding an entire top-10 country to the global grid.
And we're already failing. Bloomberg reported 30-50% of planned 2026 US data centers are delayed or canceled. Not because of money. Not chips. Because we literally can't plug them in.
@KobeissiLetter nailed it: "Energy will soon be the AI bottleneck."
It already is!
So what's the fix? Follow what @nvidia is actually doing.
@nvidia is building 800V DC power architecture for next-gen AI factories. 1 MW per rack. Shipping with Kyber in 2027. They've pulled in Vertiv, Schneider, Eaton, TI, Infineon, STMicro - the entire power ecosystem.
Why 800V DC? Traditional AC physically cannot push enough watts into a rack at AI-scale density. Enteligent's white paper showed DC-native racks generate 10-15x more revenue per square foot. TI unveiled a full 800VDC reference architecture at GTC 2026. This is happening now.
Here's the part that gets me very excited!
Vertiv - NVIDIA's primary power infrastructure partner - said their 800 VDC platform is being designed with INTEGRATED ENERGY STORAGE.
Not backup. Not UPS. Integrated into the architecture.
Battery storage. Baked into the rack. By design.
So what battery do you put inches away from GPUs worth half a million dollars?
→ Energy-dense (every square inch is revenue)
→ Zero thermal runaway (lithium-ion fire next to your H100s = game over)
→ High cycle life at rack-level charge/discharge rates
→ Safe at 800V operating voltage
Lithium-ion? Thermal runaway. Can't risk it next to the compute.
Lead-acid? Not close on density.
Flow batteries? Way too big.
Solid-state checks every box.
Now here's where it gets interesting - the technical moat.
$QS isn't just "a solid-state battery company." Look at what they've actually built:
→ 300+ patents covering the ceramic separator and anode-free cell design. This isn't one patent. It's a fortress.
→ Anodeless architecture - zero excess lithium, no host materials. This is what enables the energy density advantage.
→ Their ceramic separator is the only one that's demonstrated dendrite resistance at automotive-grade current densities for 800+ cycles at room temperature. Nobody else has shown this. Not Toyota. Not Solid Power. Not CATL.
→ 1,000 cycles with 95% capacity retention. Published data, not a press release.
→ Cobra manufacturing process - 25x faster heat treatment, fraction of the floor space vs their prior Raptor process. This is how you go from lab to factory.
→ Murata AND Corning - two of the world's best ceramics companies are both investing in QS-proprietary tooling to produce the separator. When the two best in the world independently validate your manufacturability, that tells you something.
Competitors? Solid Power is on sulfide electrolytes - different chemistry, different problems. Toyota says 2027-2028. CATL says 2027. BMW is still on prototypes. $QS has cells on Eagle Line today.
The moat isn't just the tech. It's 300 patents + the only proven dendrite-resistant ceramic separator + a manufacturing process that actually scales + two world-class production partners already building the tooling.
Good luck replicating that in 2 years.
The recent hiring in 2026 confirms the thesis entirely!
→ VP/GM from @MediaTek's data center AI infrastructure group
→ @nvidia / @Cadence ex-CFO Geoff Ribar on the board
→ Ex-CTO of L3Harris and ex-President of Aerojet Rocketdyne on the board
→ Commercial Counsel with STEM background and licensing focus
→ Licensing product strategy role to define technology transfer value prop
→ @ironmantimholme (CTO) is publicly framing energy delivery as the next AI bottleneck
They're not talking about pivoting.
They already hired for it.
They already have board governance for it.
They're building the cells for it.
Connect the dots:
AI energy bottleneck is here → NVIDIA building 800V DC → architecture requires in-rack storage → solid-state is the only chemistry that fits → $QS has the deepest technical moat, 300+ patents, the only proven separator, and is already staffing for data center and defense commercialization
Market still think this is an EV battery company.
That's the edge.
$QS