@sububoston We won’t see that and neither will management. It’ll stay blinded to everyone except a third party that will directly provide it to the FDA. Integrity of SOL-R is critical as it’s needed for filing in EU/JP//CN etc
$OCUL will file in a few weeks. Approval 2H -27. TKI-class is safe. Axpaxli BCVA curve doesn’t decay as $EYPT, but stabilises. SOL-R will hit NI vs 2mg. Will be marketed as maintenance, enormous market. Patients will start on eylea biosimilar, then be put on Axpaxli q6m/q9m+.
@veremcocapital I still think it’s $KOD showing they have a single agent 6 month product. Sure there are questions about durability when redosing, and many loading doses but data was clean overall. I think $OCUL is differentiated, but it’s now clear they won’t be competing against q8w eylea.
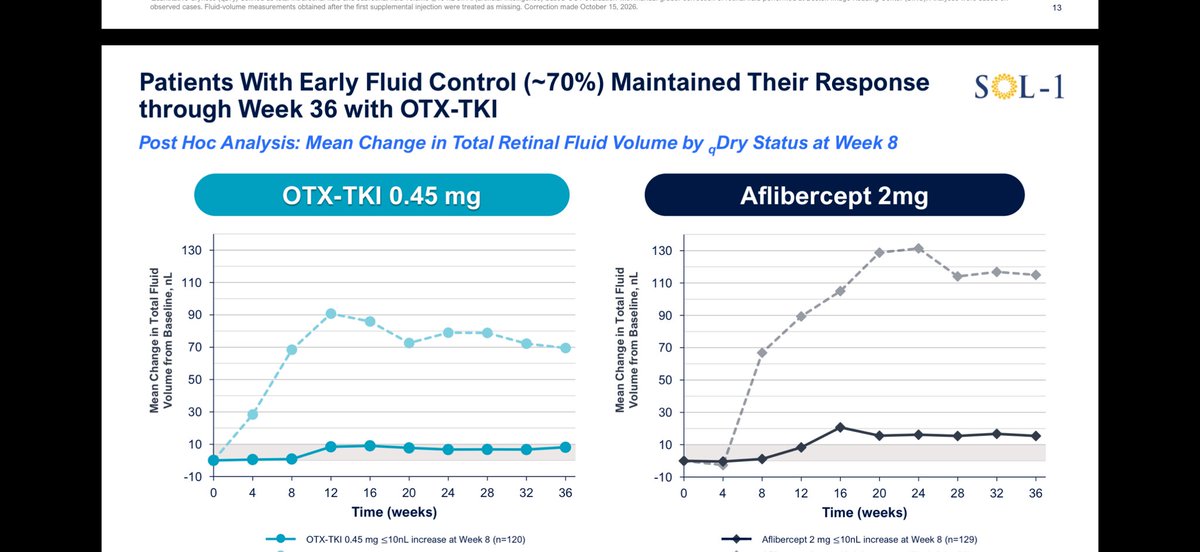
$OCUL latest slide (post-hoc) show that the ~30% that does not respond well to Ax or Eylea can be identified week 4-8. In Axpaxli group, the remainder, 70%, all get to 9 month.
@DescartesIdea XBI is down which doesn’t help. I think they’ll file and get approved. Stock will go up a bit but invstrs are uncertain about sales ramp pre SOL-R. 1st study is viewed as oddly designed and hard to interpret. That is the cost Dugel pays for superiority path, that path isn’t free
900m EV for $OCUL is nuts when clinical risk is behind us. There’s regulatory & commercial risk left. With SOL-R rescue criteria applied, which are inline with industry practice, 77% of patients in SOL-1 are rescue free at 6 months. This is a phase 3 program with an SPA.
In a Ph3 clinical trial in wAMD with rescue criteria 75um + 5 letters loss, to get 77% of patients to 6 months without rescuing is that number good or not? $KOD, $EYPT, $OCUL, $REGN, $RHHBY $XBI
$ocul $kod If both get approved, Axpaxli having better durability, on label and in practice, is close to a given. Sustained release vs bolus is structural. If durability drives share, $6B vs $1.5B is a wide gap.
The path to market share is to have durability that meets or exceeds the other products on the market. $OCUL is weeks from submitting a product that is almost guaranteed to get a product approved with a label that will read durability of 6 months to 1 year. They will be able to advertise that this works for up to one year. Anyone who wants to grab a significant market share will need to be able to say the same.
@Sjfms1Steven Important events ahead; filing, approval, labelling and then pre-SOL-R it’s quite unclear what eventual ramp would look like, but at this level I feel very confident holding.
$KOD EV is $6.1b and $OCUL EV is $1.1b, difference is 5.2x. $KOD data was good, but feels priced for absolute perfection. $OCUL at $7.50 feels like an opportunity.
@DescartesIdea My expectation is real/actual duration out in practice in line with Vabysmo/HD or marginally longer (~15%). I see it as a evolutionary improvement on HD, not a new durability category, ie very little changed for $OCUL.