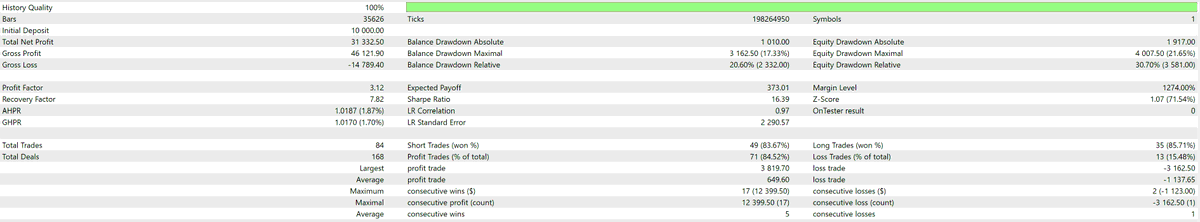
Thank you @MrMilkTrading and @etbent1 for this great strategy! I rebuild it in mql5 as well and got insane results with real ticks. This is Nasdaq and S&P500 in M5 and M15!
🚨Free source code in the discord of @PropQuantX
Took you up on the "test it yourself."
Rebuilt it from the Pine source — an MQL5 EA and a Python twin, neither tuned toward your numbers. Ran it on USTEC instead of NQ.
You: 12,994 pts (2019–26)
Me: 13,038 pts (2020–26, where my data starts)
Different index, different window, ~2% apart. It replicates.
First thing I checked was whether it's just beta, since the index rose the whole time. Buying every open in the same 9:30–11:00 window gives +6.5
pts/trade over 1,716 trades. Your signal: +35.0 over 373. It also beats 1000 out of 1000 random-entry variants. The edge is real.
Two changes improved it, and both held on train (2020–23) and test (2024–26):
1. End the window at 10:00 instead of 11:00. Profit factor 1.97 → 2.34, and return/drawdown roughly doubles. It's monotone — every widening of the window makes it worse. That fits the construction: ATR(14) on a 10m chart is 140 minutes, so at 9:30 the normalizer is all premarket, and by 11:00 it's full
of RTH bars. The 3-ATR threshold isn't measuring the same thing anymore.
2. Exit at 61.8 rather than the full traverse to −100. Profit factor 1.97 → 2.16. Saty already plots that level.
Your threshold is right where it should be, though — I swept 80 through 120 and 100 is a clean peak on both halves, not a fitted edge.
On the missing stop, I measured instead of guessing. Winners' MAE: median 35 pts, p95 137. Losers: median 117. Any stop tighter than 150 costs real money — at 60 pts you give up 53% of total profit, at 100 pts 21%. At 200 pts it costs 1%. So there's room for a catastrophe stop, but not for a working one.
One caveat worth flagging: US500 gives the same answer, but only in the back half. Its 2020–23 profit factor is 1.14 against USTEC's 1.60.
Result of the strategy:
- Asset: BTCUSD
- Timeframe: H1
- Direction: Long only
- Period: 1.1.2020 - 31.12.2025
- No optimization
We would need the ATR stop, the EMA slow and EMA fast values to get similar results.
Free source code in the discord. No financial advice.
HOW TO BUILD YOUR FIRST TRADING STRATEGY
Don’t start with random indicators.
Start with one question:
Why should this idea make money?
That’s your hypothesis.
STEP1️⃣: BUILD THE RULES
Keep it simple.
Example:
Market: Bitcoin
Direction: Long only
Entry: Fast EMA crosses above Slow EMA
Exit: Opposite EMA cross
Stop: ATR-based
No discretion.
Everything must be objective and testable.
STEP 2️⃣: BACKTEST IT
Now test the exact rules over a large sample.
Look at:
Profit Factor
Drawdown
Trade Count
Sharpe
Win/Loss distribution
Don’t ask only:
“Did it make money?”
Ask:
“Does the behaviour actually look robust?”
STEP3️⃣: TRY TO BREAK IT
Test:
Different parameters
Different markets
Different periods
Higher costs
Out-of-sample data
If it survives…
you may actually have something worth trading.
Hypothesis → Rules → Test → Validate
That’s how you build your first system.